
Ascentage Pharma Group International (SEHK:6855) Ties Up With Peking University, Is The Upside Priced In?
Why Ascentage Pharma Group International Is Back On Investor Radars
Ascentage Pharma Group International (SEHK:6855) has moved into focus after agreeing to a research collaboration in hematologic oncology with Peking University, tying its cancer pipeline more closely to academic and clinical resources.
At a HK$31.7 share price, Ascentage Pharma Group International has seen a sharp 1-day share price return of 7.24%, which contrasts with a weaker year-to-date share price return. The 1-year total shareholder return has declined 57.9%, while the 3-year total shareholder return remains positive at 48.83%. This suggests that current momentum is picking up after a much tougher stretch for longer term holders.
Scan other clinically focused biotechs that are moving on fresh research partnerships with universities and hospitals through our hand-picked list of 615 high quality undiscovered gems
The Peking University tie up and 7% jump hint at something more than a mood swing around Ascentage Pharma Group International. Is the current HK$31.7 price grounded in the underlying pipeline economics, or is it simply reflecting a reset in sentiment?
Most Popular Narrative: 27% Undervalued
Against the HK$31.7 close, the most followed valuation story for Ascentage Pharma Group International points to a higher fair value of HK$43.67, built on detailed assumptions about its late stage hematology pipeline and future earnings profile.
The company's expanding late-stage pipeline, with multiple Phase III global registration trials for both Olverembatinib and Lisaftoclax and several additional compounds advancing, increases the likelihood of future product launches and diversified revenue streams, improving long-term revenue and potentially boosting net margins. Advancements in clinical differentiation of lead compounds, for example, the convenience and tolerability of Lisaftoclax's dosing regimen compared to competitors and Olverembatinib's efficacy in resistant mutations, enhance competitive positioning, which can contribute to premium pricing and improved gross margins.
See why 2 investors see Ascentage Pharma Group International as 27% undervalued.
The narrative framework uses a 7.58% discount rate and assumes Ascentage Pharma Group International reaches CN¥1.2b in revenue and CN¥206.1m in earnings by 2029, with the share price then trading at a P/E of 103.7x, to back into the HK$43.67 fair value estimate. That view also factors in a 7% annual increase in the share count over the next three years and weighs both execution risk around Phase 3 programs and the potential cash flow contribution from existing partnerships.
Result: Fair Value of HK$43.67 (UNDERVALUED)
Still, a faster ramp in olverembatinib sales in China or stronger than expected Takeda partnership milestones could quickly challenge this more cautious Ascentage Pharma Group International narrative.
Find out about the key risks to this Ascentage Pharma Group International narrative.
Another View: What Multiples Say About Ascentage Pharma Group International
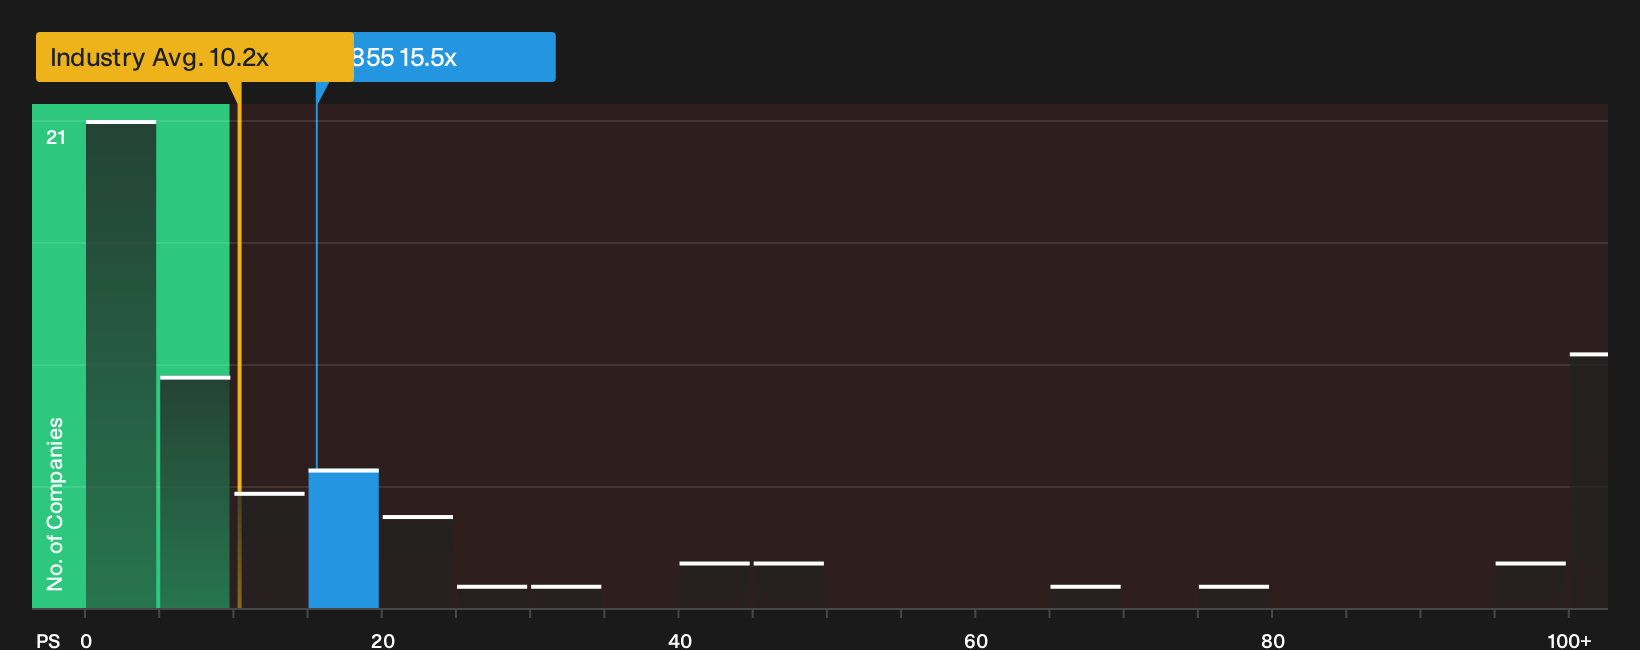
The story looks different when you strip it back to what investors are paying for today. Ascentage Pharma Group International trades on a P/S of 15.5x, above both the Hong Kong Biotechs industry at 10.2x and its own fair ratio of 13.8x. This points to a richer entry price than the first narrative suggests.
For anyone weighing valuation risk against upside potential, the numbers here raise a simple question. How comfortable are you paying a premium multiple for a business that is still loss making, while the market could move closer to that lower fair ratio over time and compress returns on the way.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Ascentage Pharma Group International story so far. If you want to move fast and test the bullish and cautious angles against your own expectations, start by weighing both sides of the ledger through 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Ascentage Pharma Group International?
You have seen how complex the Ascentage Pharma Group International story can be, so do not stop here when there are other opportunities waiting to be checked.
- Target potential mispricings and let valuation work in your favor by scanning a curated set of 178 high quality undervalued stocks before the crowd catches on.
- Build a sturdier portfolio base by focusing on companies with strong financial footing and dependable fundamentals through the list of solid balance sheet and fundamentals (198 results).
- Review high yield opportunities screened as 159 dividend fortresses while yields and entry points still look appealing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com