
Learn Why The Bull Case For Ally Financial Stock Could Change Following Guidance Reaffirmation
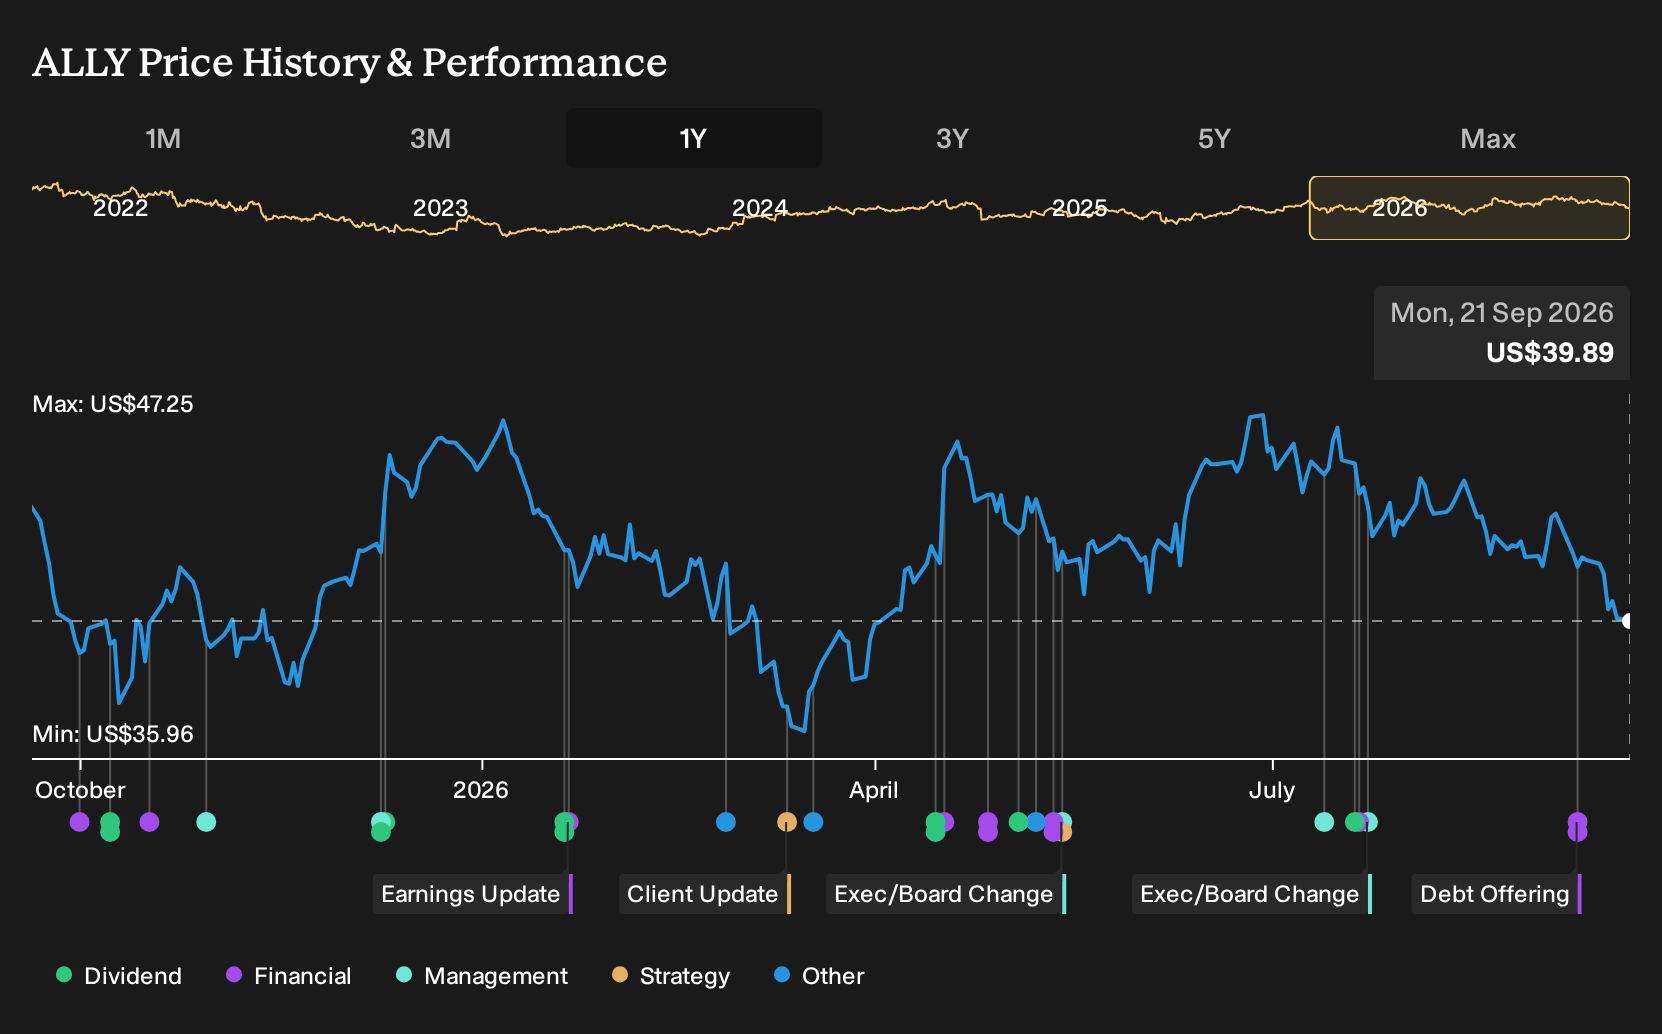
- Ally Financial completed a US$750 million fixed to floating rate senior unsecured note issuance due 2030, alongside reaffirmed guidance on net interest margin and retail auto net charge-offs despite lease losses from recalled Stellantis vehicles.
- The mix of callable variable rate debt and steady margin and credit loss guidance reflects how Ally Financial is seeking to balance funding flexibility with pressure from specific auto lease exposures.
- Investors will now be watching how Ally Financial's reaffirmed net interest margin outlook influences its broader investment narrative over the long term.
Ally Financial Investment Narrative Recap
To own Ally Financial, you need to believe in a digital bank that leans hard into auto and corporate lending, manages credit tightly, and keeps funding costs in check. The reaffirmed 3.6% to 3.7% net interest margin outlook suggests management sees current pricing, deposit costs, and loan mix as workable, even with pockets of stress.
The Stellantis related lease losses, about US$20 million in the third quarter, look manageable against a US$7.9b revenue base but do highlight concentration risk in auto. The near term swing factor remains credit performance in retail auto. The biggest watchpoint is any broad deterioration in consumer credit that pushes losses above guidance.
The US$750 million fixed to floating senior unsecured notes due 2030 matter because they sit at the intersection of funding and margin. A callable, variable rate structure gives Ally Financial room to adjust its liability stack as rate conditions evolve, which directly feeds into the net interest margin guidance investors are tracking.
For you, the key question is execution. Can Ally keep remixing into higher yielding retail auto and corporate finance loans, while lease issues from recalled Stellantis vehicles and any future product specific problems stay contained inside current loss assumptions? Funding resilience from this bond issuance supports that effort, but credit discipline will decide how attractive that NIM guidance is over time.
Ally Financial's narrative projects US$9.8b revenue and US$1.9b earnings by 2029. This implies 8.5% yearly revenue growth and an earnings increase of about US$0.6b from US$1.3b today.
Uncover why Ally Financial's fair value indicates a potential 35% upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view focuses less on Ally Financial's auto credit risk and more on rising regulatory costs. The most cautious analysts, using pre news estimates, were only penciling in about US$9.9b of revenue and US$1.8b of earnings by 2029. That is a meaningfully tougher story than consensus, and this bond deal could eventually reshape both narratives.
Explore 3 other Ally Financial fair value estimates, including one that suggests it could be worth just $46.64.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ally Financial research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Ally Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ally Financial's overall financial health at a glance.
Looking For More Ideas Beyond Ally Financial?
If Ally Financial has sharpened your focus on balance sheet strength, credit quality, and funding mix, it can help to line it up against other businesses with similar traits. The Simply Wall St Screener lets you filter for those characteristics quickly so you can build a watchlist that matches your own risk and return preferences.
- If you want potential mispricings where quality and valuation meet, scan a focused set of 33 high quality undervalued stocks that share robust fundamentals and disciplined capital allocation.
- For investors who care most about stability and capital preservation, narrow your search to a curated pool of 30 resilient stocks with low risk scores that score well on earnings consistency and financial strength.
- To find companies that might not be on every headline list but still show solid numbers, filter through a targeted group of 16 high quality undiscovered gems with metrics that can justify a deeper look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com