
How Investors Are Reacting To Extreme Networks (EXTR) AI Networking Launch
- Extreme Networks has rolled out Extreme Agent ONE Coworker to all Extreme Platform ONE subscribers globally, adding AI driven “Nudge,” “Talk to RRM,” and canvas capabilities to automate troubleshooting, reporting, and wireless tuning based on real network data.
- The product embeds tailored AI recommendations directly into IT workflows, which may shift Extreme Networks’ cost profile and stickiness toward higher value, subscription based networking services.
- We will look at how Extreme Networks’ investment narrative is shaped by Agent ONE Coworker’s workflow level “Nudge” recommendations for IT teams.
Scan beyond Extreme Networks and track how agentic AI is reshaping infrastructure by reviewing the hand picked 88 AI infrastructure stocks now.
Extreme Networks Investment Narrative Recap
To own Extreme Networks, you need to believe the business can keep shifting from one-off hardware toward higher value software, cloud, and subscription services, even as growth in core networking hardware is relatively modest. The roll out of Agent ONE Coworker to all Platform ONE subscribers ties that story more tightly to AI driven automation and recurring revenue.
The key near term swing factor is execution on this AI heavy portfolio, including customer adoption across large public sector and enterprise accounts that already drive a big share of sales. Competitive pressure from larger vendors and the risk of lumpy government demand remain central worries, and this launch does not remove those.
The Agent ONE Coworker release is most relevant to the existing catalyst around Extreme Networks’ AI powered Platform ONE and cloud management stack. Making Agent ONE generally available inside current subscriptions reinforces that the firm is leaning into AI driven workflows, where recurring software and services are expected to matter more than one time hardware deals.
Operationally, the new “Nudge,” “Talk to RRM,” and canvas features sit directly on top of that thesis. They tie AI recommendations to real network telemetry, incident response, and reporting, which could influence customer stickiness and subscription mix if IT teams integrate these tools into daily work. The risk is that larger rivals push similar capabilities aggressively, which would keep pricing pressure and execution risk front and center.
Extreme Networks' current analyst script points to revenues of $1.7b and earnings of $60.2 million by 2029, based on a forecast 9.8% yearly revenue growth rate and an increase of about $18.1 million in earnings from $42.1 million today to the 2029 consensus level.
Uncover why Extreme Networks' fair value indicates a 47% potential upside to its current price, which could narrow quickly.
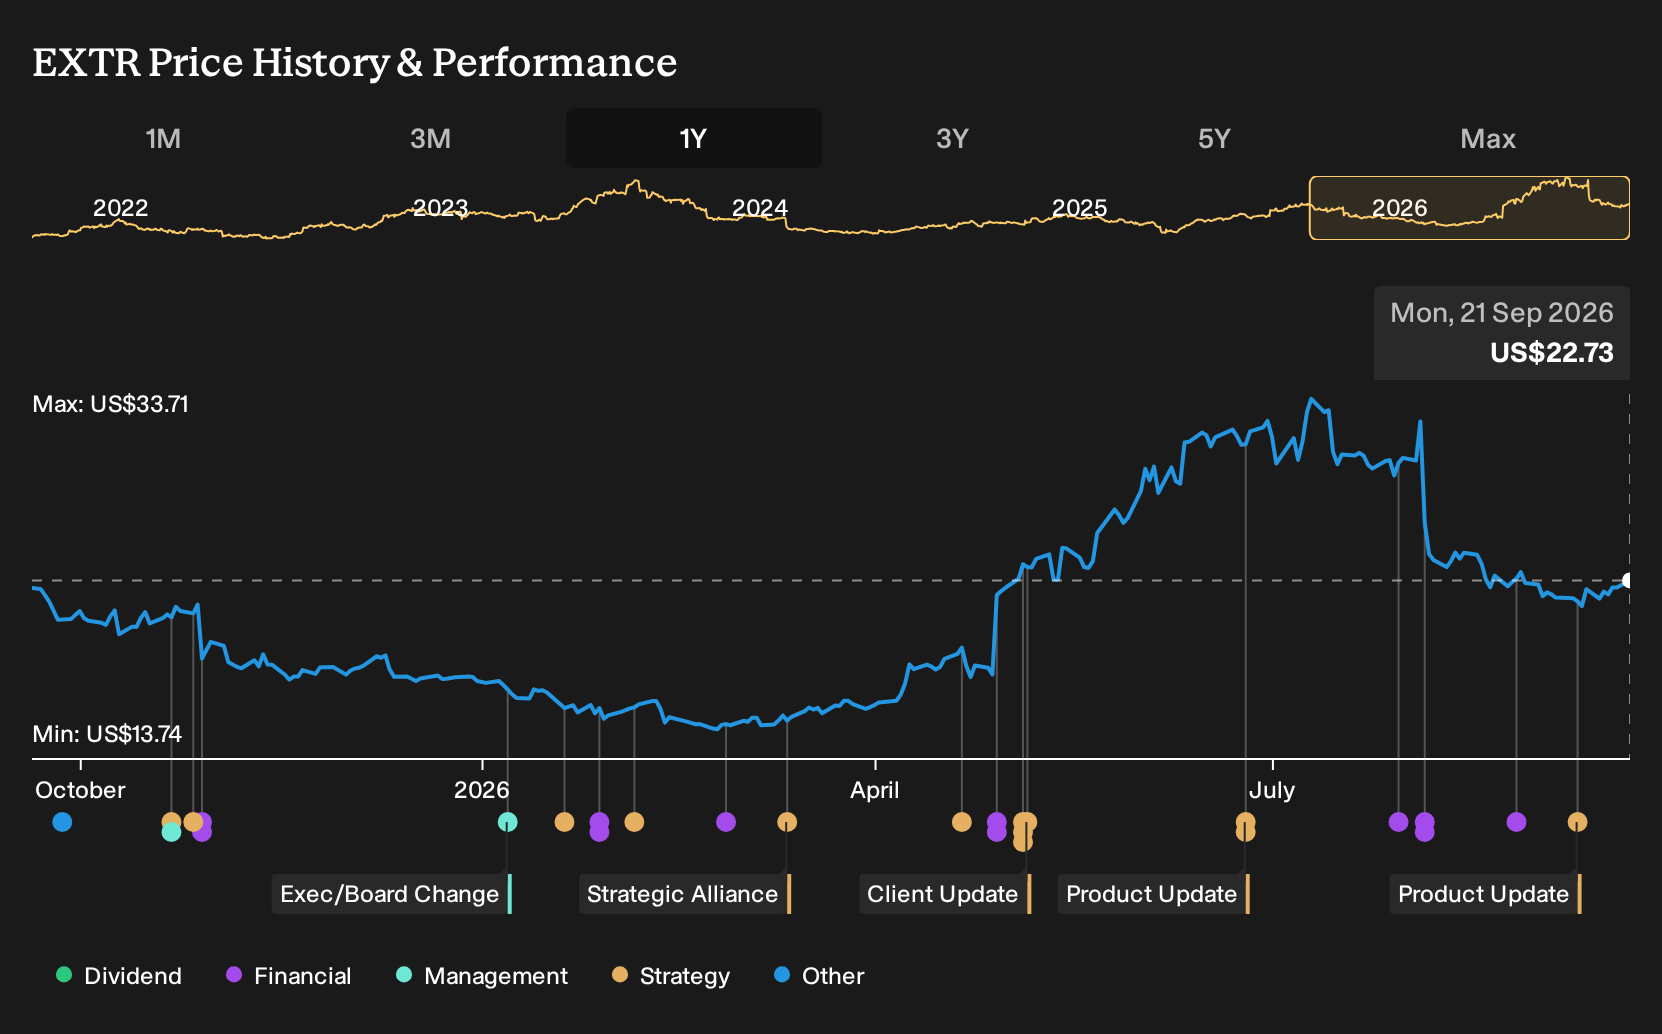
Exploring Other Perspectives
One alternate view around Extreme Networks treats a slowdown in enterprise networking spend as the real swing factor. The lowest analysts were already baking in only 8.8% yearly revenue growth to about US$1.7b and earnings of roughly US$61.2 million by 2029. This new Agent ONE Coworker launch could push those expectations in either direction, so it makes sense to compare several narratives before deciding how you feel about the stock.
Explore 4 other Extreme Networks fair value estimates, including one that suggests as much as 22% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research.
- A great starting point for your Extreme Networks research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Extreme Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extreme Networks' overall financial health at a glance.
Looking for more investment ideas beyond Extreme Networks?
If the Extreme Networks story has you thinking about portfolio upgrades, it can help to scan a wider field of opportunities that match your own risk tolerance and return goals.
- For investors who want potential upside without stretching quality too far, consider a curated set of underpriced, financially solid candidates via the Simply Wall St screener built around 30 high quality undervalued stocks.
- If capital preservation matters just as much as returns for you, filter for sturdier balance sheets and steadier businesses using the screener focused on a 30 resilient stocks with low risk scores.
- Those hunting for mispriced quality away from the crowded trades can scan a tighter, hand picked pool of strong but less followed stocks through a screener highlighting 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com