
Top 3 Japanese Dividend Stocks With Yields Over 3%
With the Federal Reserve lifting interest rates again as inflation stays sticky, income from cash and bonds looks more tempting, yet those payouts can still be eroded by rising prices. Reliable Japanese dividend stocks paying more than 3% offer a different route: you get regular cash flow plus potential capital upside. This article walks through three high-yield candidates from a quality focused screen that prioritises well covered and stable payouts.
The three dividend ideas in this piece are just a sample from the broader screen, which surfaced 546 more companies with 3%+ yields and similarly appealing income stories that are not covered here.
If you want to go beyond this shortlist and quickly identify your own high conviction income plays, head straight to the Dividend Powerhouses (3%+ Yield) screener.
DENSO (TSE:6902)
Overview: DENSO is a Japanese auto parts manufacturer supplying powertrain, thermal management, safety and cockpit systems, plus service parts worldwide.
Operations: DENSO generates revenue mainly in Japan at ¥4.5t, with sizeable contributions from Asia at ¥2.0t and North America at ¥2.1t.
Market Cap: ¥4.8t
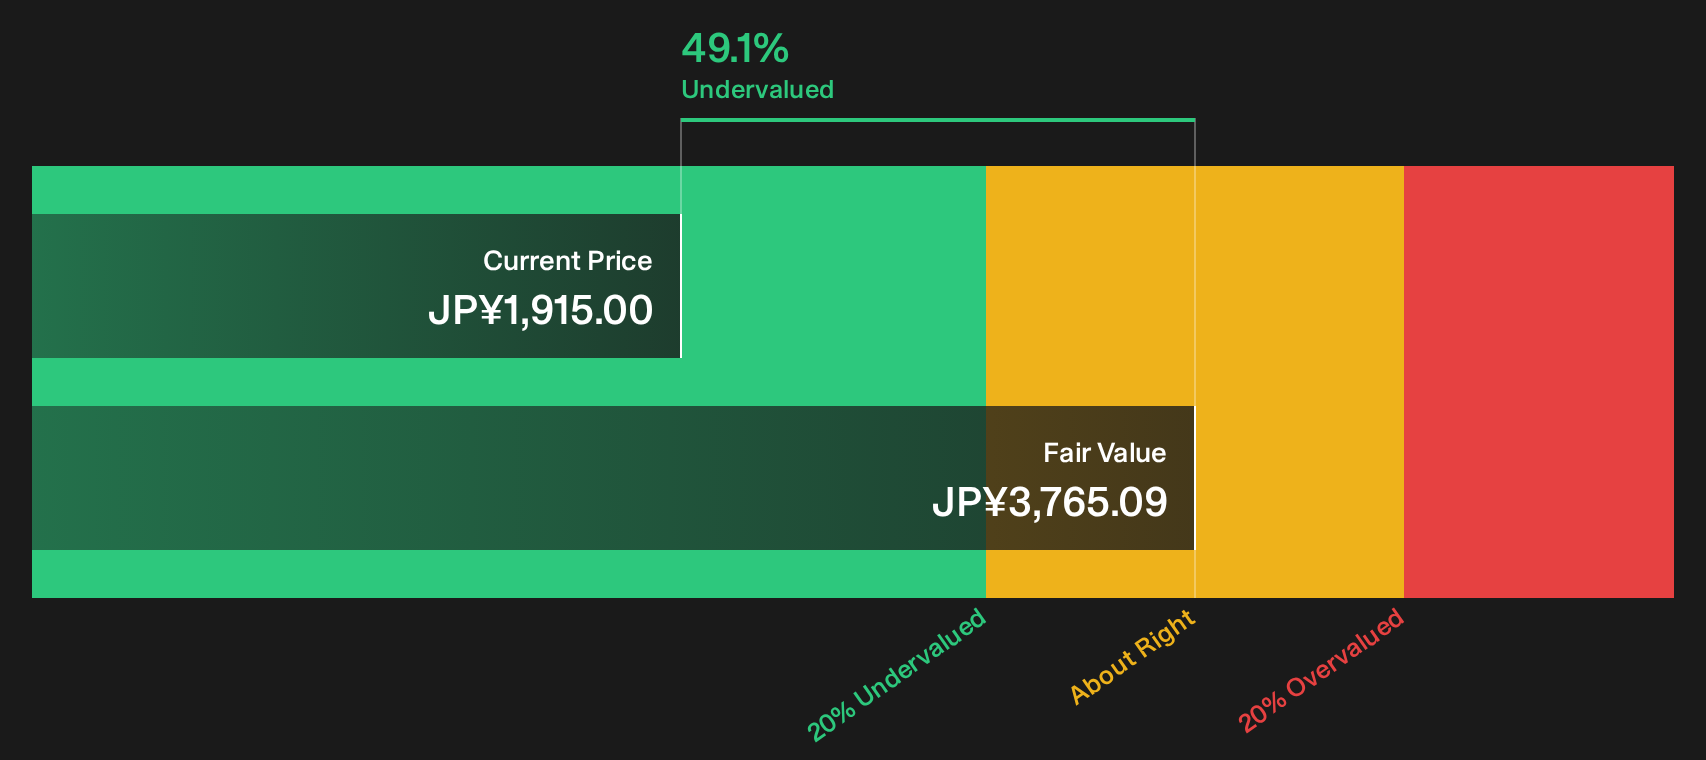
DENSO offers a 3.86% dividend yield backed by a large automotive components business that produces recurring cash flow from powertrain and thermal systems. Earnings have grown at 10.1% per year over 5 years and the shares trade at a large discount to estimated cash flow value. The appeal of that payout now rests on how one pressure on future cash generation resolves.
That depends on how resilient cash generation really is, so unpack the full picture in the 3 key rewards and 1 important warning sign to understand what might be driving the valuation gap.
Astellas Pharma (TSE:4503)
Overview: Astellas Pharma is a global drug maker focused on oncology, urology, ophthalmology and women's health therapies that fund a steady dividend.
Operations: Astellas generates about ¥2.27t in pharmaceutical revenue, led by the USA at roughly ¥1.01t and supported by Japan at ¥328b.
Market Cap: ¥4.27t
Astellas Pharma matters in a dividend screen like this because established cancer, urology and women’s health therapies can turn into repeatable cash flows that keep a 3%+ payout on solid footing.
"Continued strong commercial performance and expanding indications for strategic brands like Xtandi, PADCEV, VYLOY, and IZERVAY, particularly benefiting from increasing access and demand in aging populations and expanding global middle-class markets, are expected to materially boost topline revenue growth."
What really counts now is how one emerging cost and pricing pressure shapes the gap between headline earnings and the cash backing that yield.
That pressure is only one piece of the puzzle, and the full narrative for Astellas Pharma shows how cash generation, pricing power, and pipeline moves could be decoupling from headline earnings expectations.

Japan Tobacco (TSE:2914)
Overview: Japan Tobacco manufactures and sells tobacco products worldwide that generate the cash rich earnings underpinning its high dividend, alongside a smaller processed food operation.
Operations: Japan Tobacco generates about ¥3.6t from Tobacco and ¥162b from Processed Food, mainly across EMA, Asia and Western Europe.
Market Cap: ¥12.2t
Japan Tobacco matters for the Dividend Powerhouses theme because its global cigarette and reduced risk portfolio generates sizeable cash flows that fund a high payout. Recent guidance and dividend increases indicate that management is aligning the income stream with the company’s underlying earnings strength.
"Expansion of harm-reduction products like Ploom AURA and EVO addresses evolving consumer preferences for reduced-risk options, with segment share gains and plans for accelerated international rollout supporting sustained future revenue growth and improved net margins over the medium term."
The key test for income focused holders now is whether one less visible cost and margin pressure allows that higher payout to remain comfortably covered.
If that margin squeeze is what worries you, read the full narrative for Japan Tobacco to see how Japan Tobacco’s payout story could still be quietly accelerating.

Seeking Fresh Alternatives Before They Fly
New income and growth themes can move from quiet to crowded fast. Scan fresh ideas now, before momentum gets caught by the crowd and pricing power starts dropping. Consider acting early based on your own research and objectives.
- Identify early breakouts in small, cash generative AI players by running your filters through the 38 profitable AI stocks that aren't just burning cash while they remain under the radar.
- Search for resilient portfolio anchors with sturdy cash buffers using the curated list of solid balance sheet and fundamentals (21 results) before quality balance sheets become widely recognized.
- Explore opportunities related to potential power infrastructure upgrade cycles by screening the curated 40 power grid technology and infrastructure stocks while valuations still reflect previous assumptions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com