
Gilead Sciences (GILD) HIV Access Push Keeps Valuation Questions Front And Center
Gilead Sciences (GILD) has put its HIV prevention push in the spotlight after expanding royalty free lenacapavir licenses to 120 high incidence countries and signing a fresh access agreement with the Pan American Health Organization.
These HIV access agreements land at a time when Gilead Sciences’ momentum has been building, with a 90 day share price return of 20.4%, a 1 year total shareholder return of 37.15%, a 3 year total shareholder return above 100%, and a 5 year figure above 150%.
Scan how Gilead Sciences’ HIV prevention push compares with other health-focused stocks by zeroing in on curated 37 healthcare AI stocks aligned with long-term medical breakthroughs.
Gilead Sciences’ HIV push and recent share price jump point in the same direction, but are investors re-rating the business or simply chasing momentum as the valuation gap to intrinsic estimates stays wide?
Most Popular Narrative: 17.3% Overvalued
According to the most followed narrative on Gilead Sciences, the fair value sits at $128.38 compared with a last close of $150.56, which leaves a sizeable gap that investors are now weighing against the HIV and oncology pipeline story.
Gilead is transitioning from a “single-franchise HIV company” into a multi-platform biopharma with: High-probability growth drivers (lenacapavir, Trodelvy) and high-upside optionality (cell therapy, immunology). Temporary earnings headwinds may mask the longer-term value creation potential as management leans into M&A, new launches and pipeline build-out.
See why 15 investors see Gilead Sciences as 17% overvalued.
Result: Fair Value of $128.38 (OVERVALUED)
Still, Gilead Sciences faces clear swing factors, including execution risk around recent acquisitions and the possibility that key late stage trials disappoint expectations.
Find out about the key risks to this Gilead Sciences narrative.
Another View: Market Pricing Versus Cash Flow For Gilead Sciences
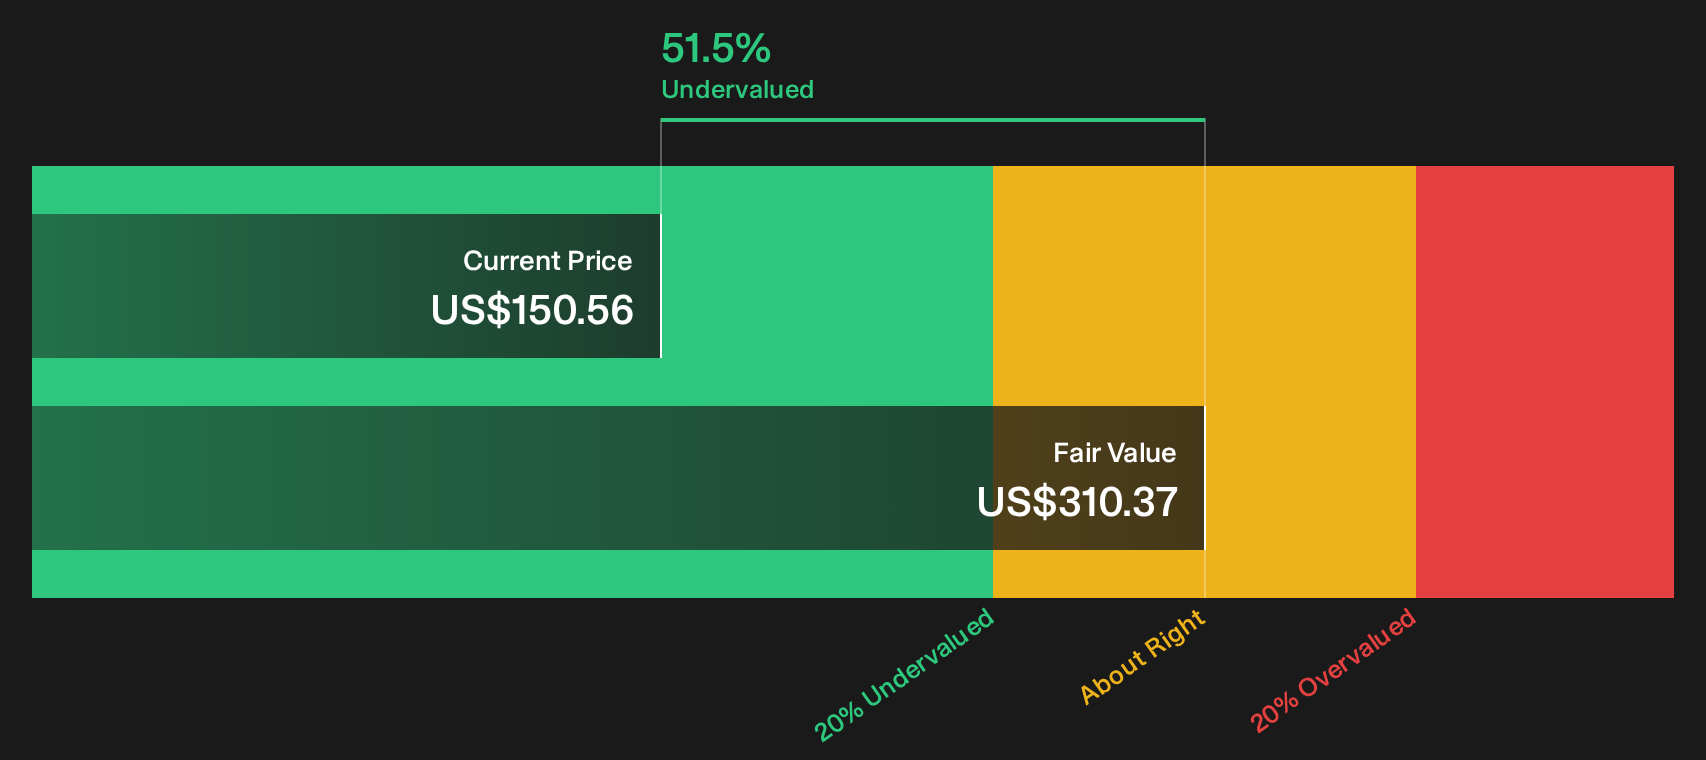
While the leading Gilead Sciences narrative points to a $128.38 fair value and labels the stock overvalued, the SWS DCF model paints a very different picture. On that cash flow view, GILD at $150.56 trades well below an estimated $310.37 value. This flags a wide potential upside gap that investors need to interpret carefully.
Our DCF model uses long term cash flow assumptions, which can influence valuation more than near term earnings metrics. When one framework sees Gilead Sciences as 17.3% overvalued and another sees a large discount, it raises a simple question: which set of expectations do you trust more for your own time horizon?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
With sentiment split on Gilead Sciences, it helps to pressure test both the upside story and the bear case for yourself right now. Weigh the data on 3 key rewards and 2 important warning signs.
Looking for more Gilead Sciences sized investment ideas?
If you stop with Gilead Sciences, you risk missing opportunities where quality, value, and resilience line up even more cleanly across different sectors and themes.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that can help you stress test your portfolio.
- Hunt for potential mispriced quality by running through a focused 30 high quality undervalued stocks that highlights stronger businesses than their current tags suggest.
- Zero in on quieter opportunities by reviewing a 17 high quality undiscovered gems list that surfaces lesser known stocks with solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com