
Paychex (PAYX) Could Be 1% Overvalued As Paycor Deal Shapes Its Value
Paychex (PAYX) has drawn investor attention after recent share price moves, with the stock down about 7.6% over the past month but showing a gain of roughly 17.4% over the past 3 months.
For context, Paychex now trades at US$115.01, with recent share price momentum cooling after a strong run. The 1-year total shareholder return of about 7.9% is lower and contrasts with positive 3-year and 5-year total shareholder returns of 11.4% and 23.5% respectively. This suggests longer term holders have still seen gains even as near term sentiment has softened.
Scan how Paychex compares to other payroll and HR players by checking stocks on our curated list of solid balance sheet and fundamentals (23 results), which may offer similar resilience with different price momentum profiles.
That mix of a recent pullback and longer term gains leaves a simple tension for Paychex investors. Are you seeing the business being re-priced, or just sentiment cooling after a strong run into today’s valuation?
Most Popular Narrative: 1% Overvalued
On Simply Wall St's most followed narrative, Paychex screens as slightly overvalued, with a fair value estimate of $113.71 against the latest close at $115.01 and a 7.58% discount rate behind the calculation.
The acquisition of Paycor is expected to strengthen Paychex's competitive position by expanding its customer base and offering a more comprehensive HCM portfolio, which could drive revenue growth through cross-selling opportunities. Investments in automation and technology are boosting efficiency, resulting in an increased operating margin, with further potential margin improvements anticipated from cost synergies over $80 million from the Paycor acquisition.
See why 52 investors see Paychex as 1% overvalued.
Result: Fair Value of $113.71 (OVERVALUED)
Still, Paychex faces real pressure if Paycor integration stumbles or if higher employee costs and smaller client health plans continue to affect the profitability assumptions built into this narrative.
Find out about the key risks to this Paychex narrative.
Another View On Paychex Valuation
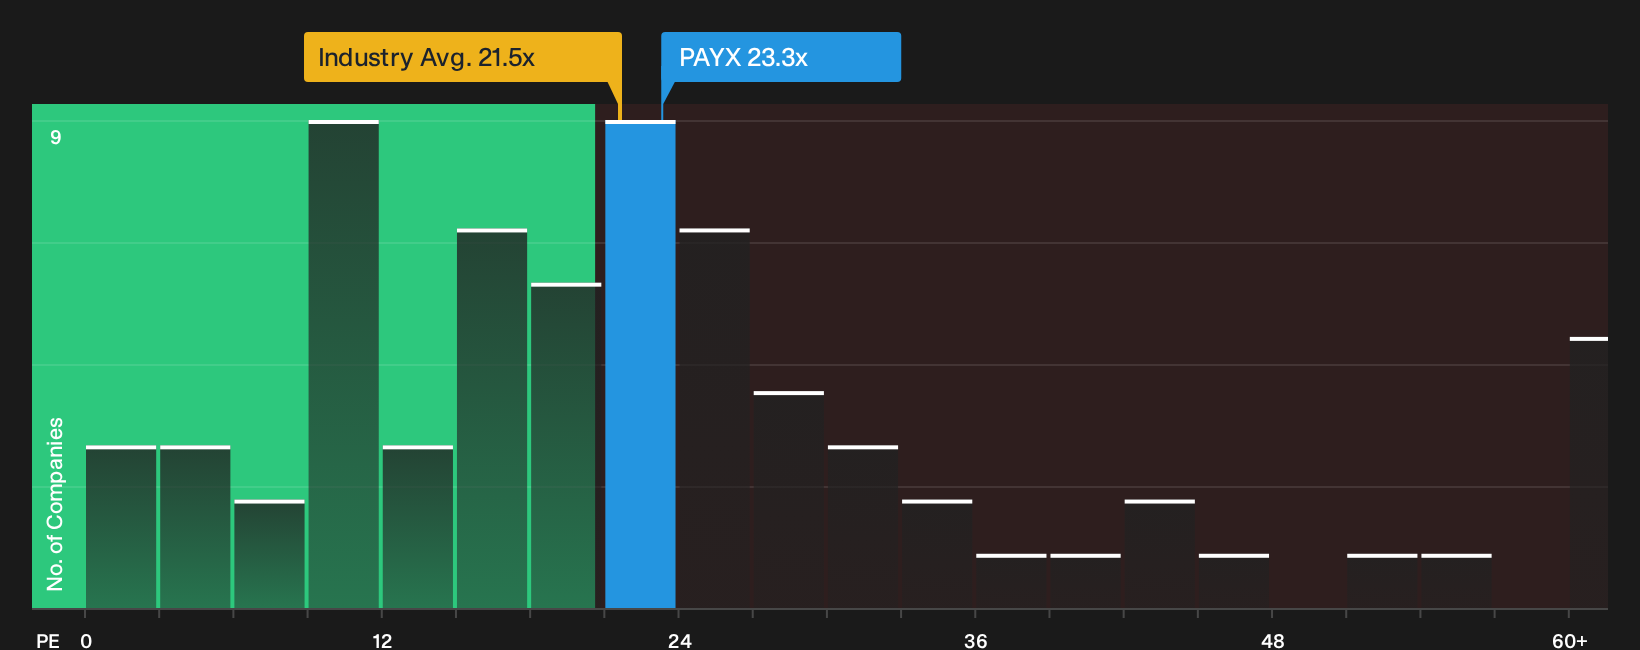
On the multiples side, Paychex looks mixed. The P/E sits at 23.3x, which is higher than both the US Professional Services industry on 21.6x and the peer average at 20.7x, yet it is below the estimated fair ratio of 24.3x. That combination points to some valuation risk if growth disappoints, but also suggests the market could still move closer to that fair ratio if the story plays out as expected.
To see how this price tag lines up with the earnings profile and whether the current multiple leaves enough margin of safety for you, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Paychex can leave the story feeling unsettled. Move quickly, review the underlying data yourself, and shape your own stance by weighing 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Paychex?
Do not stop your research with Paychex. The next opportunity for your portfolio could be sitting in plain sight among other quality businesses and different risk profiles.
- Target potential mispricing by scanning companies our models flag as attractively valued using the 30 high quality undervalued stocks.
- Lock in income potential by reviewing high-yield opportunities screened through the 7 dividend fortresses.
- Strengthen your downside protection by focusing on financially resilient businesses highlighted in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com