
Is QUALCOMM (QCOM) Fully Valued After The Amazon AI Deal And US China Relief?
QUALCOMM (QCOM) has been back in focus after constructive U.S. China talks lifted semiconductor sentiment, and fresh headlines around its expanded collaboration with Amazon on custom AI data center silicon sharpened attention on the stock.
Investors have reacted quickly to this mix of macro relief and QUALCOMM specific AI news, with the share price up 9.29% over the past day and delivering a 20.83% 1 month share price return. This has occurred even though the 90 day share price return is down 4.85% and longer term total shareholder returns of 16.82% over 1 year and 87.42% over 3 years point to momentum that has built over several years rather than just a short burst around the latest headlines.
Pace QUALCOMM’s AI data center story against other potential breakouts by scanning our hand picked 88 AI infrastructure stocks moving with the same macro and hyperscaler tailwinds.The Amazon AI deal and macro relief have already pulled QUALCOMM sharply higher. The real tension now is whether investors just caught the bulk of the move or only the opening act, which is where valuation work starts to matter.
Most Popular Narrative: 94% Overvalued
QUALCOMM last closed at $194.23, while the most followed valuation narrative anchors fair value at $100. The market price currently sits far above that reference point and raises questions about how much of the AI data center story is already reflected in the stock.
The company faces a significant threat from rising geopolitical fragmentation and escalating trade tensions, particularly between the U.S. and China. Ongoing and potential future tariffs, combined with increased efforts by China to reduce dependence on U.S. suppliers, could lead to a substantial decline in Qualcomm's addressable revenue and loss of market share in its largest international market over the next several years, severely constraining long-term revenue growth.
See why 20 investors see QUALCOMM as 94% overvalued.
The narrative uses a $100 fair value anchored on earnings reaching $9.2b by around 2029, profit margins easing from about 21.0% to 19.0%, and a future P/E of roughly 15x, all discounted back using an 11.6% rate. That framework effectively argues that even with $44.1b of current revenue and exposure to AI data center demand, the present share price already assumes stronger profitability and a richer multiple than the more cautious cohort is willing to underwrite.
For investors, the gap between the $194.23 market price and the $100 narrative fair value is really a question about how much earnings resilience QUALCOMM can produce in the face of smartphone headwinds, potential China pressure, and capital needs for new AI infrastructure. The more a reader believes that handset reliance, margin compression in custom silicon, and geopolitical friction will weigh on future cash flows, the closer their own estimate may sit to this discounted view that uses an 11.6% required return.
Result: Fair Value of $100 (OVERVALUED)
Still, a faster ramp in QUALCOMM’s automotive and IoT lines, or stronger traction for its AI data center platforms, could chip away at this bearish narrative.
Find out about the key risks to this QUALCOMM narrative.
Another View: QUALCOMM’s P/E Sends A Different Signal
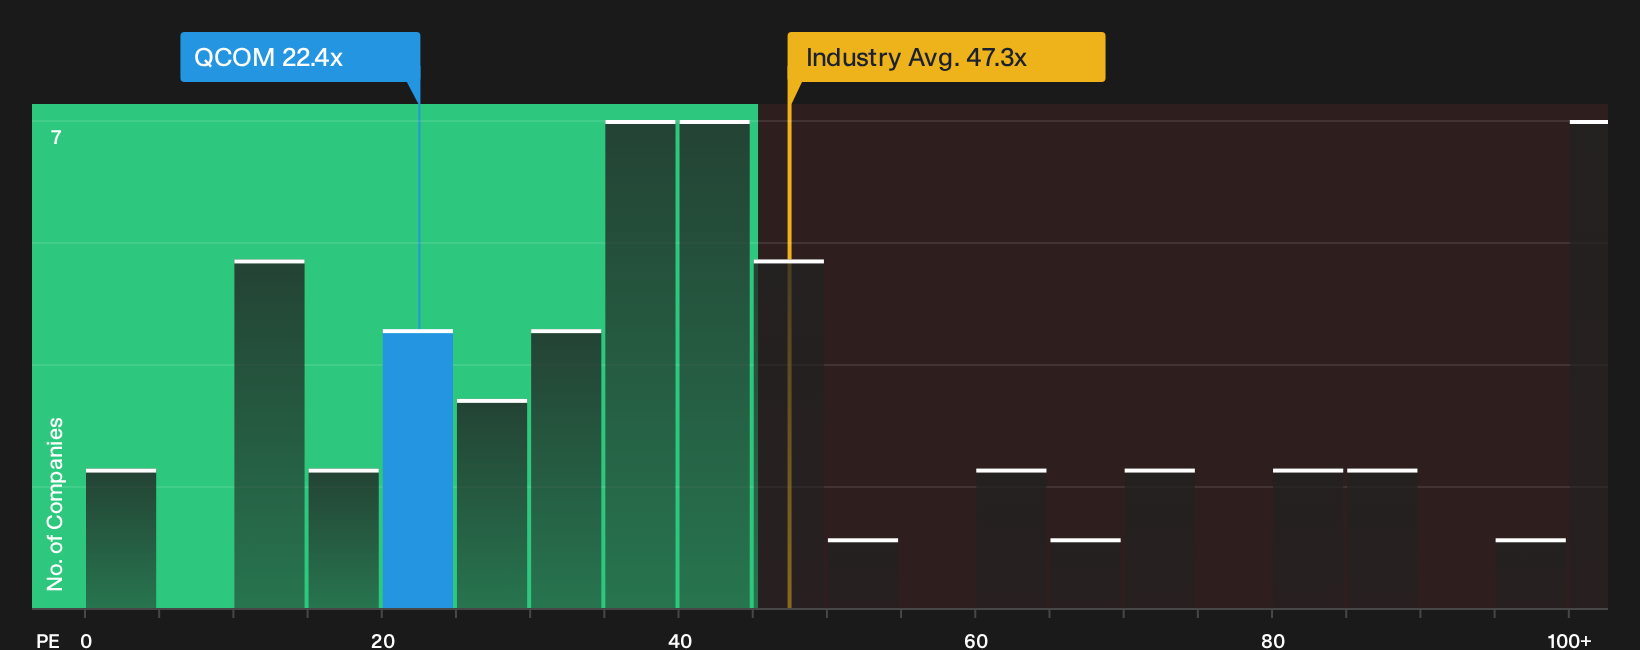
The bearish fair value narrative pegs QUALCOMM at $100, yet the current P/E of 22.4x tells a different story. It sits well below the US Semiconductor sector on 47.3x and the peer group on 47.8x, and under the 29.8x fair ratio that the market could move towards, which lowers valuation risk rather than stretching it.
If the stock is priced above $171.92 on our cash flow work but screens as good value against sector earnings multiples, which lens should carry more weight in your own framework?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around QUALCOMM’s valuation and AI exposure are exactly why the data matters more than the headlines. Move quickly, review both the upside and the red flags, and weigh the 3 key rewards and 1 important warning sign.
Looking for more QUALCOMM-sized investment ideas?
QUALCOMM may be front of mind today, but your next meaningful move could come from a less crowded corner of the market if you scan beyond the usual suspects.
- Target dependable cash flow by zeroing in on established payers through the 7 dividend fortresses that aim to keep income a central part of your portfolio.
- Hunt for value where quality and pricing still align by working through the 30 high quality undervalued stocks that spotlight companies with stronger fundamentals than their tags suggest.
- Protect your downside first by filtering for resilience with the 30 resilient stocks with low risk scores that highlight businesses scoring well on financial strength and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com