
Exploring European Undervalued Small Caps With Insider Buying In September 2026
In September 2026, the European markets experienced volatility as escalating tensions in the Middle East drove energy prices higher, reinforcing inflation concerns and impacting small-cap stocks. Despite these challenges, opportunities may exist for investors seeking to identify promising small-cap companies with insider buying activity, which can sometimes indicate confidence in a company's potential amidst broader market uncertainties.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 39.68% | ★★★★★★ |
| Telecom Plus | 7.9x | 0.3x | 39.07% | ★★★★★☆ |
| Franchise Brands | 27.8x | 2.0x | 46.66% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 16.62% | ★★★★☆☆ |
| Saniona | 7.2x | 3.1x | 32.92% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 31.68% | ★★★★☆☆ |
| Vistry Group | 6.0x | 0.2x | -14.14% | ★★★☆☆☆ |
| Eurocell | 23.1x | 0.3x | 47.35% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.96% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -215.84% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
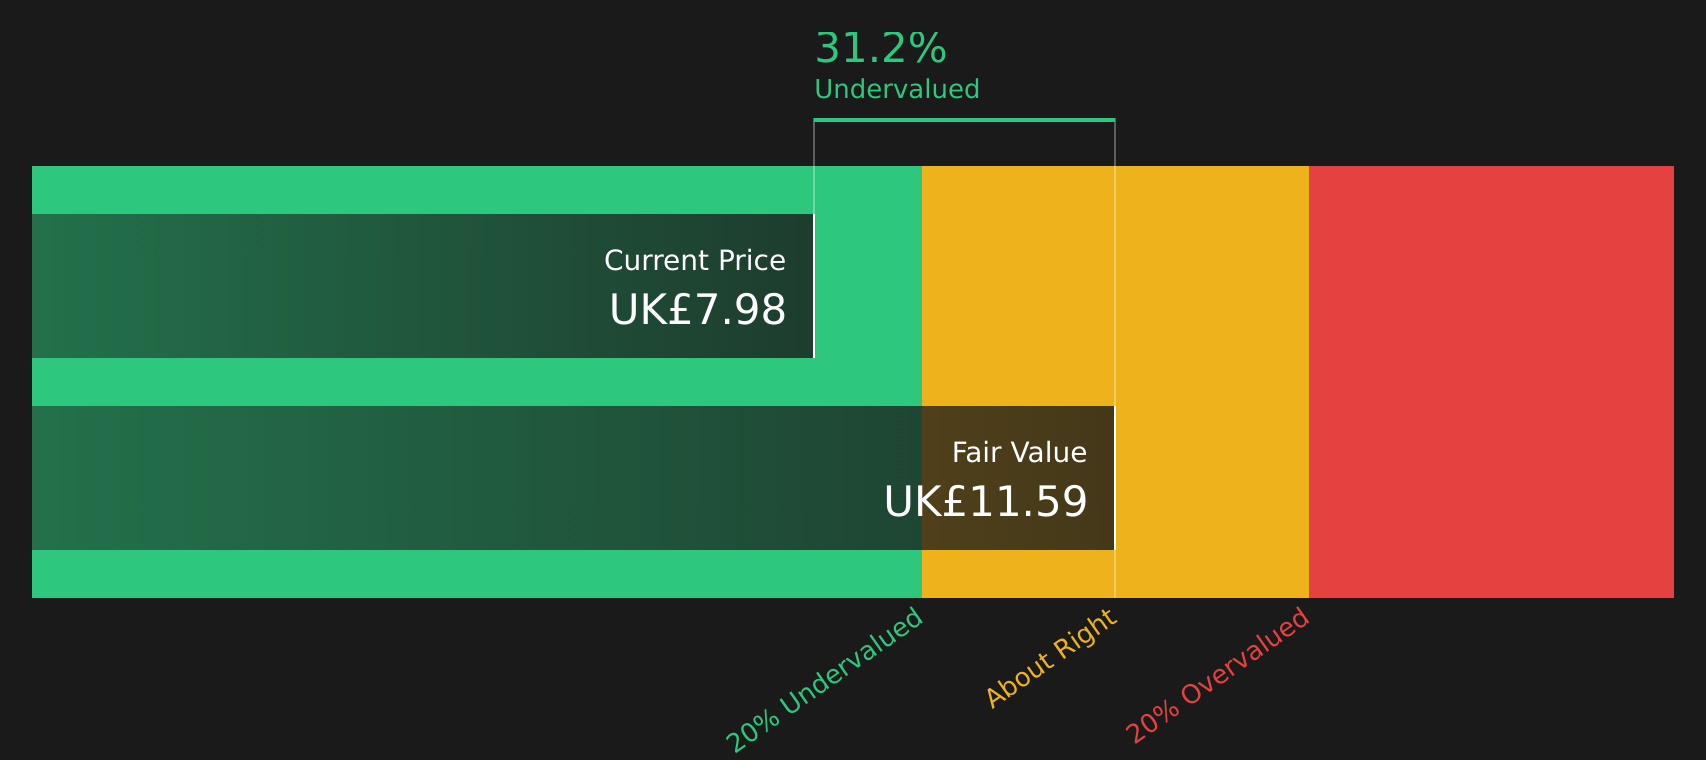
AB Dynamics (AIM:ABDP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: AB Dynamics is a company that specializes in providing simulation, testing products, and testing services for the automotive industry with a market cap of £0.46 billion.
Operations: The company generates revenue primarily from three segments: Simulation, Testing Products, and Testing Services. Recent financial data shows a gross profit margin of 63.79%, with operating expenses being a significant component of the cost structure. The net income margin has fluctuated over time, recently recording -5.02% in February 2026 due to increased operating expenses surpassing revenues.
PE: -36.0x
AB Dynamics, a player in the European market, is navigating its growth path with an expected revenue of £91.6 million for the fiscal year ending August 2026. Insider confidence is evident with recent share purchases by key executives, underscoring belief in its potential despite a volatile share price over the past three months. The appointment of Edward Haycock as Group CFO signals strategic leadership aimed at steering through medium-term growth aspirations amidst reliance on external borrowing for funding.
- Get an in-depth perspective on AB Dynamics' performance by reading our valuation report here.
Understand AB Dynamics' track record by examining our Past report.
Craneware (AIM:CRW)
Simply Wall St Value Rating: ★★★☆☆☆
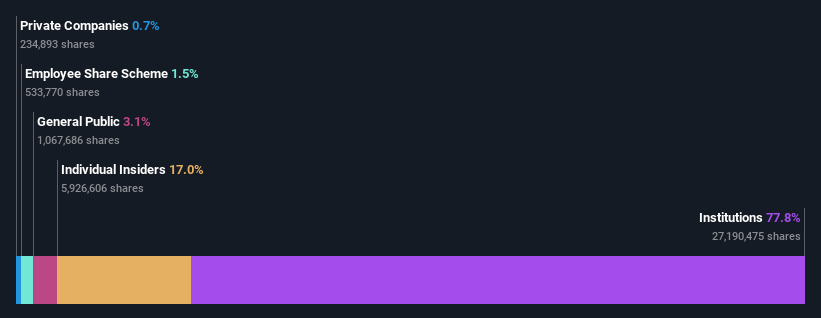
Overview: Craneware is a healthcare software company that specializes in providing revenue integrity and financial performance solutions to healthcare providers, with a market capitalization of approximately £0.63 billion.
Operations: Craneware generates revenue primarily through its operations with a consistent increase in revenue over the periods observed, reaching $211.33 million by December 2025. The company has seen fluctuations in its net income margin, which stood at 10.64% during the same period. Operating expenses have also risen alongside revenue growth, impacting overall profitability.
PE: 20.1x
Craneware, a healthcare software provider, is navigating complexities in medication reimbursement with its new strategic framework, Medication Reimbursement Intelligence. Despite stable revenue of US$205.96 million for FY26 and net income of US$19.73 million, the company expects FY27 to benefit from deferred contracts. Insider confidence is evident as Keith Neilson purchased 9,074 shares in July 2026 for approximately US$100K. This move suggests potential optimism about future growth despite current volatility and external borrowing risks.
- Dive into the specifics of Craneware here with our thorough valuation report.
Gain insights into Craneware's historical performance by reviewing our past performance report.
LSL Property Services (LSE:LSL)
Simply Wall St Value Rating: ★★★★★☆
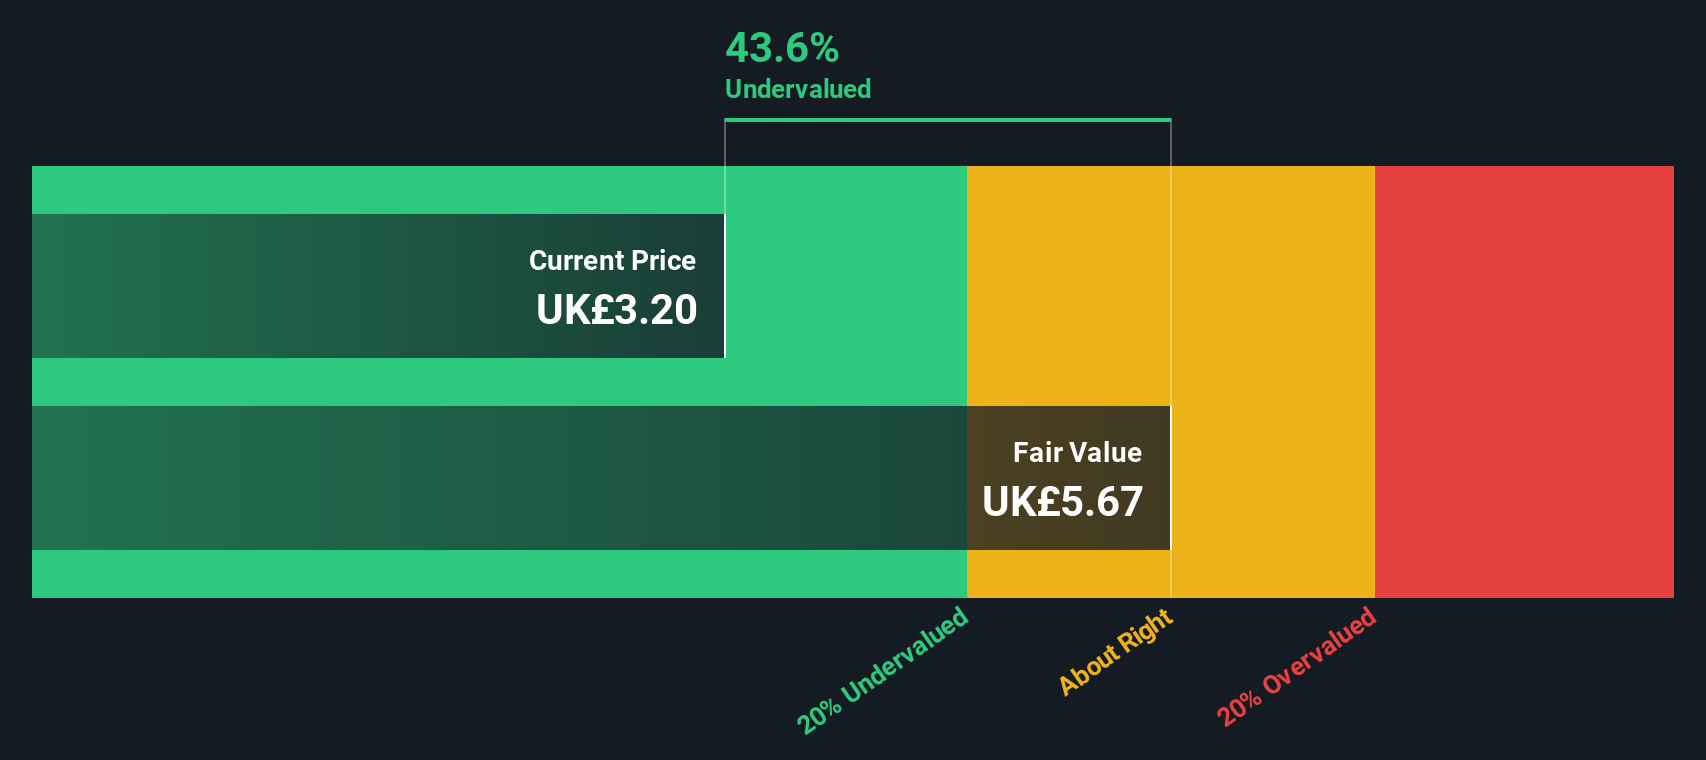
Overview: LSL Property Services operates in the UK, providing financial services, surveying and valuation, and estate agency services with a market cap of £0.28 billion.
Operations: The company generates revenue primarily from Surveying and Valuation (£110.70 million), Financial Services (£48.19 million), and Estate Agency (£26.70 million). Operating expenses are significant, with General & Administrative Expenses being a major component, reaching £116.53 million by the latest period available. The net income margin has shown variability, peaking at 18.95% in late 2021 before turning negative in late 2022 but recovering to positive figures by early 2024, indicating fluctuations in profitability over time.
PE: 14.9x
LSL Property Services, a small company in the European market, recently reported increased half-year sales of £92.31 million and net income of £8.61 million. The firm declared an interim dividend of 4 pence per share, maintaining shareholder returns. Insider confidence is evident as their CFO purchased 46,205 shares worth nearly £99,479 in recent months. Despite relying entirely on external funding sources, LSL's earnings are projected to grow by over 11% annually, suggesting potential for future value appreciation.
- Delve into the full analysis valuation report here for a deeper understanding of LSL Property Services.
Explore historical data to track LSL Property Services' performance over time in our Past section.
Summing It All Up
- Investigate our full lineup of 39 Undervalued European Small Caps With Insider Buying right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com