
Top 3 Japanese Undervalued Stocks To Watch In September 2026
Long term US interest rates have risen sharply as bond investors demand higher compensation for locking in yields. That shift puts pressure on richly priced assets and rewards solid cash generators. For Japanese stocks with strong cash flow potential yet discounted share prices, this creates a window where pessimism can misprice steady businesses. This article highlights 3 such Japan cash flow stocks that screen as undervalued on a discounted cash flow basis.
The three featured stocks below are only a sample, and the full discounted cash flow screen surfaced 36 more companies with similar cash generation potential that are not covered here. To identify and analyze the highest conviction ideas built around strong cash flows and valuation gaps, go straight to the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Canon is a global manufacturer of printers, cameras, medical scanners, and industrial equipment. The printing division’s recurring consumables and service contracts closely align it with the cash-flow focus of this screener. The group has an equity value of about ¥3.8t, placing it firmly in large cap territory.
Recurring cash generation from Canon’s office and production printers supports the DCF-based view that the stock trades below its cash-flow potential. Investors who care about dependable free cash flow may find the valuation interesting. However, that appeal ultimately rests on how one unseen pressure shapes printing demand and pricing power.
To see how that pressure feeds into assumptions on renewal rates, pricing and cash conversion, review the DCF valuation analysis for Canon and decide whether Canon’s cash engine is being underestimated.
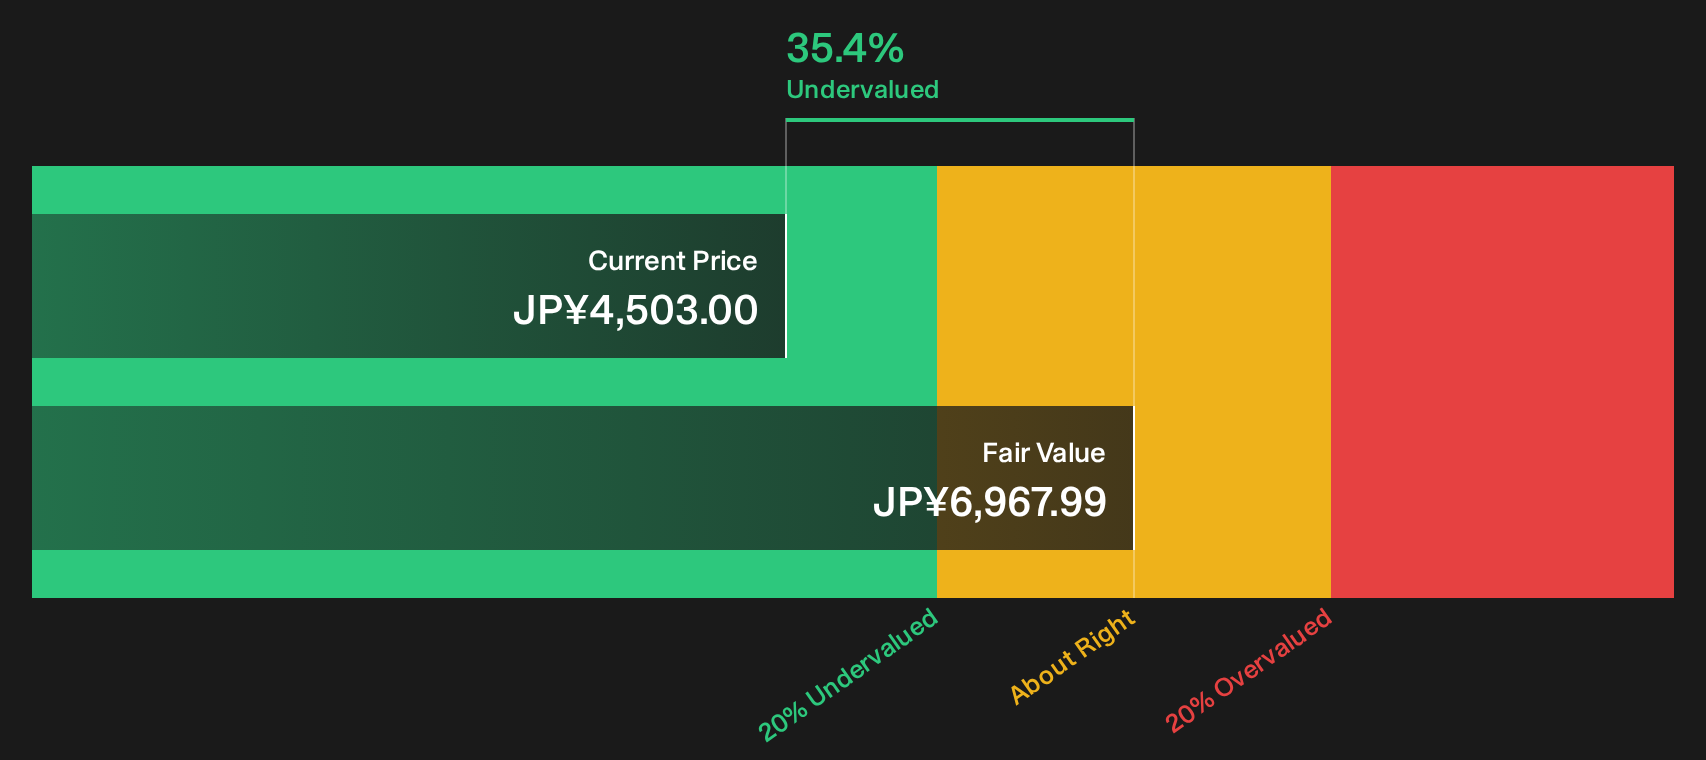
Astellas Pharma (TSE:4503)
Astellas Pharma is a global drug maker focused on oncology and specialty treatments that can generate steady cash flows from marketed therapies, which fits the cash flow undervaluation theme. It generated about ¥2,274.4b from pharmaceuticals and has a market value near ¥4,273.6b.
"Patent expirations for key drugs such as XTANDI and mirabegron threaten to create substantial revenue and earnings losses as generic entrants erode Astellas' market share in critical therapeutic areas over the next several years."
For Astellas Pharma, a key consideration is whether its newer specialty franchises can reshape margins before a shift in pricing power occurs.
Whether that shift happens smoothly or stalls abruptly, the full narrative for Astellas Pharma describes how Astellas Pharma could convert today’s pressure into an accelerating cash engine.

Terumo (TSE:4543)
Terumo is a global medical device group whose cash-flow-rich consumables, such as syringes and vascular tools, link neatly to this cash flow undervaluation screen. The Cardiac and Vascular segment brings in about ¥706.7 billion, Medical Care Solutions adds roughly ¥222.3 billion, and Blood and Cell Technologies contributes around ¥240.2 billion, supporting a roughly ¥3.3 trillion market cap.
Terumo’s recurring consumables story is not just about steady orders in hospitals. It also ties directly into how the group is trying to deepen its foothold in faster growing markets.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects in this key emerging market."
What really matters next is how one unresolved pressure on pricing power shapes Terumo’s ability to keep those cash-heavy consumables earning their keep.
That pressure on pricing power is exactly where the story gets interesting, and the full narrative for Terumo shows how Terumo’s consumables engine could continue to gain momentum beyond China.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast. Breakout trends, new momentum, and under the radar stories often get caught once prices are already flying. Scan curated ideas while it matters and aim to get in before moves become widely recognized.
- Spot potential income workhorses before yields get crowded by running through the 14 dividend fortresses that screens for high payouts backed by sturdy balance sheets.
- Track where real AI momentum could be building, not just hype, by scanning the 38 profitable AI stocks that aren't just burning cash filtered for businesses already turning artificial intelligence into earnings.
- Find potential growth alternatives in companies quietly reinforcing the electricity backbone by reviewing the 40 power grid technology and infrastructure stocks focused on grid hardware, software, and infrastructure specialists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com