
UK Growth Companies With High Insider Ownership For September 2026
As the United Kingdom's FTSE 100 index experiences turbulence due to weak trade data from China, investors are closely monitoring the market for opportunities that can withstand global economic pressures. In such a climate, growth companies with high insider ownership may offer potential resilience and alignment of interests between management and shareholders, making them an intriguing focus for those navigating the current financial landscape.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| RentGuarantor Holdings (AIM:RGG) | 39.7% | 87.7% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Metals Exploration (AIM:MTL) | 15.9% | 86.7% |
| Hochschild Mining (LSE:HOC) | 38.3% | 22.2% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| Energean (LSE:ENOG) | 19.3% | 32.7% |
| EARNZ (AIM:EARN) | 19.5% | 76.5% |
| Crimson Tide (AIM:TIDE) | 32.5% | 119.1% |
| ActiveOps (AIM:AOM) | 22.2% | 81% |
Let's dive into some prime choices out of the screener.
Optima Health (AIM:OPT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Optima Health plc offers occupational health and wellbeing services to both public and private sectors in the UK and Ireland, with a market cap of £267.59 million.
Operations: The company generates £120.64 million in revenue from its occupational health and wellbeing services across the UK and Ireland.
Insider Ownership: 27.9%
Earnings Growth Forecast: 68.8% p.a.
Optima Health shows strong growth potential with forecasted earnings growth of 68.8% annually, outpacing the UK market's 11.1%. Despite a low return on equity forecast and recent shareholder dilution, its revenue is projected to grow at 19% per year, significantly above the UK market average. The company is actively seeking M&A opportunities to enhance scale and efficiency. Currently trading at a substantial discount to estimated fair value, Optima remains an intriguing prospect for growth-focused investors.
- Click to explore a detailed breakdown of our findings in Optima Health's earnings growth report.
- In light of our recent valuation report, it seems possible that Optima Health is trading behind its estimated value.

Greencore Group (LSE:GNC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Greencore Group plc, with a market cap of £1.94 billion, manufactures and sells convenience food products in the United Kingdom and Ireland through its subsidiaries.
Operations: The company's revenue segment consists of £2.34 billion from its Convenience Foods operations in the UK and Ireland.
Insider Ownership: 21.4%
Earnings Growth Forecast: 48.2% p.a.
Greencore Group exhibits promising growth prospects with earnings forecasted to grow significantly at 48.18% annually, outpacing the UK market's 11.1%. Despite a low return on equity forecast and recent shareholder dilution, its revenue is expected to grow faster than the market at 14.3% per year. Trading well below estimated fair value and with substantial insider buying recently, Greencore presents an intriguing opportunity for investors focused on growth companies with high insider ownership.
- Dive into the specifics of Greencore Group here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Greencore Group is priced lower than what may be justified by its financials.
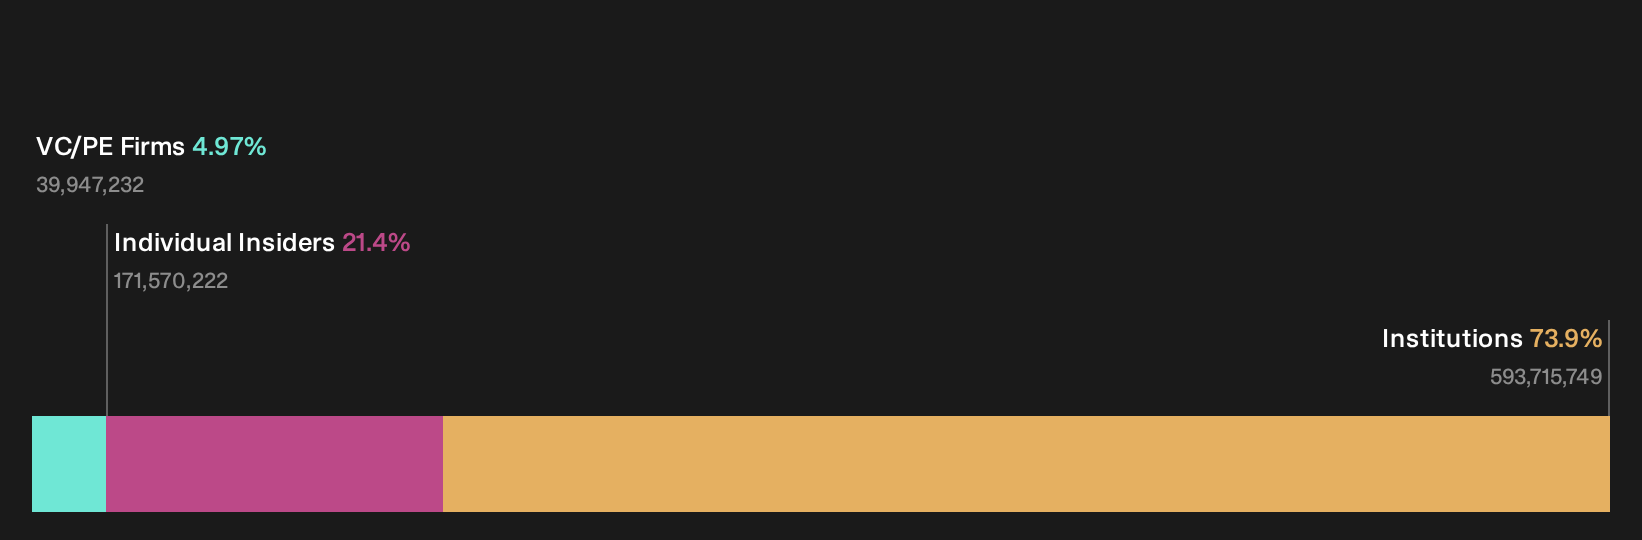
International Workplace Group (LSE:IWG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: International Workplace Group plc, along with its subsidiaries, offers workspace solutions across the Americas, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of approximately £1.65 billion.
Operations: The company generates revenue from its workspace solutions through two primary segments: Company-Owned at $3.31 billion and Managed & Franchised at $151 million.
Insider Ownership: 27.1%
Earnings Growth Forecast: 42% p.a.
International Workplace Group is trading significantly below its estimated fair value, with analysts predicting a 55% stock price increase. Despite slower revenue growth forecasts compared to the UK market, earnings are expected to grow rapidly at 42% annually. However, financial concerns arise as interest payments aren't well covered by earnings and profit margins have declined. Recent buybacks totaling $100 million reflect confidence in the company's prospects, alongside a modest dividend increase demonstrating shareholder commitment.
- Click here to discover the nuances of International Workplace Group with our detailed analytical future growth report.
- Our valuation report here indicates International Workplace Group may be undervalued.
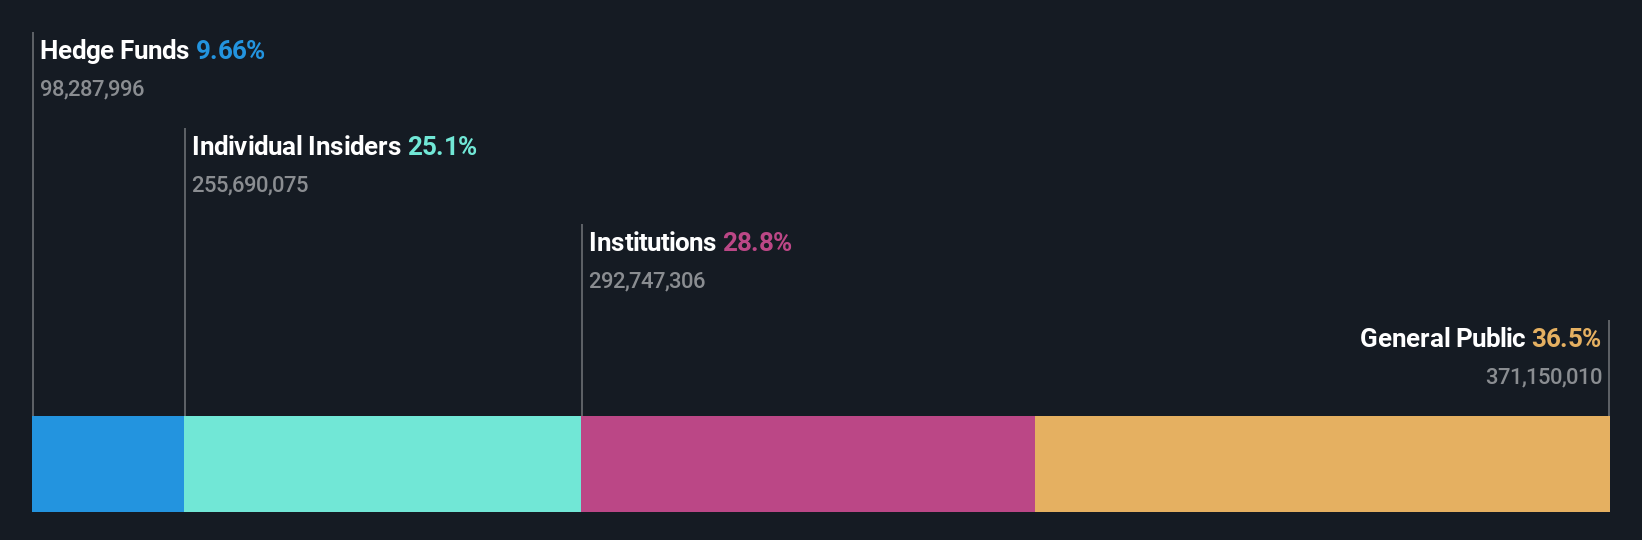
Key Takeaways
- Gain an insight into the universe of 58 Fast Growing UK Companies With High Insider Ownership by clicking here.
- Seeking Other Investments? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com