
South African Steel Tariffs Put PPC Stock And Construction Margins In Focus
South Africa’s sweeping steel tariff hikes have just changed the ground rules for construction and infrastructure contractors. Input costs, pricing power and project margins are all being reshuffled, and that creates a window where some Johannesburg-listed stocks tied to this story could surprise investors while others face tighter squeezes. This article unpacks the tariff shock and reveals 3 stocks from the Construction & Infrastructure Contractors screener that look most exposed to the news.
The stocks highlighted below are only a first cut from this tariff story, while the full Construction & Infrastructure Contractors screen surfaces 9 more Johannesburg-listed companies with equally compelling steel exposure angles that are not covered here. To identify and analyze the highest conviction ways to play this theme, head straight into the South African Construction & Infrastructure Contractors screener.
PPC (JSE:PPC)
PPC is a cement heavyweight in the South African construction ecosystem, so any shift in project activity or input costs tends to have a direct impact on its cement, aggregates and readymix volumes.
PPC generates about ZAR6.3b from South Africa and Botswana cement, ZAR3.6b from Zimbabwe cement and around ZAR900m from its South African materials arm, with a market cap of roughly ZAR12b.
"PPC's strategic turnaround plan includes optimizing current assets and implementing energy efficiency upgrades, which could reduce operational costs and improve EBITDA margins and earnings."
What matters from here is how one quieter shift in its competitive backdrop affects pricing power and future profitability.
If that pricing shift is what you are watching, the full narrative for PPC shows how PPC’s turnaround, tariffs and capacity moves could be quietly reshaping the risk reward gap.

Raubex Group (JSE:RBX)
Raubex Group is an infrastructure and construction materials group tightly linked to South Africa’s construction and civil engineering cycle, supplying roads, earthworks and other projects that rely on steel intensive inputs. It generates about ZAR7.2b from Roads and Earthworks, ZAR4.5b from Construction Materials, ZAR4.5b from Materials Handling and Mining, ZAR4.6b from Infrastructure and has a roughly ZAR7.5b market cap.
Raubex Group ties directly into the screener theme through heavy exposure to roads, earthworks and infrastructure work that depends on steel rich products whose pricing is being reset by tariffs. The mix of construction services and materials gives it several ways to reflect higher input costs in tenders. However, funding risk, margins and dividend cover still hinge on how one unseen pressure on project pricing evolves.
That hidden pressure point is exactly what makes the 3 key rewards and 1 important warning sign so useful for weighing how Raubex Group could absorb shocks or accelerate from here.

Wilson Bayly Holmes-Ovcon (JSE:WBO)
Wilson Bayly Holmes-Ovcon is a Johannesburg based contractor focused on large building and civil engineering work, a direct fit with the Construction & Infrastructure Contractors theme. It earns about ZAR12.1b from building and civil projects, ZAR9.1b from roads and earthworks, ZAR1.5b from construction materials and ZAR5.9b from the UK, with a market value near ZAR7.4b.
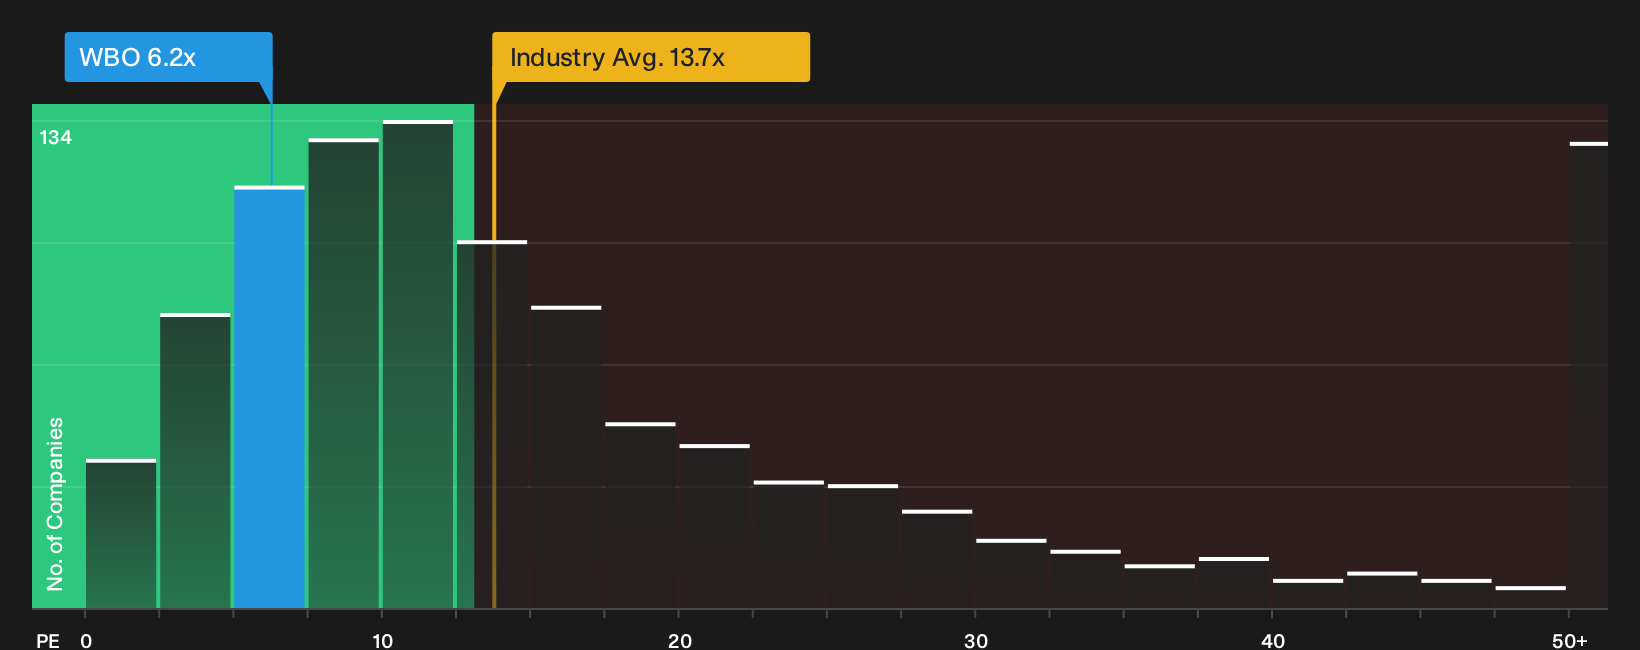
Wilson Bayly Holmes-Ovcon provides exposure to large construction and infrastructure projects at a P/E of 6.2x, supported by its earnings and a ZAR28.3b revenue base that is concentrated in South African work. Steel tariffs are an important factor, and so is the impact when a key contract term is affected by input inflation.
When that contract term moves, the analysis report for Wilson Bayly Holmes-Ovcon shows how Wilson Bayly Holmes-Ovcon’s P/E, order book mix and tariff exposure could be quietly decoupling from headline sentiment.
Seeking Alternatives Beyond Steel Tariffs
Fresh ideas move first. Stocks gaining quiet momentum often fly before the crowd even looks. Scan new themes while they are still under the radar and act now.
- Spot cash generative businesses before they hit headlines by scanning the curated list of solid balance sheet and fundamentals (198 results) and filter for sturdier balance sheets while it still really matters.
- Ride structural shifts in digital finance by tracking under the radar leaders through the curated 19 cryptocurrency and blockchain stocks and position before momentum traders turn up.
- Target potential income workhorses with resilient payouts by scanning the hand picked 162 dividend fortresses so you are not chasing yields after prices have already moved.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com