
Hemlo Mining (TSX:HMMC) Slides On Power Outage As Valuation Questions Grow
Hemlo Mining (TSX:HMMC) has been in focus after reporting a temporary electrical outage at an underground substation at the Hemlo Gold Mine on September 4, 2026. The incident affected part of its Alimak production area.
That outage coincided with a sharp pullback in Hemlo Mining’s recent trading, with the share price down 6.31% over the past day and 17.61% over the past week, following a 36.60% year-to-date share price return and a very large 1-year total shareholder return that points to strong momentum over the longer period.
Scan how Hemlo Mining stacks up against other producers under fresh operational headlines by comparing it to our hand picked 36 elite gold producer stocks in similar situations.
After a sharp pullback, Hemlo Mining now trades well below both its analyst target and intrinsic estimate range. Is that discount a fair reflection of risk, or has the price slipped too far from fair value?
Price-to-Earnings of 88.6x: Is it justified?
Hemlo Mining now trades at CA$6.83 per share, while screening as expensive on earnings with a P/E of 88.6x compared with both peers and the wider Canadian metals and mining group.
The P/E ratio compares the current share price with the last 12 months of earnings per share, so a higher figure usually reflects strong profit expectations or temporarily low earnings. For a gold producer like Hemlo Mining that only recently moved into profitability and carries a large one off loss of $15.1m in its latest 12 month period to 30 June 2026, that single snapshot can be skewed by unusual items.
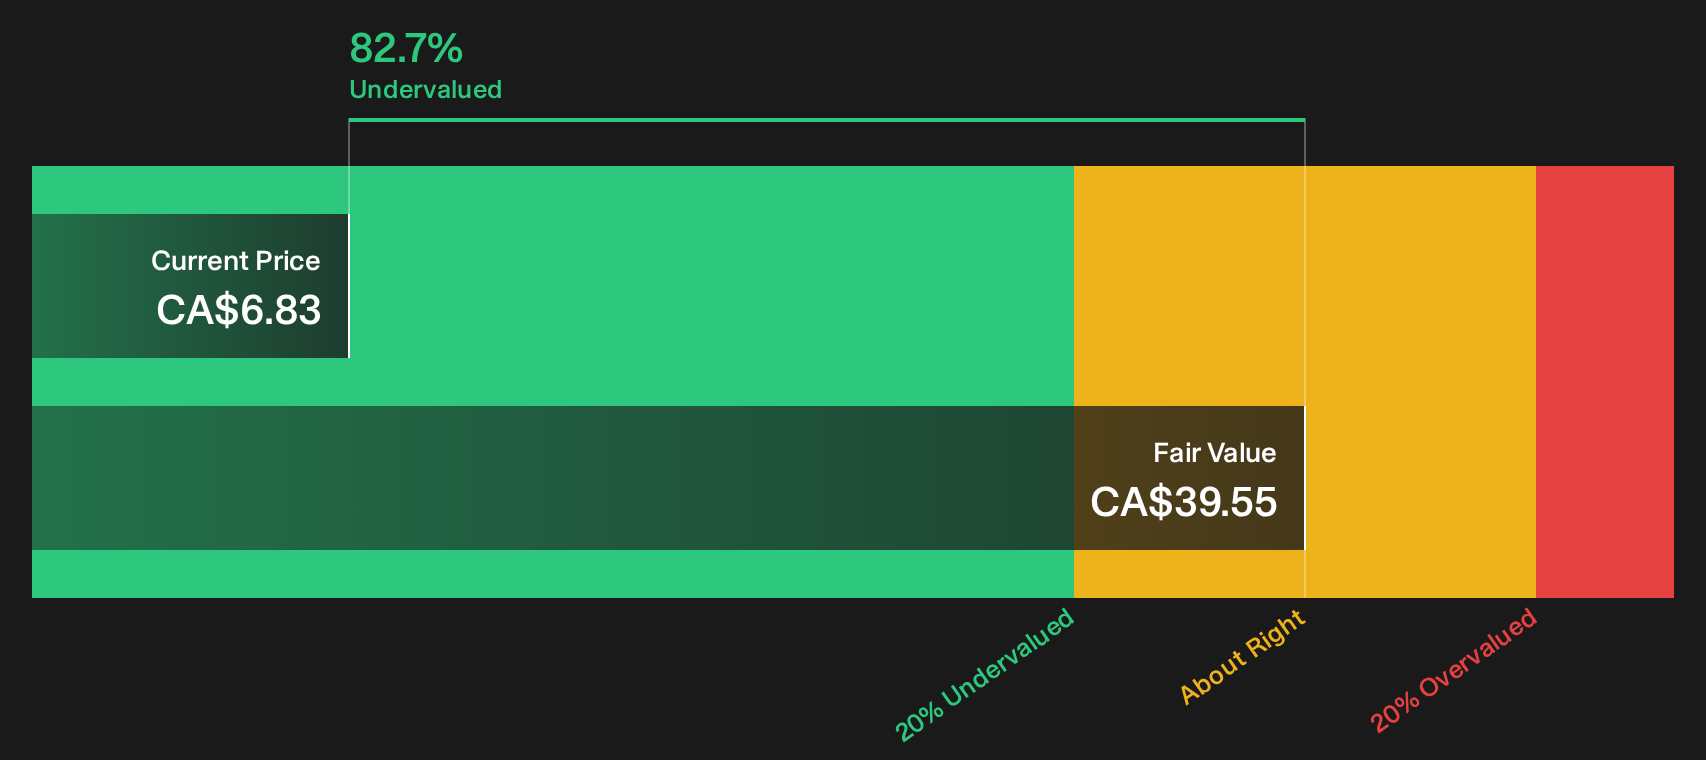
Analysts are forecasting annual earnings growth of 40.8% and revenue expansion of 23.7%, and the SWS DCF model currently estimates fair value at CA$39.55, which is well above the current CA$6.83 price. Against that backdrop, the P/E of 88.6x screens very elevated versus the Canadian metals and mining industry average of 17x, the peer group average of 24.9x and the estimated fair P/E of 26.1x that the market could move toward over time if cash flows and profitability normalise.
Explore the SWS fair ratio for Hemlo Mining.
Result: Price-to-Earnings of 88.6x (OVERVALUED)
Still, a single-mine profile at Hemlo Mining and the recent electrical disruption at the Hemlo gold operation could both pressure sentiment if setbacks persist.
Find out about the key risks to this Hemlo Mining narrative.
Another view on Hemlo Mining’s value
The P/E of 88.6x makes Hemlo Mining look expensive on recent profits. The SWS DCF model tells a very different story. It suggests fair value of CA$39.55 per share versus the current CA$6.83 price, which screens as heavily undervalued. So which signal deserves more weight?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hemlo Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Hemlo Mining is split, with clear worries sitting beside clear positives, so move quickly, review the underlying data, and weigh both sides. To see the key issues and upsides investors are focused on in one place, take a look at the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hemlo Mining?
You have seen how sharply sentiment can swing around one operation. Give yourself more options by screening for other opportunities with stronger balance sheets, income profiles, or upside potential.
- Pinpoint undervalued opportunities that pair quality fundamentals with cheaper pricing by scanning the 6 high quality undervalued stocks before they move out of reach.
- Lock in potential income streams by reviewing the 1 dividend fortresses that focus on higher yielding companies with more robust payout records.
- Tilt your watchlist toward resilience by checking the 8 resilient stocks with low risk scores that score stronger on stability and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com