
Is Kureha (TSE:4023) Fully Valued On Its Revenue And Loss Profile?
Kureha (TSE:4023) has drawn investor attention after posting annual revenue of ¥167,246 and a net loss of ¥8,465, prompting fresh questions about how the materials group’s mixed financial profile compares with its recent share performance.
The share price tells a mixed story. Kureha has slipped over the past month with a 30 day share price return of a 6.62% decline, and short term moves have been weak. However, the 90 day share price return of 8.33% and 3 year total shareholder return of 64.50% show momentum that long term holders may consider more important than the recent pullback.
Compare Kureha's mixed share performance with other materials and industrials players by scanning our hand-picked list of solid balance sheet and fundamentals (21 results) that have weathered recent swings with sturdier finances.
That combination of a recent pullback, a longer run-up and a current loss on ¥167,246 in revenue raises a practical question: Is Kureha worth paying up for now, or does patience make more sense at this price?
Preferred price-to-sales of 1x for Kureha: Is it justified?
On a simple sales based lens, Kureha looks expensive at its current valuation, with a P/S of 1x at a ¥4,160 share price compared with cheaper readings across both the JP Chemicals industry and the company’s own estimated fair ratio.
The P/S ratio tells you how much investors are willing to pay for each ¥1 of revenue. For a materials and chemicals group like Kureha, this is a useful check because earnings can swing with input costs and cycles, while revenue tends to be more stable. A higher P/S suggests the market is baking in stronger profitability or growth in the future, while a lower one implies more muted expectations.
Here the market is paying 1x sales for Kureha, which is higher than the JP Chemicals industry average of 0.7x and also above the estimated fair P/S of 0.8x. That premium signals investors are assigning a richer tag than both sector peers and the level the fair ratio analysis suggests the valuation could move towards if sentiment cools or expectations reset.
Explore the SWS fair ratio for Kureha.
Result: Price-to-sales of 1x (OVERVALUED)
Still, Kureha is running a net loss of ¥8,465 and trades at a P/S above both the JP Chemicals average and its own fair ratio estimate. As a result, any reversal in sentiment or pressure on revenues could quickly test that premium.
Find out about the key risks to this Kureha narrative.
Another view on Kureha’s value
The earlier P/S check painted Kureha as expensive, and the SWS DCF model points in the same direction. At a share price of ¥4,160, the stock trades above an estimated future cash flow value of ¥2,582.5. That gap suggests limited room for error if the cash generation story softens.
Look into how the SWS DCF model arrives at its fair value.
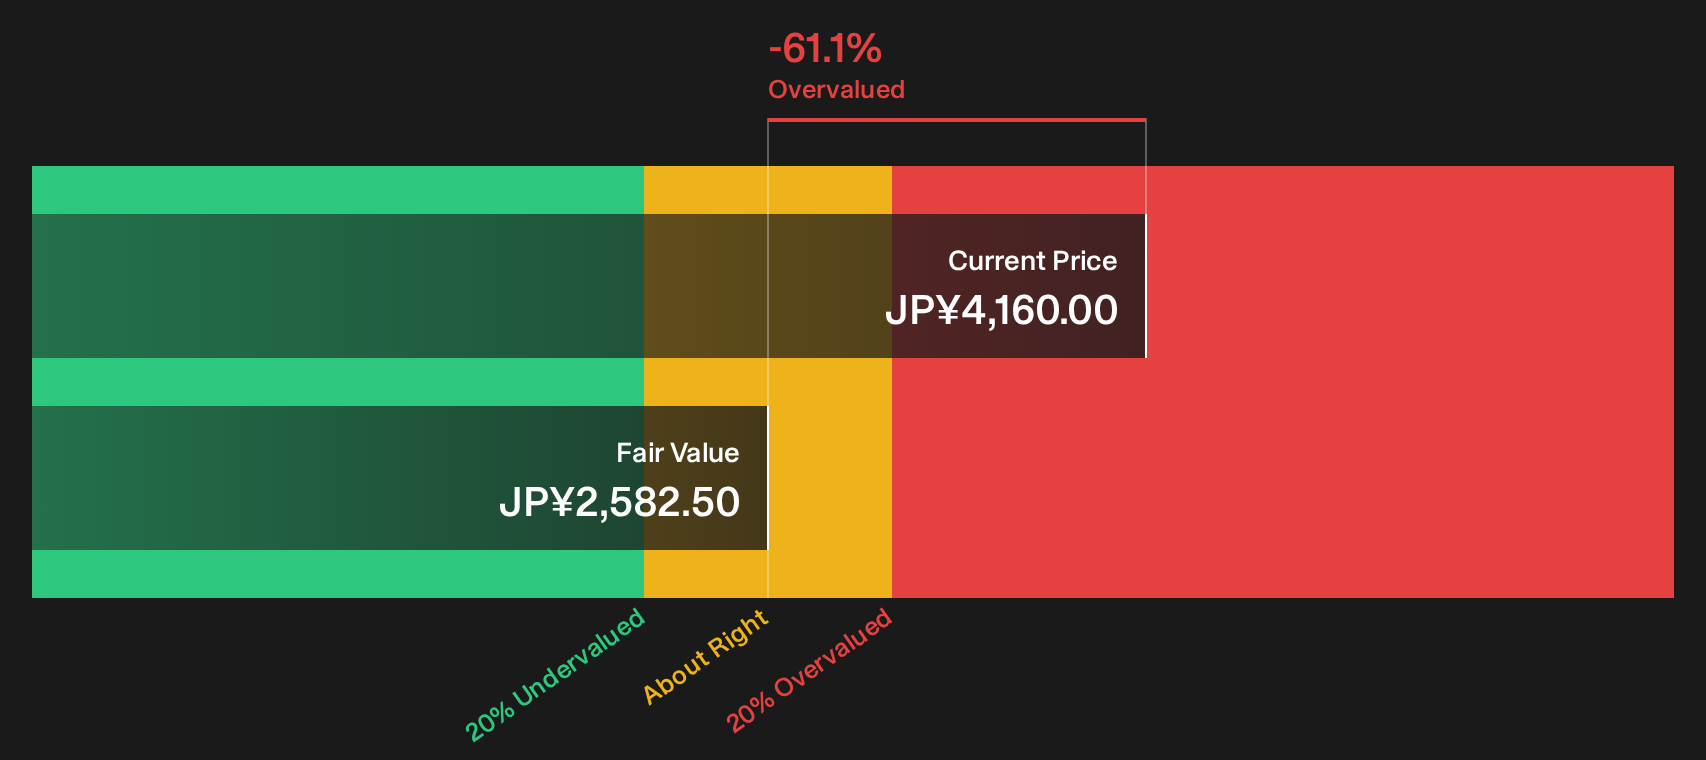
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kureha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mixed picture on Kureha leaves you undecided, move quickly from reading to testing the numbers yourself and pressure test both sides of the story with the 1 key reward and 2 important warning signs.
Looking for more Kureha alternatives and investment ideas?
Do not stop with Kureha. Apply the same scrutiny across a broader opportunity set and use data driven filters to surface ideas you might otherwise overlook.
- Target resilience by scanning a 21 resilient stocks with low risk scores that filters for companies with sturdier risk profiles than the broader market.
- Hunt for mispriced quality through a 75 high quality undiscovered gems that focuses on strong fundamentals that the crowd may be ignoring.
- Strengthen your core holdings with a 14 dividend fortresses that highlights higher yielding businesses focused on returning cash to shareholders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com