
Undiscovered Gems Three Promising Global Stocks with Strong Potential
As global markets navigate a complex landscape marked by interest rate hikes, volatile oil prices, and mixed performance across key indices, investors are increasingly seeking opportunities in the small-cap sector. In this environment of cautious optimism and selective investment strategies, identifying stocks with robust fundamentals and growth potential can be particularly rewarding.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Alexandria Group Oyj | 5.79% | 6.84% | 8.17% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Angler Gaming (DB:0QM)
Simply Wall St Value Rating: ★★★★★★
Overview: Angler Gaming plc is a company that invests in businesses providing online gaming services based in Malta, with a market capitalization of €416.92 million.
Operations: Angler Gaming generates its revenue primarily from iGaming activities, totaling €32.50 million. The company's financial performance is influenced by its ability to manage costs associated with these operations, which in turn affects its net profit margin.
Angler Gaming, a nimble player in the gaming sector, has shown impressive growth with earnings skyrocketing by 271% over the past year, outpacing its industry peers. The company's recent financials highlight a robust performance with second-quarter sales at €8.45 million and net income reaching €2.38 million, both up from last year's figures of €6.64 million and €0.47 million respectively. Trading at 87.6% below estimated fair value suggests potential undervaluation despite its volatile share price recently observed over three months, making it an intriguing prospect for those eyeing under-the-radar opportunities in this space.
- Navigate through the intricacies of Angler Gaming with our comprehensive health report here.
Review our historical performance report to gain insights into Angler Gaming's's past performance.

China Lilang (SEHK:1234)
Simply Wall St Value Rating: ★★★★★☆
Overview: China Lilang Limited, with a market cap of HK$3.39 billion, is engaged in the manufacturing and sale of branded menswear and related accessories in the People's Republic of China through its subsidiaries.
Operations: The company generates revenue primarily from the manufacturing and sale of menswear and accessories, amounting to CN¥4.41 billion.
China Lilang, a notable player in the apparel sector, reported sales of CNY 2.06 billion for H1 2026, up from CNY 1.73 billion last year. Despite this increase in sales, net income fell to CNY 215 million from CNY 243 million. The company declared an interim dividend of HKD 0.10 and a special dividend of HKD 0.04 per share, reflecting its commitment to shareholder returns despite earnings pressure. Over the past year, earnings grew by an impressive 12%, outpacing the luxury industry average of 7.7%. Trading at nearly half its estimated fair value suggests potential upside for investors looking at growth prospects within this segment.
NEUCA (WSE:NEU)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: NEUCA S.A. is a company based in Poland that primarily focuses on the wholesale distribution of pharmaceuticals, with a market capitalization of PLN 3.03 billion.
Operations: NEUCA generates significant revenue from its Pharmacy Wholesale segment, contributing PLN 12.93 billion, followed by Medical Operator and Clinical Trials at PLN 565.51 million and PLN 502.90 million respectively. The company also earns from the Manufacture of Pharmaceuticals and Insurance Activities, with revenues of PLN 456.02 million and PLN 225.42 million respectively.
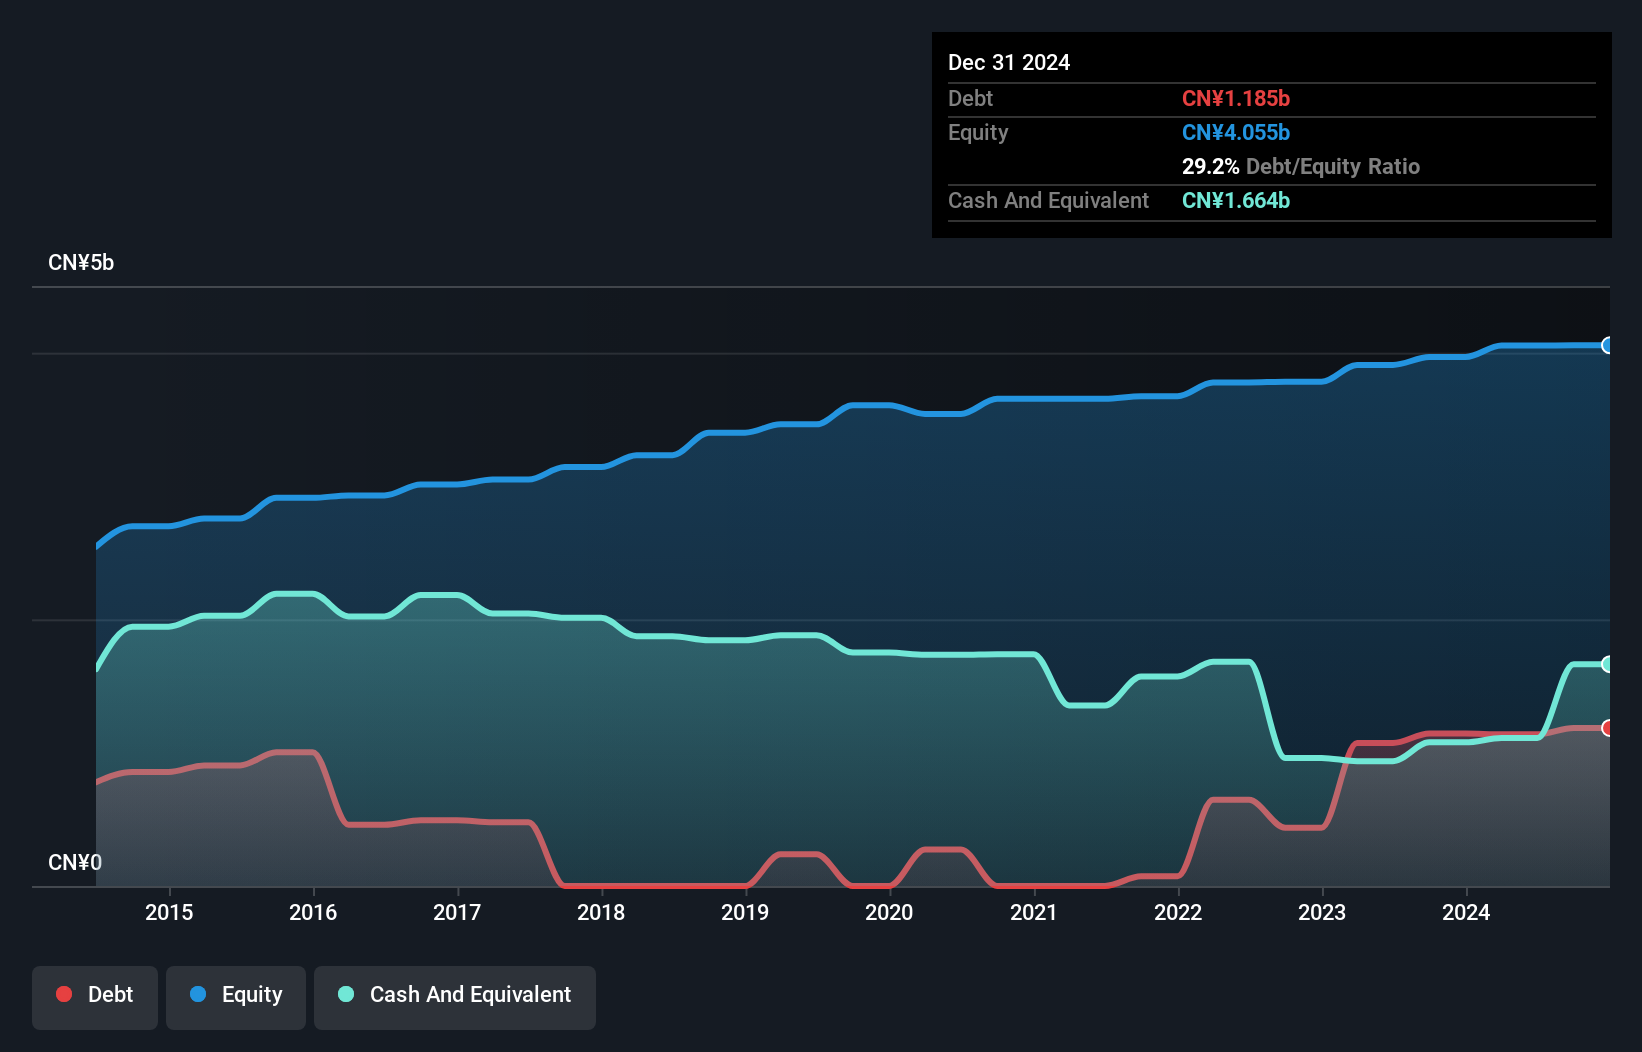
NEUCA, a player in the healthcare sector, has shown impressive growth with its earnings surging by 45.1% over the past year, outpacing the industry average of 15.9%. Despite trading at a significant discount of 63.5% below its estimated fair value, NEUCA's net debt to equity ratio stands at a high 42.2%, having climbed from 18.8% five years ago to 52.5%. The company's interest payments are comfortably covered by EBIT at a robust multiple of 10.5x, and it remains free cash flow positive with recent quarterly sales hitting PLN 3,570 million compared to PLN 3,268 million last year.
- Click to explore a detailed breakdown of our findings in NEUCA's health report.
Gain insights into NEUCA's past trends and performance with our Past report.

Seize The Opportunity
- Delve into our full catalog of 168 Global Undiscovered Gems With Strong Fundamentals here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com