
3 Undervalued Small Caps In Global With Recent Insider Activity
In recent weeks, the global markets have been marked by volatility, with small-cap stocks particularly lagging behind their large-cap counterparts as reflected in the underperformance of the Russell 2000 Index. Despite these challenges, opportunities may arise for investors who focus on small-cap companies that demonstrate strong fundamentals and have shown recent insider activity, suggesting potential confidence from those closest to the business.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| China Aircraft Leasing Group Holdings | 7.4x | 1.0x | 35.34% | ★★★★★☆ |
| Transcontinental | 2.5x | 0.2x | -98.80% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.1x | 3.0x | 8.19% | ★★★★☆☆ |
| Franchise Brands | 27.8x | 2.0x | 46.66% | ★★★★☆☆ |
| Saniona | 7.2x | 3.1x | 32.92% | ★★★★☆☆ |
| Yellow Pages | 8.5x | 0.8x | 27.82% | ★★★☆☆☆ |
| Diversified Royalty | 25.6x | 10.1x | 45.92% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.96% | ★★★☆☆☆ |
| ATS | 55.3x | 0.9x | 31.84% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -215.84% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
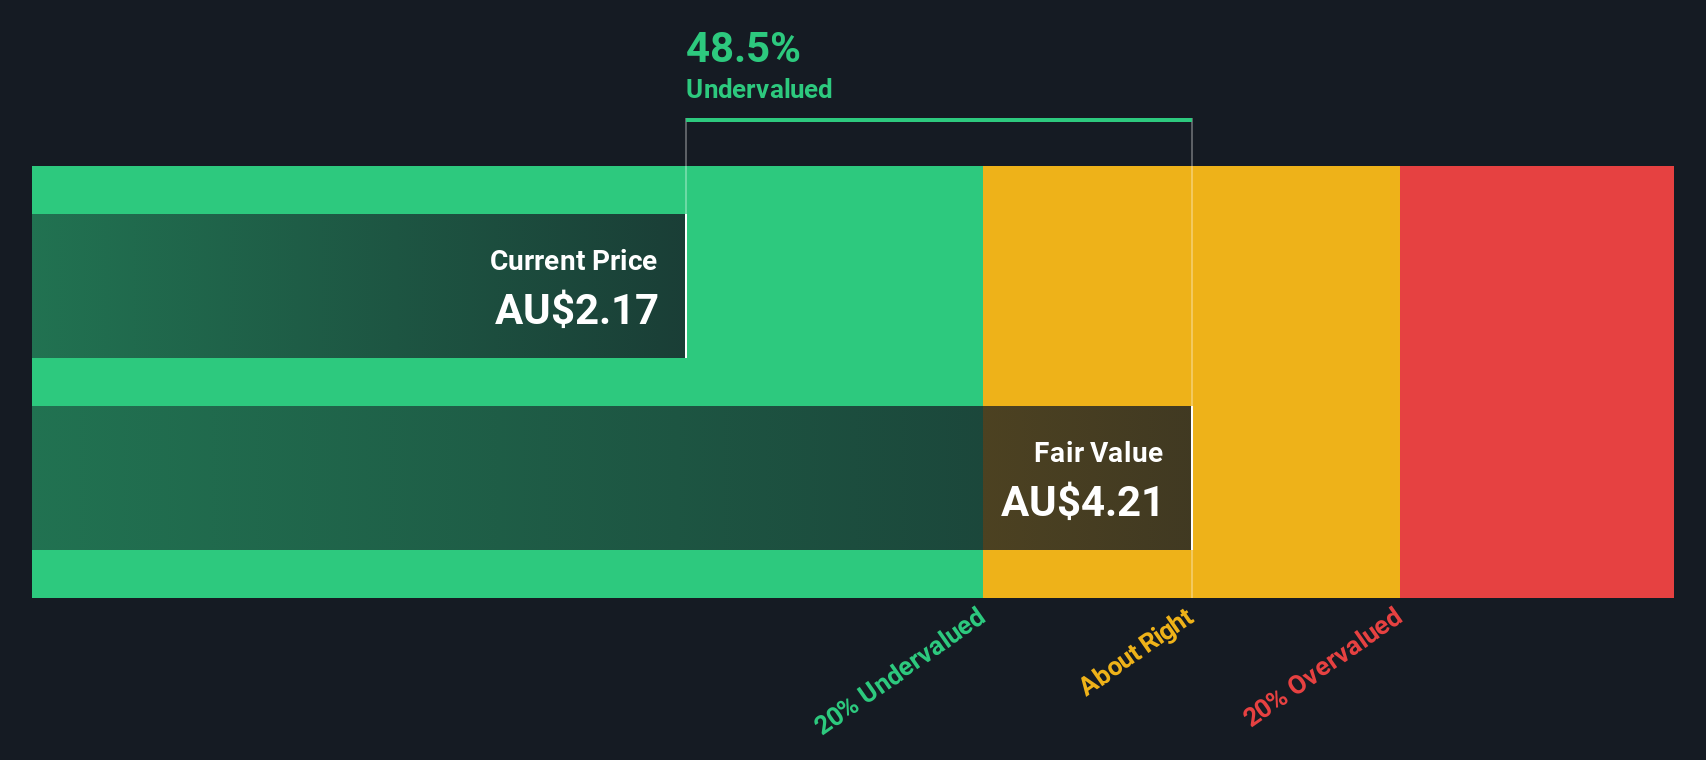
Navigator Global Investments (ASX:NGI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Navigator Global Investments operates as an asset management company primarily through its Lighthouse segment, with a market capitalization of approximately A$0.25 billion.
Operations: Lighthouse contributes significantly to the company's revenue, with a reported $142.09 million. The net income margin has shown varied trends, reaching as high as 1.02% in recent periods. Operating expenses and non-operating expenses have fluctuated over time, impacting overall profitability.
PE: 50.2x
Navigator Global Investments, a smaller company recently added to the S&P/ASX 300 and Small Ordinaries Index, is exploring acquisitions to enhance its earnings durability. Despite reporting a drop in net income from US$119.36 million last year to US$21.2 million this year, they forecast 30.61% annual earnings growth. Insider confidence is evident with recent share purchases by executives between July and September 2026, suggesting belief in the company's future potential amidst their acquisitive growth strategy for Fiscal Year 2027.
- Dive into the specifics of Navigator Global Investments here with our thorough valuation report.
Understand Navigator Global Investments' track record by examining our Past report.
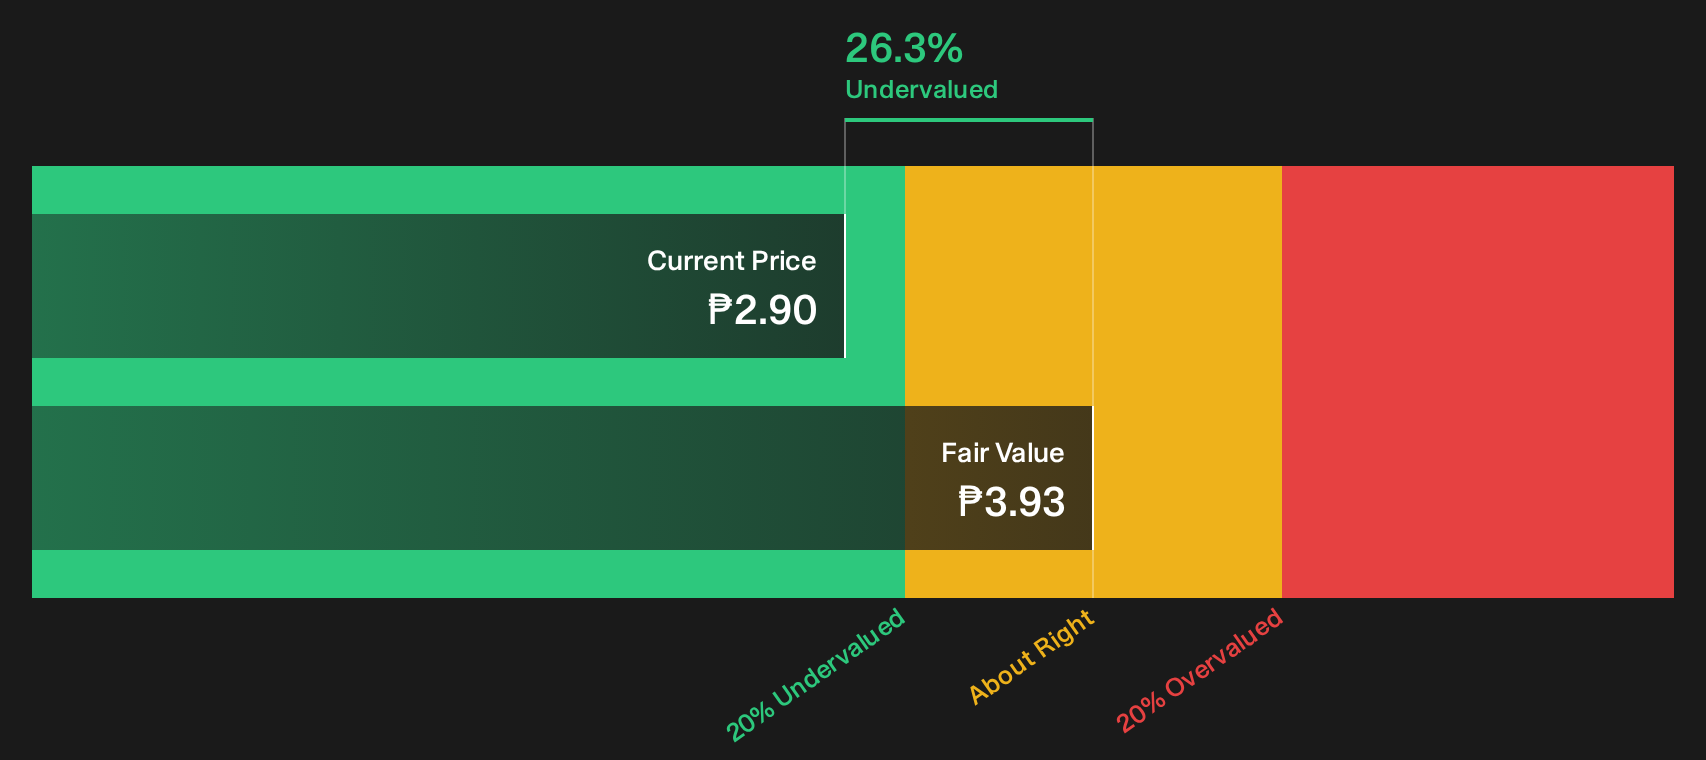
Citicore Energy REIT (PSE:CREIT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Citicore Energy REIT is a company primarily engaged in leasing operations, with a market capitalization of ₱15.6 billion.
Operations: CREIT generates revenue primarily through leasing, with a gross profit margin of 94.43% as of the latest financial period. The company has experienced fluctuations in its net income margin, reaching 75.71% recently, indicating a strong profitability trend over time.
PE: 13.3x
Citicore Energy REIT, a smaller player in the energy sector, showcases potential for those eyeing value opportunities. Despite its reliance on external borrowing for funding, earnings are projected to grow 7.92% annually. Recent financials show steady sales and net income growth for Q2 2026 compared to the previous year, with PHP 458 million in sales and PHP 344 million net income. Insider confidence is evident as insiders have been purchasing shares consistently throughout this year, hinting at optimism about future prospects.
- Get an in-depth perspective on Citicore Energy REIT's performance by reading our valuation report here.
Evaluate Citicore Energy REIT's historical performance by accessing our past performance report.
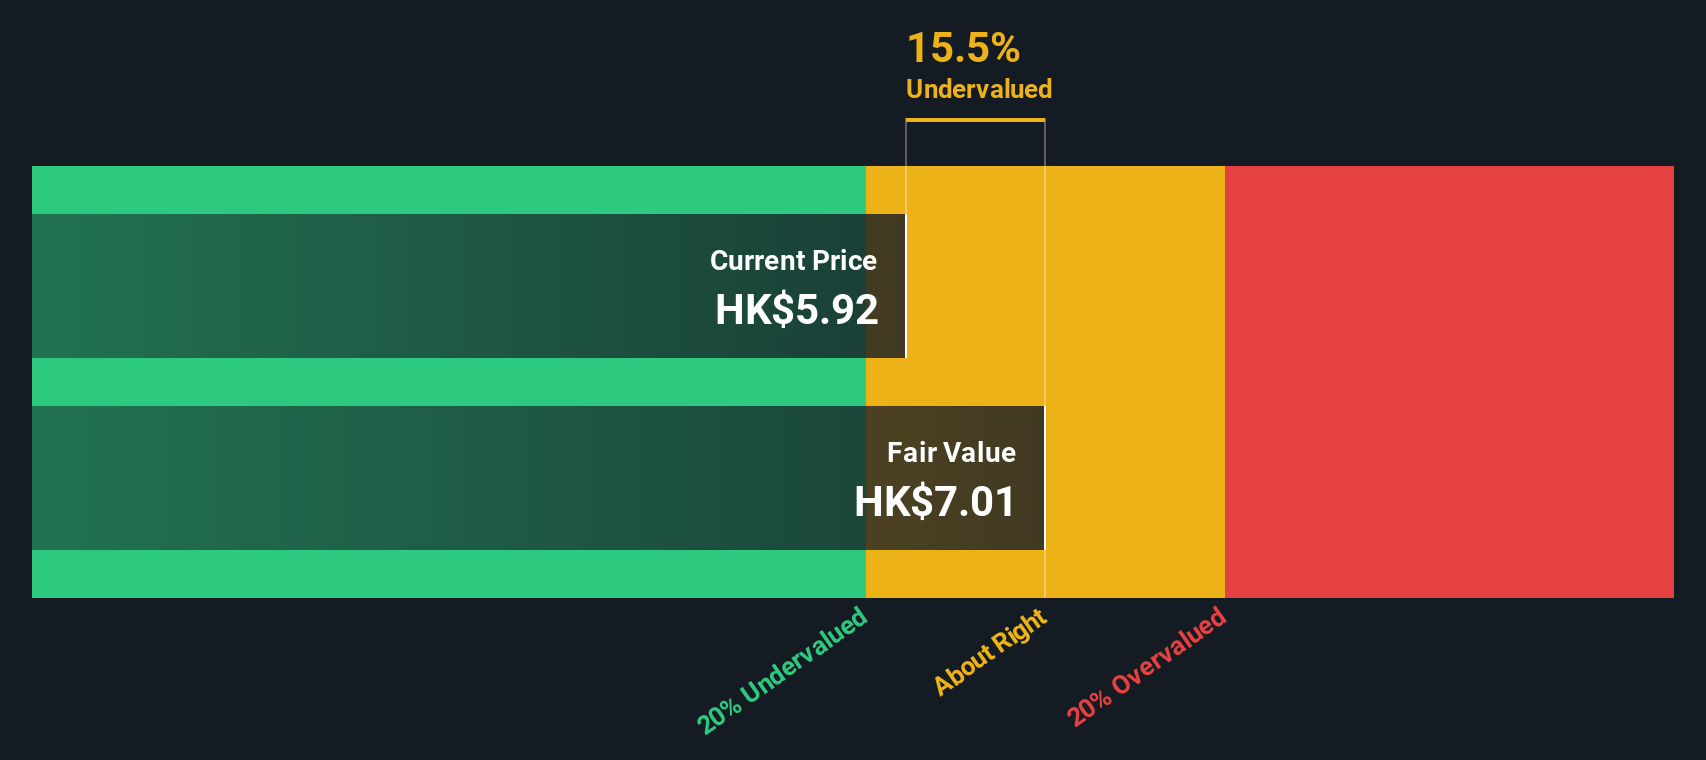
China Water Affairs Group (SEHK:855)
Simply Wall St Value Rating: ★★★★★★
Overview: China Water Affairs Group focuses on city water supply, environmental protection, and pipeline direct drinking water supply, with a market capitalization of approximately HK$10.2 billion.
Operations: The company's primary revenue sources include city water supply and environmental protection services, contributing significantly to its overall income. Over recent periods, the net profit margin has shown a declining trend, reaching 9.54% by March 2026. Operating expenses have consistently impacted profitability, with notable costs in general and administrative areas.
PE: 7.1x
China Water Affairs Group, operating in the water utility sector, presents a mixed investment opportunity. Despite earnings dropping to HK$986 million from HK$1.07 billion last year, insider confidence is evident with Non-Executive Director Xiaoqin Wang purchasing 102,000 shares for approximately HK$477,360 in August 2026. The company faces challenges with its debt coverage but anticipates annual earnings growth of 6.83%. Recent board changes include Ms. Wu Zhijun's appointment as an independent director, bringing extensive experience in debt capital markets to the table.
- Take a closer look at China Water Affairs Group's potential here in our valuation report.
Gain insights into China Water Affairs Group's past trends and performance with our Past report.
Where To Now?
- Click through to start exploring the rest of the 112 Undervalued Global Small Caps With Insider Buying now.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com