
FTSE Index Entry Could Change The Case For Nordnet Stock
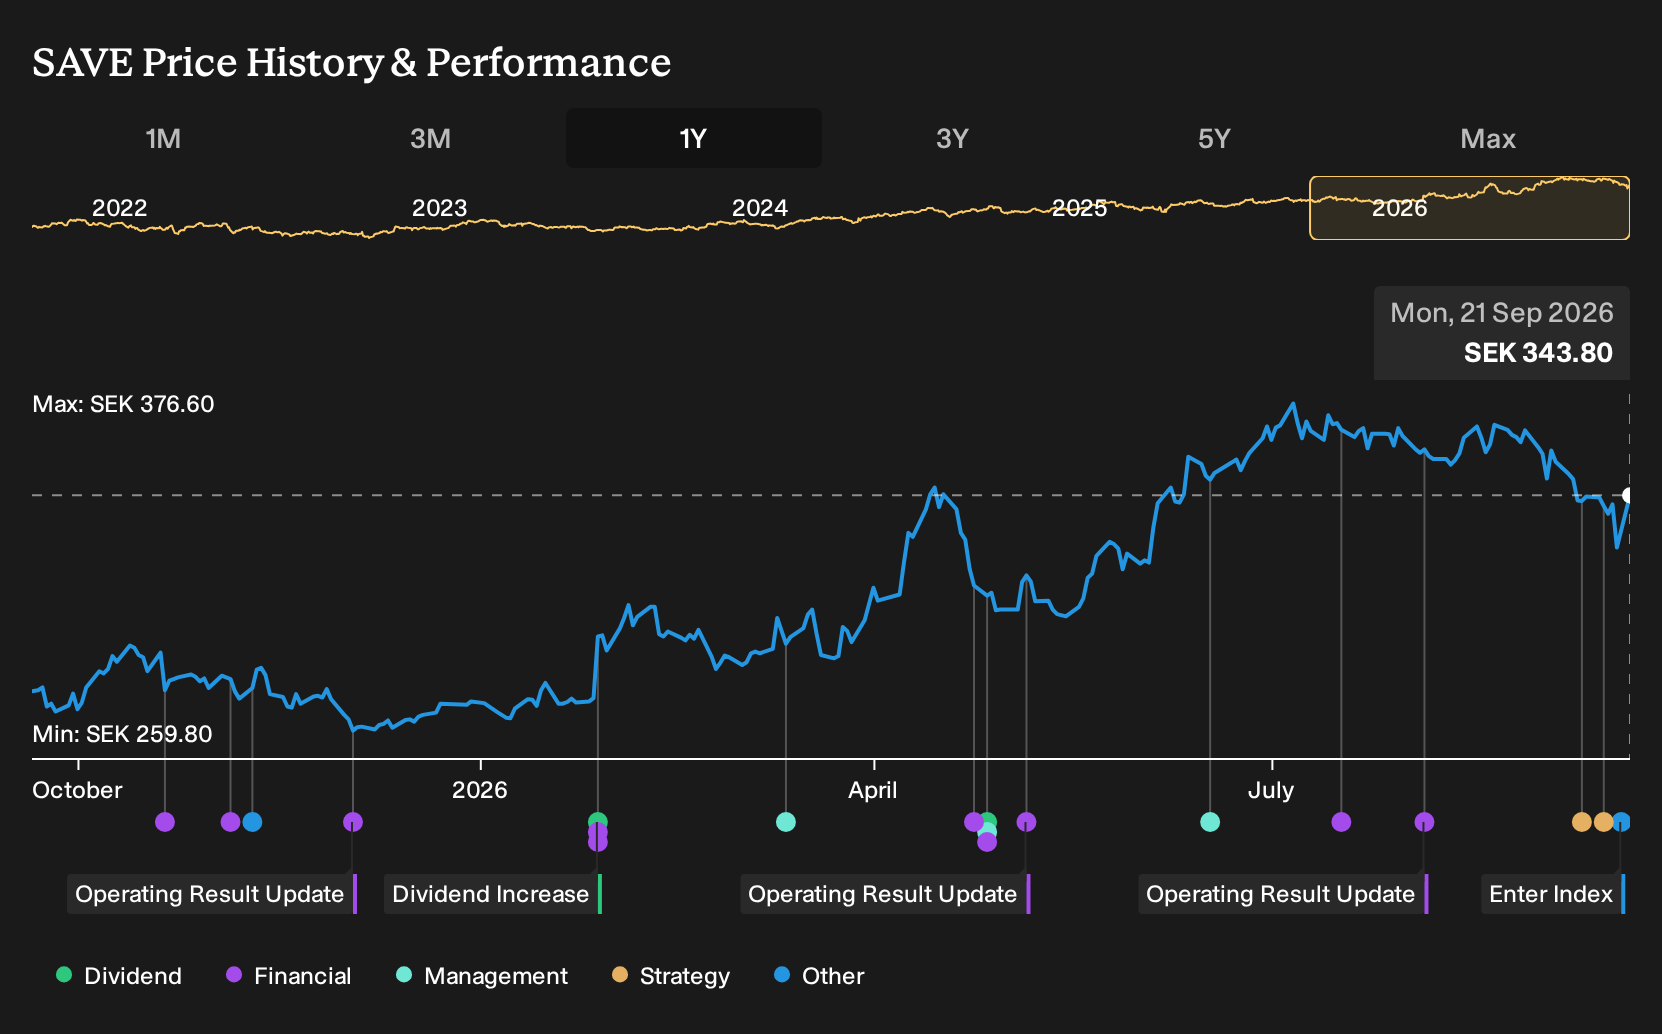
- Nordnet has been added to the FTSE All-World Index and, in recent weeks, agreed a 50/50 private banking joint venture with ABG Sundal Collier and launched a Research Portal with Citigroup for Nordic investors.
- The combination of index inclusion and deeper partnerships with ABG Sundal Collier and Citigroup points to a push to attract larger, research-driven private clients, while keeping Nordnet’s digital platform at the center of their activity.
- We will now examine how Nordnet's investment narrative could be influenced by FTSE All-World inclusion and the ABG Sundal Collier alliance.
Scan how Nordnet’s index inclusion and partnerships compare with other financial platforms pushing for research-led clients by reviewing the hand-picked list of solid balance sheet and fundamentals (198 results).
Nordnet Investment Narrative Recap
To own Nordnet, you need to believe its digital savings platform can keep adding active users and assets while holding pricing power against larger Nordic competitors. The short term swing factor still looks like customer activity and trading volumes, which drive a big share of income. Recent index inclusion and partnerships do not change that near term driver in a material way.
The biggest current risk remains cost growth running ahead of revenue, especially with investments in new markets like Germany and higher product development spend. Partnerships that target premium private banking customers may help mix, but they could also lift complexity and execution risk if uptake is slower than operating expenses.
The Citigroup Research Portal launch ties directly into Nordnet’s push toward higher value private banking tiers. Giving Platinum, Black and Signature clients full access to research on around 1,500 companies can support deeper engagement from larger accounts and potentially more stable fee income alongside trading commissions.
This tool also intersects with Nordnet’s existing catalysts. Stronger research access may help the business attract and retain wealthier households across the Nordics while it invests in Germany and other product lines such as pensions and funds. The operational test is whether usage justifies the added cost and platform complexity without adding pressure to already sensitive margins.
Nordnet's narrative projects SEK 8.2b revenue and SEK 4.8b earnings by 2029. This assumes 7.6% yearly revenue growth and an increase in earnings of SEK 1.4b from SEK 3.4b today.
Uncover why Nordnet's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate take focuses on Nordnet’s push into underpenetrated markets such as Germany and Denmark. The most optimistic analysts, who were already pencilling in SEK 8.5b of revenue and SEK 5.2b of earnings by 2029, see this expansion as the main upside swing factor. These forecasts came before the index inclusion and new alliances, so you may find it useful to compare them with your own expectations and explore how opinions could shift as the story evolves.
Explore 2 other Nordnet fair value estimates, including one that suggests potential upside of up to 9% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nordnet research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nordnet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordnet's overall financial health at a glance.
Looking for more investment ideas beyond Nordnet?
If the Nordnet story has sharpened your thinking, you can use that same lens to scan other opportunities across the market with the Simply Wall St Screener.
- For investors hunting for quality at a sensible entry point, you can start with companies flagged as potential value opportunities in the 173 high quality undervalued stocks.
- If capital preservation matters just as much as upside, you can review resilient businesses surfaced in the 229 resilient stocks with low risk scores.
- When you want strong finances as your foundation, you can broaden your watchlist using the list of solid balance sheet and fundamentals (198 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com