
SHEIN Global Holdings (SEHK:625) Could Be 62% Overvalued On Its EU Compliance Push
SHEIN Global Holdings (SEHK:625) just expanded its cooperation with the EU-backed SPEAC Project, with nine planned compliance training sessions for marketplace sellers centered on new European rules such as packaging, safety and digital product data.
For investors, the picture is mixed. SHEIN Global Holdings trades at HK$37.8, with a 1-day share price return of 1.94% and a 7-day share price return of 0.21%. However, the year-to-date share price return is down 22.06%. This suggests that short-term momentum is picking up while longer-term sentiment has cooled, despite recent operational moves such as the new Indiana fulfillment hub and this expanded EU compliance push.
Scan how SHEIN Global Holdings compares with other fast-scaling online platforms by checking a curated 616 high quality undiscovered gems that are quietly building reach and revenue in the background.
SHEIN Global Holdings is pushing hard on compliance and fulfillment capacity, which points to a serious operating platform. The real tension is simple: do the current HK$37.8 and recent share price swings reflect that strength or overshoot it?
Price-to-Earnings of 13x: Is it justified?
SHEIN Global Holdings trades at HK$37.8, and on a 13x P/E compared with peers closer to 7.8x, the stock carries a clear premium.
The P/E ratio links what you pay today to each unit of reported earnings, so it effectively reflects how much of SHEIN Global Holdings' profit profile the market is willing to pay for. For an online retail platform with global reach and multiple brands, that metric often bundles together expectations around future profit trends, competitive intensity and execution on compliance and logistics.
Here the gap is wide. SHEIN Global Holdings is described as expensive on a P/E basis versus both its peer group at 7.8x and the broader Hong Kong Specialty Retail industry at 8.8x. With profit margins at 3.7%, down from 7.7% last year, and earnings having declined 48.4% over the past year, the valuation suggests investors are still paying up relative to current profitability. If the market were to move closer to peer or industry levels, that P/E premium would need strong and consistent earnings delivery to feel fully justified.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 13x (OVERVALUED)
Still, that premium story can unravel quickly if earnings keep slipping against a 3.7% margin, and tighter EU rules start biting into third party marketplace activity.
Find out about the key risks to this SHEIN Global Holdings narrative.
Another View on SHEIN Global Holdings' Value
The P/E premium is only one lens. Our DCF model points the other way, with an estimated future cash flow value of HK$14.49 per share compared with the current HK$37.8 price, which flags SHEIN Global Holdings as overvalued on that framework. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
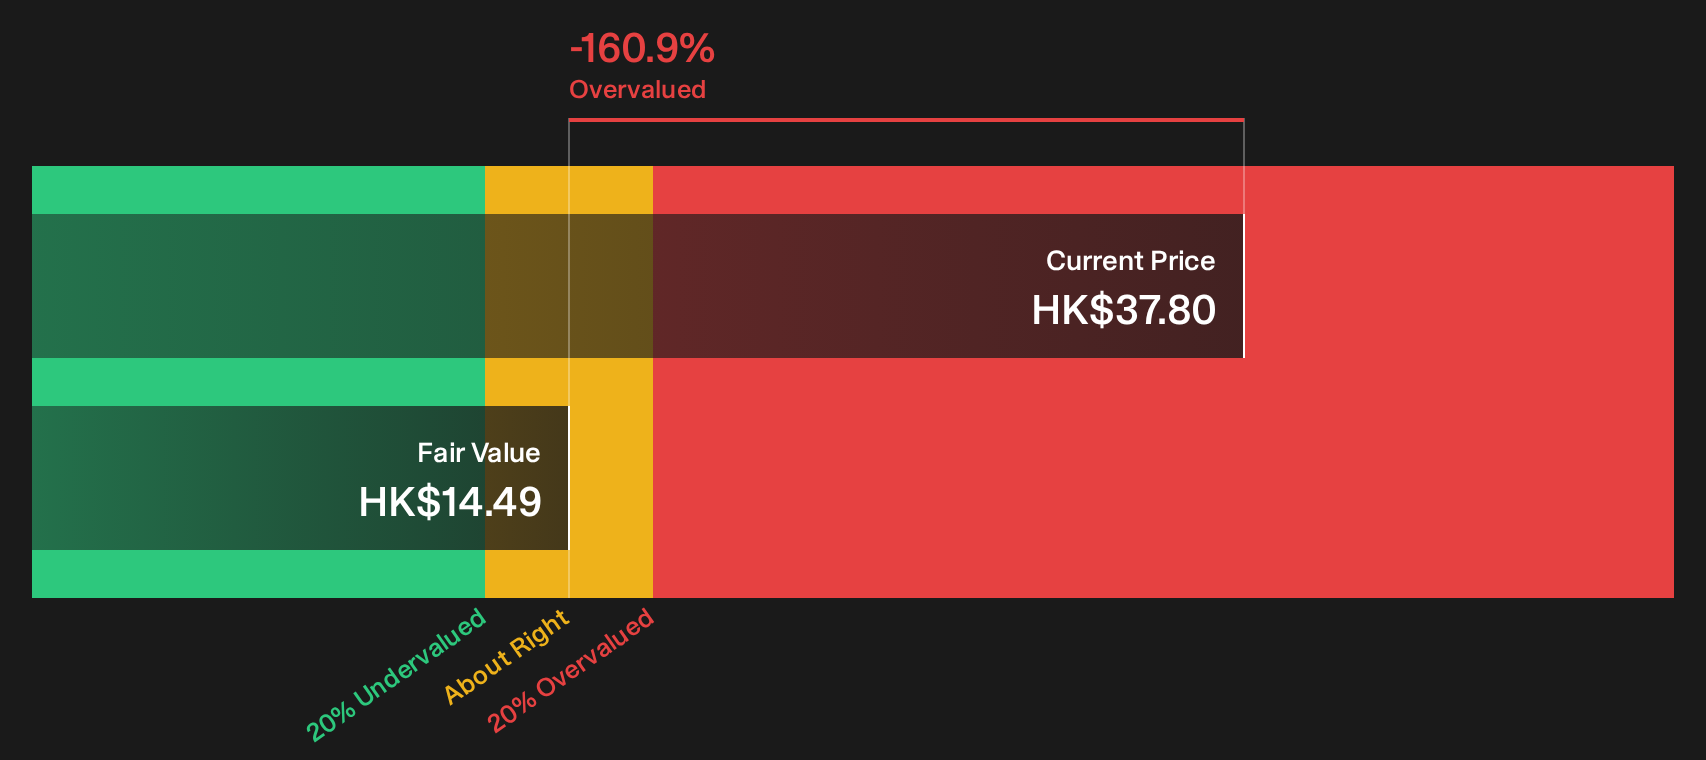
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHEIN Global Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on SHEIN Global Holdings so far, with both concern and optimism in the data, so move fast and weigh the 2 key rewards and 4 important warning signs.
Want more stock ideas beyond SHEIN Global Holdings?
If SHEIN Global Holdings has your attention, do not stop here. Fresh opportunities often sit just outside the obvious choices, and you do not want to miss them.
- Target companies that combine strong finances with appealing entry points by scanning a curated 178 high quality undervalued stocks aligned with quality fundamentals.
- Lock in steadier potential income streams by reviewing a focused 161 dividend fortresses that highlights payouts above 5% with robust support.
- Stack the odds toward resilience by filtering through a 229 resilient stocks with low risk scores designed to spotlight businesses with more stable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com