
3 Australian Penny Stocks With ROE Of At Least 20%
AI optimism has pushed global tech shares higher, reminding investors how quickly sentiment can shift when a clear theme captures attention. For Australian penny stocks with relatively strong balance sheets, that kind of focus on technology and efficiency can reward businesses that manage cash and debt carefully. This article highlights three financially healthier low priced stocks that screen well on fundamentals and may interest investors hunting for higher risk ideas.
The stocks highlighted below are just a small sample of financially fit penny stocks, with the full screen surfacing 394 more companies that also have detailed stories and fundamentals not covered here. To go beyond this short list, head straight into the Financially Fit Penny Stocks screener to identify, filter, and analyze penny stock ideas backed by stronger balance sheets.
Ora Banda Mining (ASX:OBM)
Ora Banda Mining runs the Davyhurst Gold Project in Western Australia, an operating mine that produces and sells gold ore. This aligns directly with the Financially Fit Penny Stocks focus on revenue-generating assets. Gold production and exploration generated about A$807 million, all from Australia, and the group is valued at roughly A$3.0b.
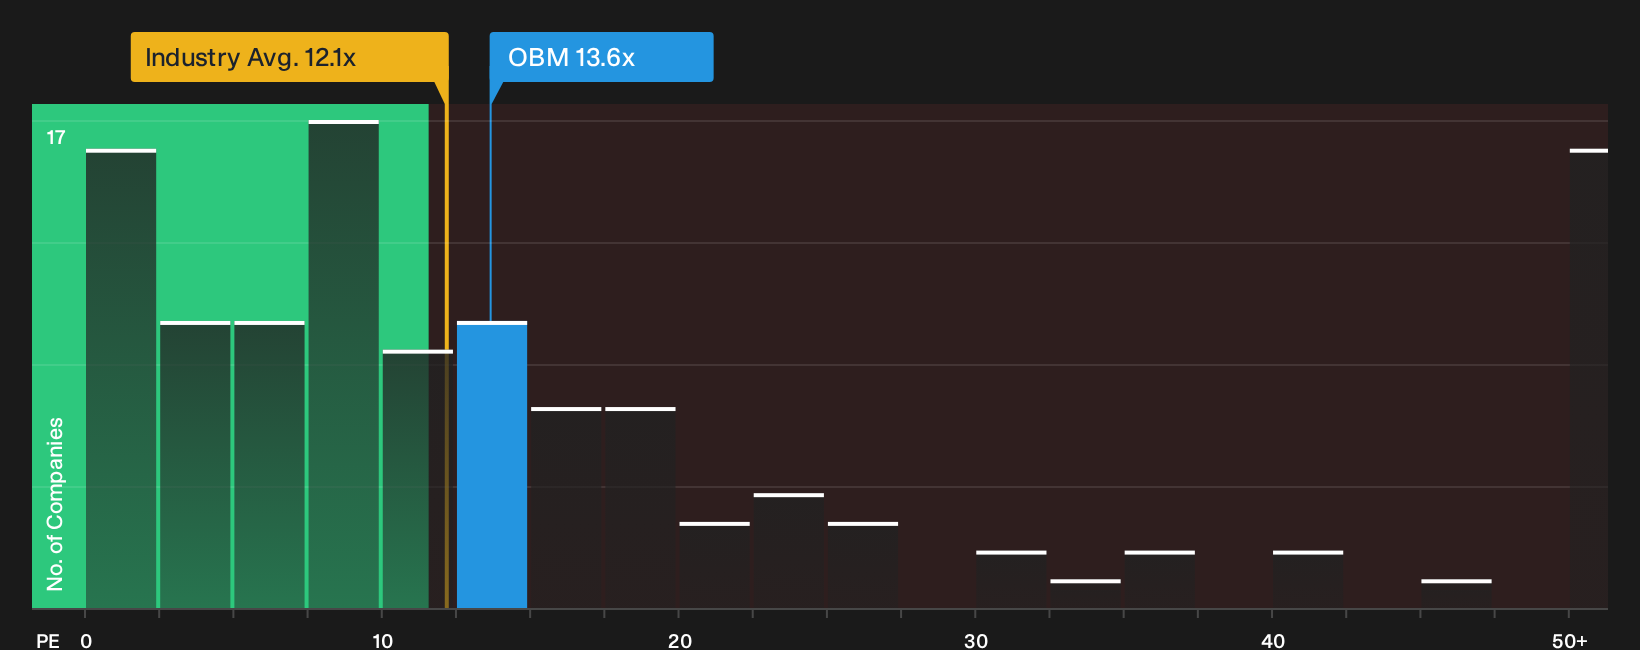
Ora Banda Mining suits this screener because it couples an operating gold project with small cap pricing and a reported P/E of 13.6x, while still posting a 40.3% ROE and 26.8% net margin. The real test for this financially fit story sits in how one unseen pressure shapes those margins over time.
That pressure point is exactly what the 3 key rewards and 1 important warning sign to see how those headline returns could be masking deeper shifts in the gold operation.
Alkane Resources (ASX:ALK)
Alkane Resources brings revenue producing gold mines into a penny stock price bracket, which fits neatly with a screener looking for smaller companies that already turn ore into cash rather than relying only on early exploration promises.
Alkane Resources runs producing gold mines and exploration projects, with revenue anchored by Tomingley at about A$417 million, Costerfield at A$270 million, and Bjorkdal at roughly A$249 million, all from Australia, and the group is valued near A$2.7b.
"The main risk is that Alkane is now a more complex business. Instead of one operation, investors must understand three mines, three jurisdictions, different cost structures, underground mining risk, antimony market volatility, and a large future capex project at Boda-Kaiser."
What happens to Alkane Resources if a single assumption in that multi mine mix shifts the balance between healthy cash flow and rising strain?
When that balance starts to shift, the full narrative for Alkane Resources shows how Alkane Resources could turn complexity into accelerating opportunity or creeping strain.

DroneShield (ASX:DRO)
DroneShield builds counter-drone systems that fit neatly with a financially fit penny stock theme, because its hardware and software solutions are tied to real world defence and security budgets rather than only early stage concepts.
Aerospace and defense operations generate about A$270 million in revenue for DroneShield, while the stock carries a market value near A$1.6b.
"If management continues converting its growing pipeline into multi-year contracts while expanding margins through scale manufacturing, we could see a valuation re-rating over the next 12 to 24 months."
What happens if a single assumption in that shift from one off projects to repeat institutional orders breaks the link between growth and financial resilience.
If that link breaks, the full narrative for DroneShield shows where contract momentum, margin shifts, and funding risk could accelerate or stall DroneShield's story.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying quickly, and the best entry points often drop away before the crowd catches on. Consider looking for them early.
- Spot potential breakouts with reliable earnings strength before sentiment chases them higher by scanning the 6 high quality undervalued stocks while those ideas still sit under the radar for now.
- Ride structural tailwinds in digital assets by tracking companies tied to blockchain momentum using the curated 19 cryptocurrency and blockchain stocks while that theme still feels under owned.
- Target long term income ideas that aim to keep paying investors through cycles by reviewing the hand picked 3 dividend fortresses while yields remain elevated.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com