
Is Tokyo Electric Power Company Holdings (TSE:9501) A Bargain Or Fully Priced?
Without a clear fresh headline catalyst, Tokyo Electric Power Company Holdings (TSE:9501) is drawing attention for its long record as a core Japanese utility and its mixed recent share performance across different time frames.
Recent trading paints a mixed picture for Tokyo Electric Power Company Holdings, with the share price at ¥549.7 after a 1-day decline of 1.17%. The 90-day share price return stands at 16.78%, while the 1-year total shareholder return is down 16.70%, and the 5-year total shareholder return remains positive at 62.15%.
Scan how Tokyo Electric Power Company Holdings compares with other infrastructure focused utilities by screening a hand picked set of 40 power grid technology and infrastructure stocks.
For Tokyo Electric Power Company Holdings, a 90 day gain alongside a weaker 1 year record raises a simple tension: Are investors reacting to business fundamentals, or simply cycling through a change in sentiment as the valuation case is reassessed?
Price-to-Earnings of 2.2x: Is it justified?
Valuation on Tokyo Electric Power Company Holdings currently hinges on a very low P/E multiple of 2.2x, which sits against a last close of ¥549.7 and raises questions about how the market is weighing its earnings profile against peers.
The P/E ratio compares what investors are paying for each unit of current profit. For a regulated utility with a long operating history like Tokyo Electric Power Company Holdings, this measure often reflects how dependable earnings appear, how clean the profit line is, and how investors view the stability of those cash flows.
Tokyo Electric Power Company Holdings is trading at 2.2x earnings, while the peer group average sits at 8.2x and the wider Asian electric utilities space is around 14.5x. The estimated fair P/E of 12.3x is also far higher than the current figure, which highlights a substantial gap between how the market is pricing the stock today and where valuation might gravitate if sentiment and earnings quality were more in line with sector norms.
Explore the SWS fair ratio for Tokyo Electric Power Company Holdings.
Result: Price-to-Earnings of 2.2x (UNDERVALUED)
Still, the Tokyo Electric Power Company Holdings story could be challenged by regulatory shifts around nuclear and thermal assets or by any setback in earnings quality metrics.
Find out about the key risks to this Tokyo Electric Power Company Holdings narrative.
Another View on Tokyo Electric Power Company Holdings' Value
The P/E story on Tokyo Electric Power Company Holdings looks cheap, but the SWS DCF model points the other way. That framework estimates future cash flows at about ¥51.92 per share, far below the current ¥549.7 level, which implies an overvalued result on this method.
That kind of gap suggests investors are paying far more than the DCF view of future cash flows. The key question is whether you trust the earnings-based signal or the cash flow model when weighing risk and potential reward.
Look into how the SWS DCF model arrives at its fair value.
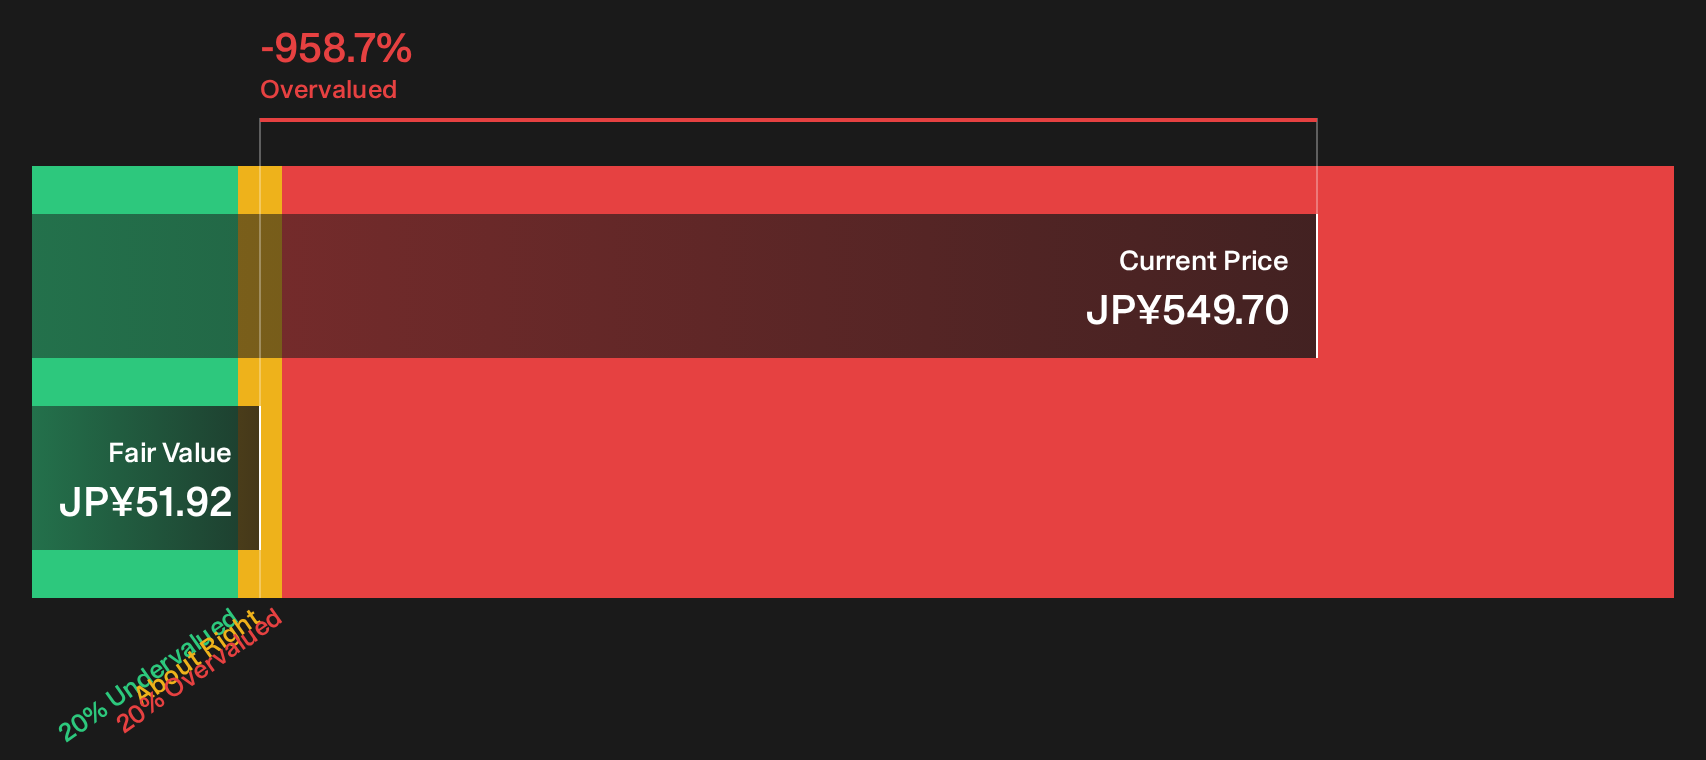
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Electric Power Company Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Tokyo Electric Power Company Holdings can feel confusing, so act promptly, review the data for yourself, and weigh both sides using 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Tokyo Electric Power Company Holdings?
If Tokyo Electric Power Company Holdings has you rethinking your watchlist, this may be a useful time to widen your search with a few focused stock ideas.
- Target resilient balance sheets and cleaner fundamentals by scanning a curated list of solid balance sheet and fundamentals (21 results) that can help anchor a diversified portfolio.
- Look for quality at a discount by checking out a carefully built 17 high quality undervalued stocks that filters for both financial strength and attractive pricing.
- Focus on under-the-radar opportunities by reviewing a 75 high quality undiscovered gems that many investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com