
Saipem (BIT:SPM) Is Getting More Attention, What Is Behind It?
Index inclusion puts Saipem on more investors’ radar
Saipem (BIT:SPM) has been added to the FTSE All-World Index in USD terms, a move that can draw fresh attention from index trackers and larger institutions that are watching global equity benchmarks.
Recent trading has been lively. Saipem’s share price return is up 4.28% over the past week after a 1.64% move on the day. However, the 30 day and 90 day share price returns are down 3.32% and 4.16%, suggesting short term momentum has cooled, even as the 73.40% year to date share price return and 90.65% one year total shareholder return keep longer term performance firmly in positive territory.
Scan how Saipem’s index move compares with other globally exposed contractors by reviewing our hand-picked list of solid balance sheet and fundamentals (198 results).
Bulls see Saipem’s index entry and recent gains as validation of a stronger business, while bears focus on the softer 30 and 90 day returns. Which side does the current valuation support?
Most Popular Narrative: 28% Undervalued
On this widely followed view, Saipem’s fair value of €5.99 sits well above the last close at €4.34, which puts the focus on how future projects and margins might support that gap under a 9.19% discount rate.
The imminent Mozambique LNG restart, where Saipem claims €3 billion in backlog exposure, combined with deepening exposure to global gas infrastructure, can trigger a sharp step-change in both revenues and EBITDA, as energy security and LNG expansion rapidly accelerate across Africa and other growth markets.
See why 8 investors see Saipem as 28% undervalued.
Result: Fair Value of €5.99 (UNDERVALUED)
Still, heavy reliance on traditional oil and gas projects, along with recurring execution issues on complex contracts, could quickly challenge this 28% undervalued Saipem narrative.
Find out about the key risks to this Saipem narrative.
Another view on Saipem’s valuation
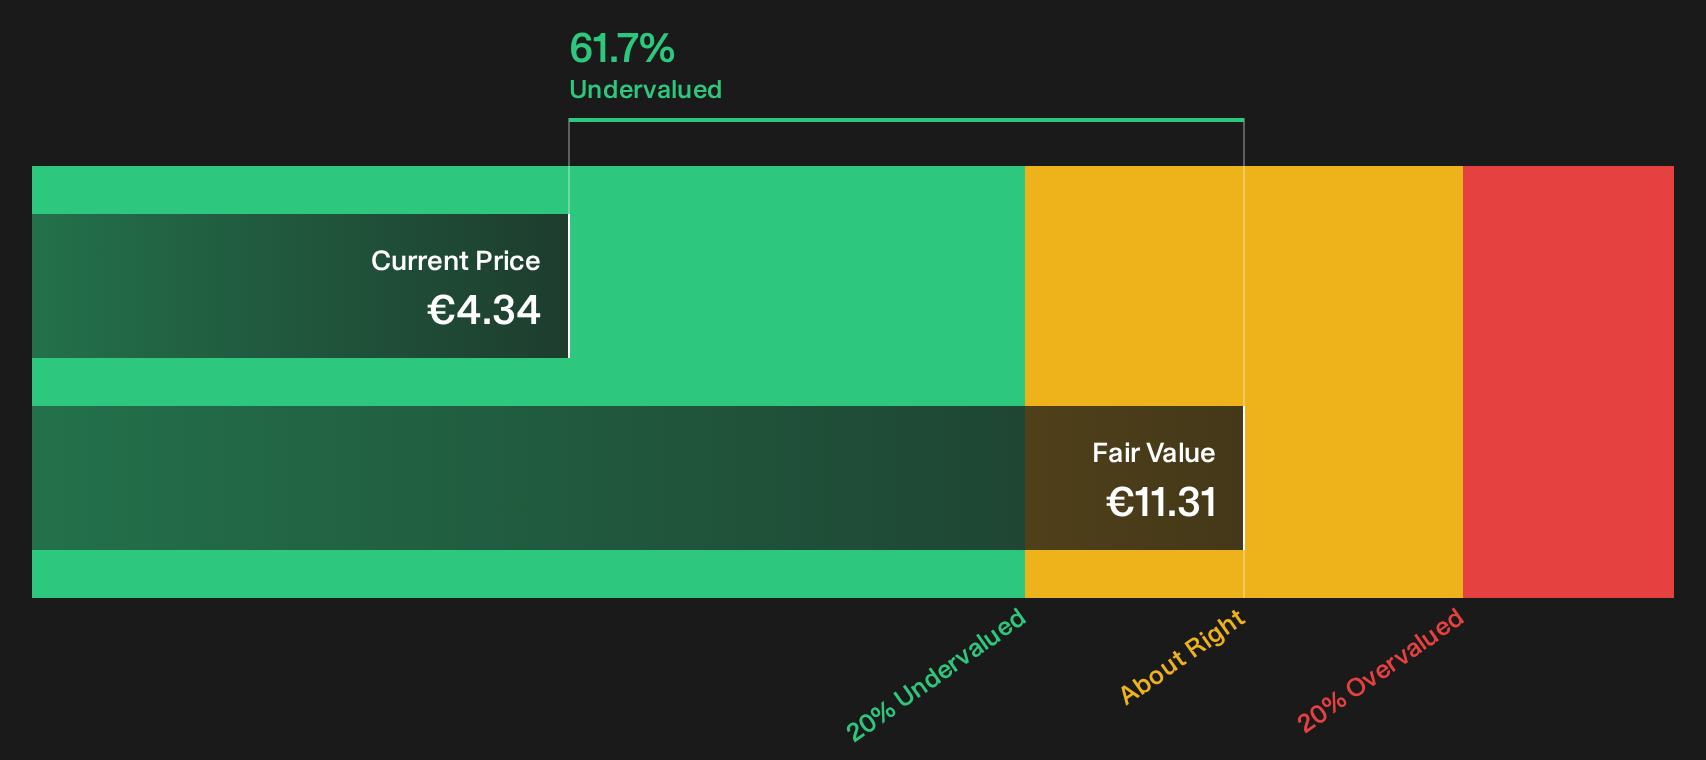
The SWS DCF model paints a very different picture for Saipem. On this approach, the shares at €4.34 are compared with an estimated future cash flow value of €11.31, which frames the stock as deeply undervalued. If a cash flow lens signals opportunity while earnings multiples look stretched, which one do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Saipem so far? Use that tension as a prompt to move fast, review the underlying numbers, and decide where you stand after weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Saipem?
If Saipem has your attention, do not stop there. Broaden your watchlist now and give yourself more ways to put fresh opportunities to work.
- Target potential mispricing by scanning our 178 high quality undervalued stocks that combine solid business quality with prices that may not fully reflect their fundamentals.
- Strengthen your income stream by reviewing 161 dividend fortresses that focus on higher yielding payouts with an emphasis on resilience.
- Sleep easier at night by filtering for 229 resilient stocks with low risk scores that prioritise stronger balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com