
Imperial Oil (TSX:IMO) Dropped, What Is Driving Attention Now?
Imperial Oil (TSX:IMO) has come under closer scrutiny after a recent pullback, with the share price down about 6% over the past month despite a gain over the past three months.
For context, Imperial Oil’s recent pullback comes after a powerful run, with the share price showing a year-to-date return of 45.19% and a 5-year total shareholder return of 417.78%. Recent momentum appears to be cooling rather than resetting the longer-term trend.
Scan opportunities riding similar momentum to Imperial Oil, and pressure test your ideas against our curated 6 high quality undervalued stocks list.
Imperial Oil’s surge over the past year, followed by a softer month, could signal either a business that has simply caught up to its fundamentals or a swing in sentiment. Which story does the valuation tell next?
Most Popular Narrative: 13% Overvalued
Imperial Oil last closed at CA$177.58 against a narrative fair value of CA$157.12. This sets up a valuation gap that hinges on how the business turns operational upgrades into durable profitability.
Major efficiency improvements at Kearl, including unit cash cost reductions (~CA$2/bbl year over year, productivity upgrades, and extension of turnaround intervals), position Imperial Oil for sustained margin expansion and higher ROIC as production targets increase toward 300,000 barrels per day. These initiatives are described as improving future net margins and earnings. Digitalization and automation investments, such as autonomous haul systems and process optimization, are delivering tangible cost reductions and paving the way for further operational efficiencies. This is described as structurally improving competitive position, lowering operational risk, and supporting long-term net margin improvement.
See why 30 investors see Imperial Oil as 13% overvalued.
Result: Fair Value of CA$157.12 (OVERVALUED)
Still, that story can be knocked off course if oil sands heavy assets face tighter decarbonization rules, or if ongoing capital needs squeeze Imperial Oil’s free cash flows.
Find out about the key risks to this Imperial Oil narrative.
Another View: Cash Flows Tell a Different Story
While analysts see Imperial Oil as 13% overvalued against the CA$157.12 narrative fair value, our DCF model points in almost the opposite direction. On that lens, CA$177.58 compares with an estimated future cash flow value of about CA$303.12, which suggests the current price may be too low rather than stretched. Which signal do you trust more when cash flows and multiples are this far apart?
For readers who want to see how this cash flow driven estimate is built up line by line, it is worth walking through the SWS DCF model inputs and assumptions in more detail, starting with the discount rate and margin path used for Imperial Oil. Look into how the SWS DCF model arrives at its fair value.
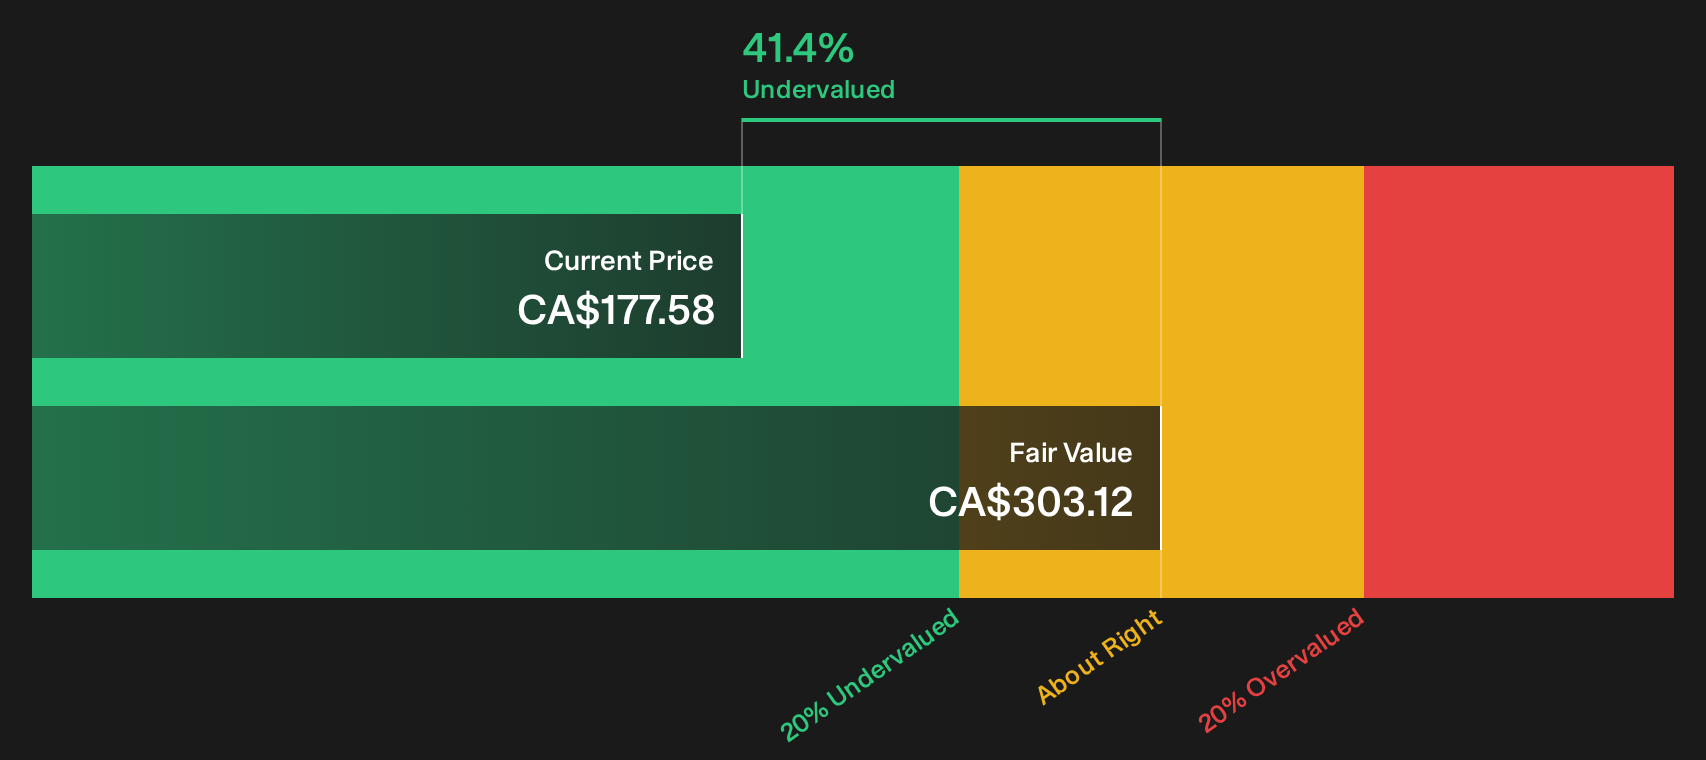
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Imperial Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Imperial Oil’s value story so far. For a sharper view, weigh the upside against the downside by checking the 2 key rewards and 1 important warning sign.
Ready To Find Your Next Idea Beyond Imperial Oil?
If Imperial Oil has sharpened your thinking on valuation gaps, now is the moment to broaden your watchlist with a few focused, data driven opportunities.
- Target potential mispricings by scanning our curated set of quality opportunities using the 6 high quality undervalued stocks.
- Prioritize resilience by reviewing a 8 resilient stocks with low risk scores that highlights businesses with more defensive risk profiles.
- Unearth potential future leaders by working through a 9 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com