
Domino's Pizza (DPZ) Joins Skip In Canada, Is The Stock Still Cheap?
Domino's Pizza (DPZ) is back in focus after joining the Skip delivery network in Canada, a move aimed at widening reach and adding fresh promotional power in a crowded delivery market.
Recent trading has been choppy for Domino's Pizza. The share price is now US$295.94 after falling about 13% over the past month and more than 30% year to date, while the 1 year total shareholder return is also down sharply. This hints that investors have been reassessing both growth prospects and risk, even as management signs new delivery partnerships and the stock is dropped from the FTSE All-World Index.
Scan beyond Domino's Pizza and compare it with hand picked consumer service stocks using our 30 high quality undervalued stocks for ideas that combine quality, strong cash flow, and potential mispricing.
Domino's Pizza now trades well below the average analyst target, even though its intrinsic value estimate sits almost flat to the current price. Is this a genuine discount or caution that still makes sense?
Most Popular Narrative: 27.5% Undervalued
On the most followed narrative, Domino's Pizza screens as undervalued, with a fair value estimate of $408.07 against the last close of $295.94, even though the story leans heavily on a mature but profitable franchise model rather than rapid expansion.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around ~20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake "pizza slice" in the company.
See why 12 investors see Domino's Pizza as 27% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, Domino's Pizza faces pressure if analyst assumptions on margins or revenue prove too optimistic, or if delivery partnerships dilute returns instead of supporting profitability.
Find out about the key risks to this Domino's Pizza narrative.
Another View: Domino's Pizza Through A Different Lens
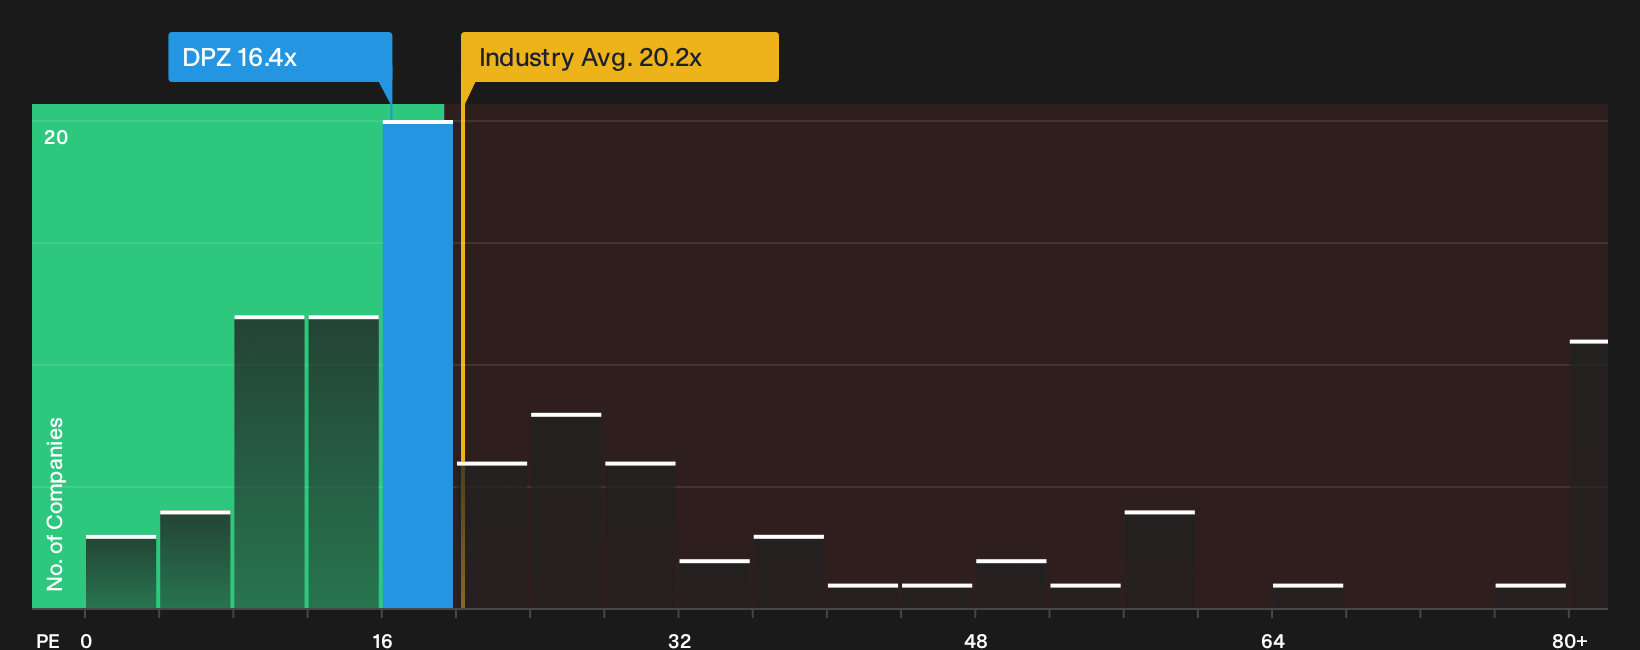
The popular narrative around Domino's Pizza leans on detailed fair value models and Monte Carlo simulations that suggest the stock is undervalued. A separate lens uses a simple P/E check. At 16.4x, the multiple sits below peers at 24.2x and under a fair ratio of 19.6x, which points to potential mispricing. Is that a cushion for long term buyers or a signal that expectations have reset for a reason?
To see how this earnings multiple picture holds up against a deeper breakdown, including what the numbers imply for risk and upside, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed message or clear signal? If Domino's Pizza leaves you on the fence, move quickly, review the numbers, and weigh the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
If Domino's Pizza has sharpened your focus on valuation and quality, do not stop here. Use the Simply Wall Street Screener to broaden your opportunity set thoughtfully.
- Target dependable income by reviewing companies that make it into our 7 dividend fortresses and see which payouts align with your risk comfort.
- Hunt for mispriced opportunities by scanning the 17 high quality undiscovered gems where fundamentals and market attention are not always in sync.
- Prioritise resilience first by filtering for businesses in the 30 resilient stocks with low risk scores so you are not the last to spot sturdier options.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com