
Cintas (CTAS) Could Be 7% Undervalued If Its Growth Narrative Holds
Cintas (CTAS) has become a talking point for investors after a stretch of mixed share performance, with the price down over the past month but higher across the past 3 months.
That mixed pattern extends beyond the past month, with Cintas showing a 15.18% 90-day share price return but a slightly negative 1-year total shareholder return of 0.86%, which signals fading near term momentum even as long term holders have seen strong gains over three and five years.
Compare Cintas' mixed recent returns with a hand picked group of sturdier balance sheet plays using our list of solid balance sheet and fundamentals (23 results) to see how other operators have held up over the same stretch.
After that mix of recent gains and slips, the real tension for Cintas holders is simple. Does the current price still offer enough upside potential to justify the risk now showing up in the chart and the valuation?
Most Popular Narrative: 7% Undervalued
Cintas last closed at $196.88, while the most followed narrative pegs fair value around $212.41 using a 7.11% discount rate. That gap, along with recent share price swings, has turned the focus to whether the current valuation reasonably reflects the cash flow story described in that work.
Continued expansion of product and service offerings, such as advanced safety solutions, recurring revenue hygiene products like AED rentals, and specialized vertical programs (healthcare privacy curtains, chef's attire), enables Cintas to capture greater wallet share from customers and benefit from the persistent demand for workplace safety, which should drive above-market revenue growth and higher margins.
See why 34 investors see Cintas as 7% undervalued.
Result: Fair Value of $212.41 (UNDERVALUED)
Still, the Cintas narrative hinges on physical workplaces and successful UniFirst integration, so prolonged remote work trends or missed synergy targets could quickly challenge the current upside case.
Find out about the key risks to this Cintas narrative.
Another View On Cintas Valuation
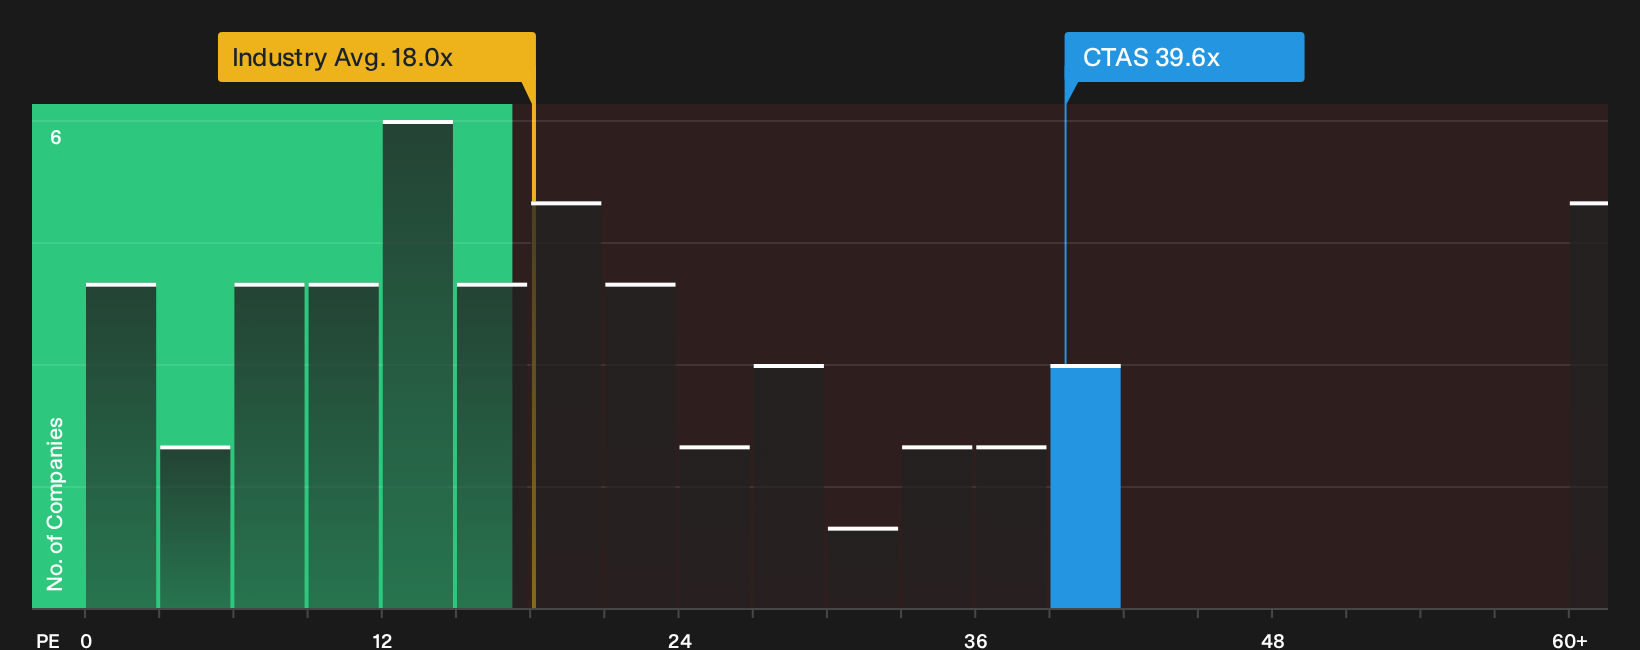
Multiples tell a different story. Cintas trades on a P/E of 39.6x, compared with a fair ratio of 26.8x, a peer average of 30.9x, and an industry level of 18x. That premium suggests investors are paying up for quality, but it raises the question of how much valuation risk remains if expectations cool.
See what the numbers say about this price in the valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Cintas does not have to leave you on the fence. Use the detailed data, weigh both sides quickly, then ground your own stance in 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cintas?
Cintas may be your starting point, but the real edge comes from lining it up against other opportunities that fit your risk, income, and growth goals.
- Target resilient balance sheets by comparing Cintas with companies screened through our list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by checking out our hand picked pool of 30 high quality undervalued stocks.
- Build a cash flow focused watchlist by reviewing a curated set of 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com