
Is Reddit (RDDT) Cheap As Its Anthropic Court Win Sharpens The AI Data Case?
Reddit’s court win over Anthropic puts data licensing in focus
A recent court ruling in Reddit’s (RDDT) favor, confirming that Anthropic is bound by Reddit’s User Agreement on data use, has pushed the platform’s role in AI training into the spotlight for investors.
Reddit’s recent legal win comes after a choppy run for the stock, with the share price at US$155.67 and the year to date share price return down 35.64%. Short term moves look more muted, with a 30 day share price gain of 1.55%, while the 1 year total shareholder return has declined 34.44%. This suggests that investors are still reassessing both the opportunity and the risks around data licensing and AI exposure.
Scan beyond Reddit’s headline legal win and compare it with other AI exposed platforms using our hand picked 36 AI small caps for potential data licensing and model training beneficiaries.
Reddit is changing hands at US$155.67 while sell side fair value estimates cluster much higher, with an average target of US$213.71 and intrinsic models implying an even larger gap. How much of that spread looks justified?
Most Popular Narrative: 50% Undervalued
Reddit’s most followed valuation narrative points to a fair value of $309.77 per share, roughly double the recent $155.67 price, which puts heavy weight on user activity turning into both ad revenue and AI data licensing income.
Successful ad networks are driven fundamentally by usage. The best type of usage is on returning daily users usually measured by Daily Active Users. The higher the number of unique daily active users the higher the ad revenue generated on a per day basis.
While ad networks and profitability and growth are generally optimised through delivery i.e FB size scale and optimisations. In the early stage of a company sheer user number and therefore impressions drive a huge part of the narrative for ad spenders to use the platform.
See why 31 investors see Reddit as 50% undervalued.
According to kinnth, the narrative rests on Reddit’s ability to convert its engaged communities into two revenue streams. One is the traditional ad model that leans on Daily Active Users and impressions. The other is licensing the platform’s conversational data to AI players that want structured, real world problem solving content for model training.
In that view, the current $30.5b market cap is being compared to a fair value near $60b, using a discount rate of 8.68% and an assumed profit margin of 24%. The story argues that Reddit’s current earnings profile and high Return on Equity of 26.5% leave room for further monetisation if both advertising and data deals continue to build off the same user base.
For investors weighing the recent court decision on Anthropic, this narrative frames the ruling as one piece of a bigger question. How much value can Reddit extract from its community generated content without dampening user engagement, and how much of that upside is already reflected in the $155.67 share price versus a narrative fair value of $309.77.
Result: Fair Value of $309.77 (UNDERVALUED)
Still, the Reddit narrative could wobble if user engagement softens or if AI data licensing deals prove smaller or slower than enthusiasts expect.
Find out about the key risks to this Reddit narrative.
Another view of Reddit’s valuation
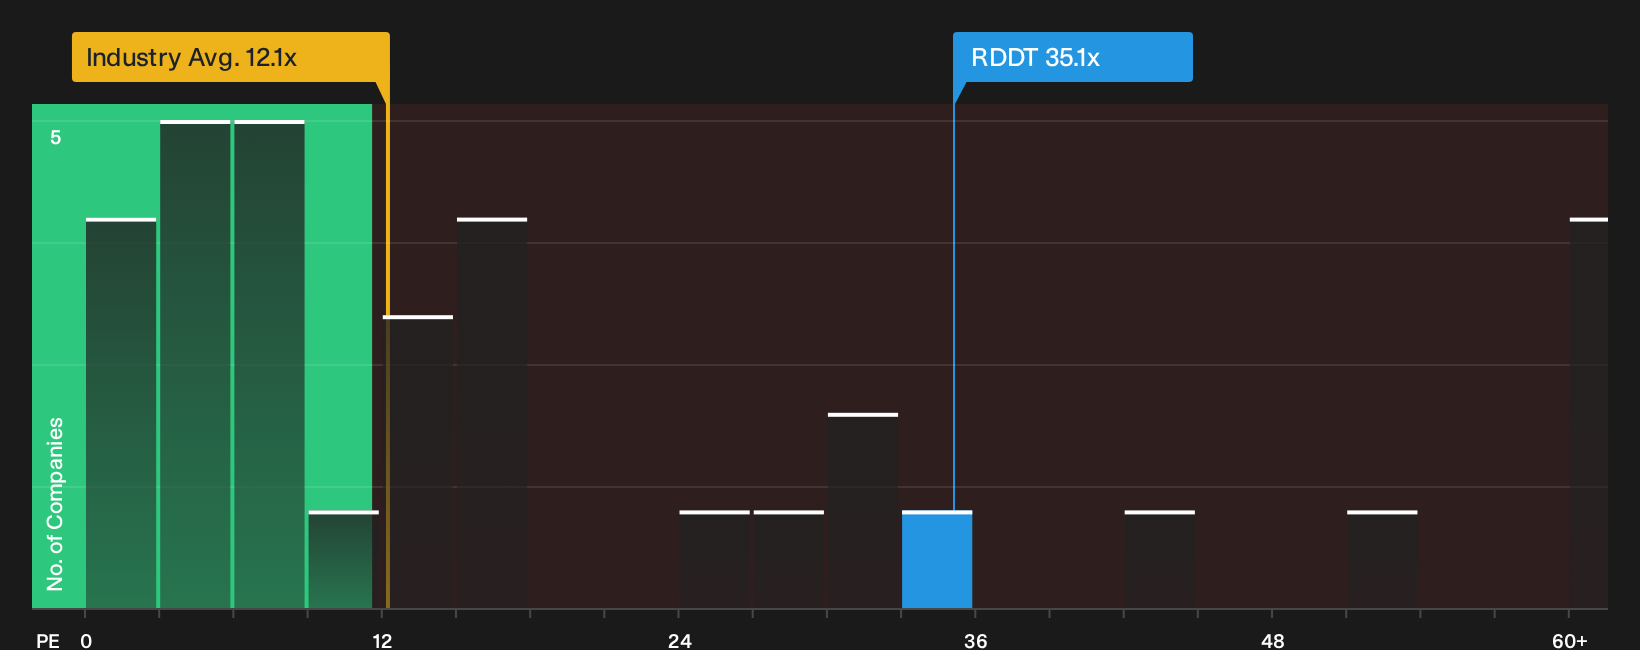
The user driven fair value story paints Reddit as heavily undervalued. A simple earnings multiple tells a tighter story. At a P/E of 34.4x, the stock trades well above the US Interactive Media and Services group at 12.1x, its peer set at 28.9x, and even the 29.7x fair ratio.
That gap can signal investors are already paying up for growth, which leaves less room for mistakes if Reddit’s AI licensing or advertising ramps more slowly than hoped. It raises a blunt question: is this valuation a cushion or a source of pressure?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Reddit’s valuation and AI exposure are clear. Move quickly from reading to testing the numbers yourself and decide where you land on the story by weighing the 3 key rewards and 1 important warning sign.
Looking for more Reddit-adjacent investment ideas?
If Reddit’s AI and data licensing story has your attention, do not stop here. Cast a wider net now and give yourself more ways to put capital to work.
- Target resilient performers by scanning a 30 resilient stocks with low risk scores that emphasises durability when conditions get choppy.
- Hunt for mispriced opportunities through a 29 high quality undervalued stocks built around quality fundamentals and compressed expectations.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (23 results) that focuses on sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com