
Is SPIE (ENXTPA:SPIE) Still Undervalued Following Its Recent Share Price Rebound?
SPIE (ENXTPA:SPIE) drew fresh attention after its recent share price move, with the stock up 4.2% on the day and modestly higher over the past week.
SPIE’s recent bounce comes after a weaker patch, with the 90-day share price return down 11.34% and the year-to-date share price return down 8.90%. However, the 5-year total shareholder return of 152.75% points to a much stronger longer-term story.
Scan how SPIE compares with other potential turnaround stories by reviewing our curated list of 170 high quality undervalued stocks that also pair recent weakness with stronger multiyear returns.
The recent rebound in SPIE after a softer spell raises a simple fork in the road. Has most of the easy upside already played out, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 14% Undervalued
SPIE last closed at €44.82, while the most followed narrative points to a fair value of €52.00, which frames the recent rebound against a still sizeable valuation gap.
The company's disciplined bolt-on M&A strategy and smooth integration of recent acquisitions are delivering accretive margin improvement while expanding SPIE's capabilities in high-growth areas such as building automation and fiber optic infrastructure. This supports both revenue and profit margins. SPIE is successfully shifting its project mix toward higher-margin, recurring maintenance and service contracts. This is resulting in structural margin expansion and greater earnings resilience despite cyclical fluctuations in some business lines.
See why 5 investors see SPIE as 14% undervalued.
Result: Fair Value of €52.00 (UNDERVALUED)
Still, if demand for data center projects or German high voltage and grid work proves weaker than analysts expect, SPIE’s earnings path could look very different.
Find out about the key risks to this SPIE narrative.
Another View On SPIE’s Valuation
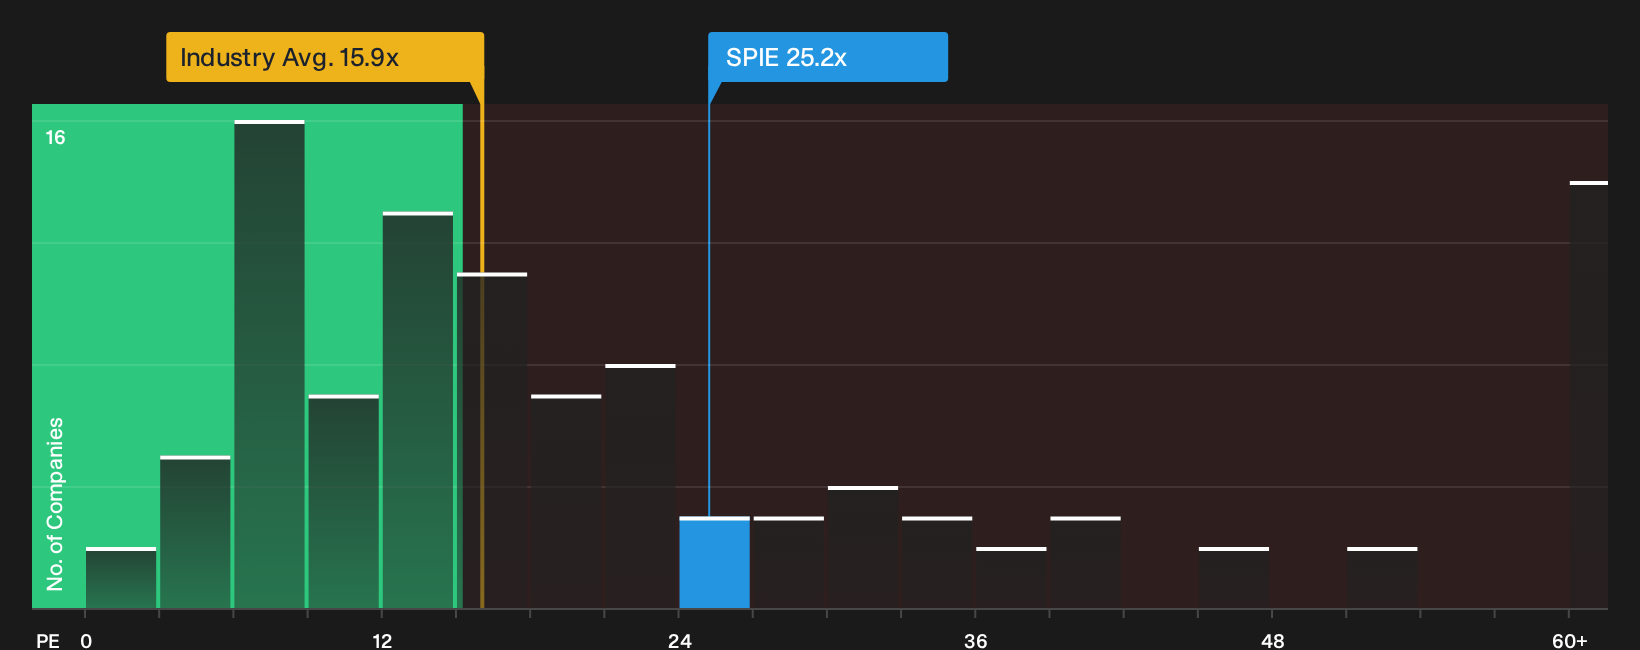
On the other side of that €52.00 fair value narrative sits SPIE’s current P/E of 25.2x. This is higher than both the European Commercial Services average of 15.9x and a fair ratio of 22x. That gap points to richer pricing on earnings, so how much comfort should investors really take from the valuation gap story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on SPIE after all that, or starting to feel more confident about the story? Move quickly, stress test your own thesis, then weigh SPIE’s 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SPIE?
If SPIE has sharpened your interest, do not stop here. Fresh opportunities often appear first in focused stock lists built from consistent rules.
- Target resilient income by reviewing companies that show up in our 159 dividend fortresses and see which payouts might complement SPIE in your portfolio.
- Hunt for quality at a discount by scanning the 615 high quality undiscovered gems and spot businesses the wider market may be overlooking.
- Tilt toward capital protection by filtering for steadier profiles through the 230 resilient stocks with low risk scores before the crowd chases the same ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com