
SkyWest (SKYW) Stock Still Looks Like A Bargain Today
SkyWest has been on a strong multi year run, which puts fresh attention on whether the current share price is still in line with what its earnings can support. With the stock now trading around US$101.20, the key issue for you is how that tag compares with the profits the airline operator is generating today.
- Over the past 3 years, SkyWest has delivered a total return of about 144.0%, which puts real weight on the question of whether its earnings performance can keep backing that kind of share price change.
- The regional carrier’s model of flying under contract for larger airlines can influence how consistently profits convert to cash, which matters for how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on SkyWest worth weighing. See what analysts think SkyWest's shares could be worth.
The issue now is whether SkyWest’s current market value is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether SkyWest’s recent run justifies its current P/E, it can help to compare it with a wider group of 29 high quality undervalued stocks as a second research starting point.
Does SkyWest Look Undervalued on Earnings?
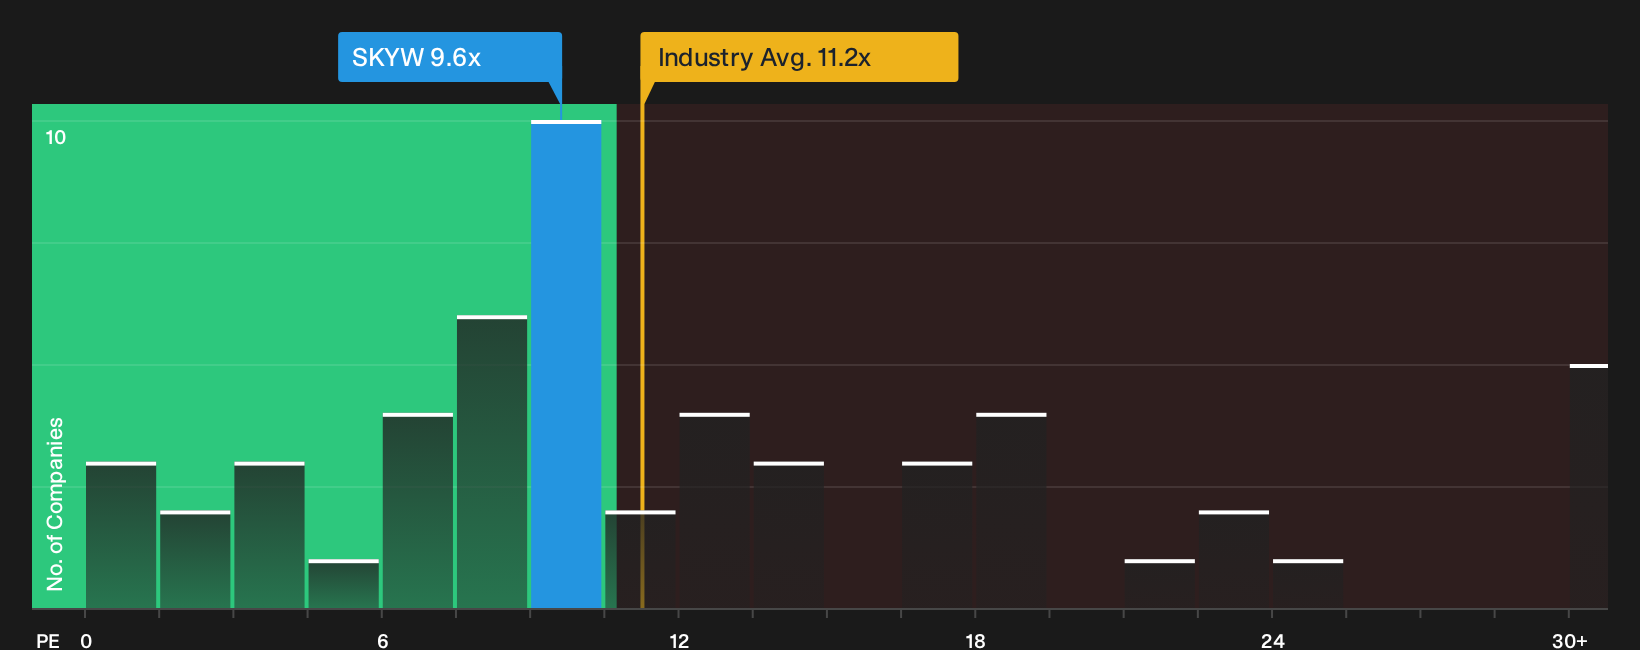
The P/E lens suits SkyWest because earnings are a central driver for how investors typically judge airline operators. On this measure, SkyWest trades on a P/E of about 9.6x, which is below both the Airlines industry average of roughly 11.2x and a peer group closer to 14.4x. For a reader, that means the market is currently paying fewer dollars for each dollar of SkyWest earnings than it is for many sector rivals.
The Fair Ratio, which blends factors like growth profile, margins, size and risk into a tailored benchmark, points to a higher multiple than the one the shares carry today. That gap suggests the stock is pricing in more caution than this framework implies is necessary, at least on recent earnings power. Whether that discount looks appealing depends on how you judge the resilience of SkyWest’s contracts, the quality of its cash flow and your tolerance for airline cycle risk. Explore the numbers behind SkyWest's P/E valuation.
The SkyWest Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle on SkyWest leaves off by spelling out which future paths for earnings, margins and growth would need to play out for the stock to be worth meaningfully more or less than it is today on the market. Instead of one static output from a ratio or model, these narratives break that single figure into the underlying expectations it rests on, so you can follow SkyWest's actual progress against those assumptions over time on the Community page.
Community views on SkyWest are split between those who see more upside left and others who think the current price already bakes most of it in.
Bull case: 20% undervalued
"Expansion of revenue streams through new flying agreements (including capacity purchase and prorate with major carriers, as well as potential enhanced charter services) decreases reliance on legacy CPAs..."
Discover why this Narrative puts SkyWest at 20% undervalued.
Bear case: roughly fairly valued
"Although long term extensions on E175 and CRJ flying with major partners support contract revenue visibility into the late 2020s, the absence of new E175 contract expirations until the back half of 2028 limits opportunities to reprice flying or expand margins meaningfully..."
Explore why this Narrative puts SkyWest at roughly fairly valued.
One more SkyWest puzzle the market is quietly watching
Valuation only tells part of the SkyWest story, because recent transactions by people inside the business raise a different question about what those closest to it are doing with their own holdings. See the recent insider selling flagged for SkyWest.

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com