
Why These Regional Bank Stocks Matter As The Fed Eases Discount Window Access
Fed Vice Chair Jefferson just put a spotlight on the plumbing of the financial system, and that quiet shift in how banks tap the discount window could matter a lot more to your portfolio than the latest headline about rates. Liquidity is getting easier to access for healthy institutions, which can change how risk is priced. This article walks through three regional bank stocks tied to that story and shows where the news might help or hurt.
The banks in the spotlight below are just a starter set, while the full screen surfaced 52 more regional and mid-sized institutions with equally compelling stories that are not covered here. To go deeper, head straight into the U.S. Regional and Mid-Sized Commercial Banks screener to identify, filter, and analyze the highest-conviction plays in this corner of the market.
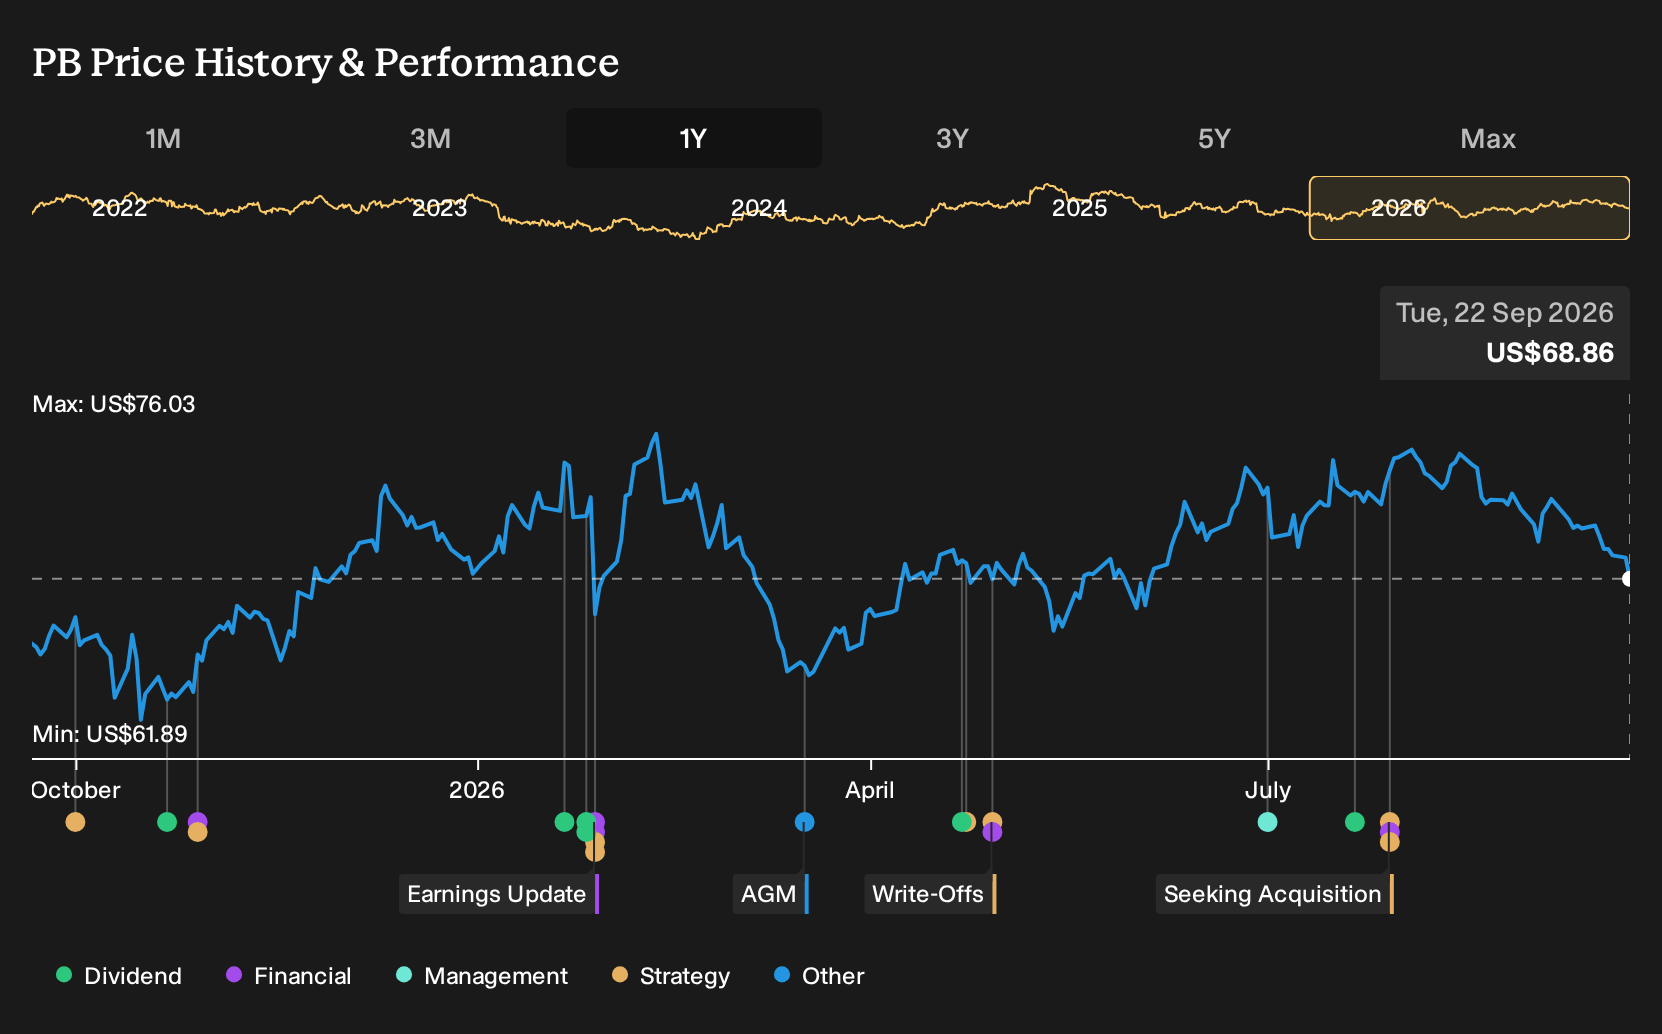
Prosperity Bancshares (PB)
Overview: Prosperity Bancshares runs Prosperity Bank, a Houston based regional lender with a deposit heavy, FDIC insured franchise funding loans and Treasuries.
Operations: Prosperity Bancshares generates about US$1.4b of banking revenue, almost entirely from traditional U.S. operations serving local businesses and households.
Market Cap: US$8.4b
Prosperity Bancshares fits the screener theme neatly, with a sizeable regional footprint, heavy reliance on core deposits, and meaningful securities holdings that tie directly into Fed liquidity plumbing. The dividend yield sits near 3.5%, and one unseen pressure on capital returns could reshape how investors think about those payout and growth ambitions.
Those payout ambitions and capital demands are already rubbing against each other, so pull up the 4 key rewards and 2 important warning signs to see what might be quietly reshaping Prosperity Bancshares.
Eagle Bancorp (EGBN)
Overview: Eagle Bancorp runs EagleBank, a Bethesda based regional bank that gathers deposits and lends to local businesses and households.
Operations: Eagle Bancorp generates about US$139 million of banking revenue, almost entirely from activities within the United States.
Market Cap: US$852 million
Eagle Bancorp sits right in the sweet spot of this screener theme, with a traditional deposit engine, a securities portfolio tied into Treasury market plumbing, and balance sheet moves that matter even more as the Fed makes the discount window easier to use for healthy lenders.
"Completion of the office credit cleanup, backed by independent portfolio validation and aggressive charge offs, positions the balance sheet for lower future provisions and a clearer path to growing earnings and book value."
What happens to margins and valuation now hinges on how one quiet shift in funding mix and liquidity access plays out from here.
That funding pivot is exactly where the story gets interesting, and the full narrative for Eagle Bancorp lays out how Eagle Bancorp’s cleanup, capital stack, and liquidity options could be quietly decoupling.

Bank of Marin Bancorp (BMRC)
Overview: Bank of Marin Bancorp is a Novato based regional bank that gathers deposits and lends to businesses and real estate clients.
Operations: Bank of Marin Bancorp generates about US$60 million of community banking revenue, entirely from customers in the United States.
Market Cap: US$449 million
Bank of Marin Bancorp fits this regional banks screen because its funding leans on insured deposits and securities. As a result, easier Fed backstops directly shape how comfortably it can support local borrowers when liquidity stress flares.
"Ongoing targeted investment in digital infrastructure and technology, including mobile banking and online lending upgrades, positions the bank to drive operational efficiency and improve customer engagement, which should support margin expansion and lower long-term costs."
What really moves the needle now is how one quiet shift in funding and collateral access ultimately flows through to those margins.
As that funding ripple spreads through returns, the full narrative for Bank of Marin Bancorp examines where Bank of Marin Bancorp’s digital spend may be masking risk or quietly accelerating profitability.

Seeking Fresh Alternatives Before They Fly?
New breakouts, fresh momentum, and under the radar stocks rarely stay overlooked for long. Spot ideas before the crowd, while the data still matters, and get in early.
- Hunt for smaller companies where profits are already driving momentum by scanning the curated 38 profitable AI stocks that aren't just burning cash before others get caught chasing stretched stories.
- Target resilient payouts that could steady your portfolio and consider the hand picked 7 dividend fortresses while those yields remain available and prices have not yet fully adjusted.
- Position ahead of potential demand shifts by reviewing the focused 35 best rare earth metal stocks before mainstream interest moves these producers further into the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com