
Should Talent Autopilot Launch Require Action From ZoomInfo Stock Investors?
- ZoomInfo Technologies recently launched Talent Autopilot, an AI-driven recruiting product that uses professional and company intelligence to surface candidates beyond traditional title or keyword searches and to support outreach through email integrations and applicant tracking system workflows.
- The product leans heavily on verified, explainable data at a time when 90% of employers in Aptitude Research’s survey require independently validated information from recruiting technology providers.
- We will now look at how ZoomInfo Technologies’ investment narrative lines up with the Talent Autopilot launch and its autonomous reasoning capabilities.
Scan how ZoomInfo Technologies fits into the broader AI hiring and automation story by comparing it with a curated group of 38 profitable AI stocks that aren't just burning cash that pair real businesses with real earnings.
ZoomInfo Technologies Investment Narrative Recap
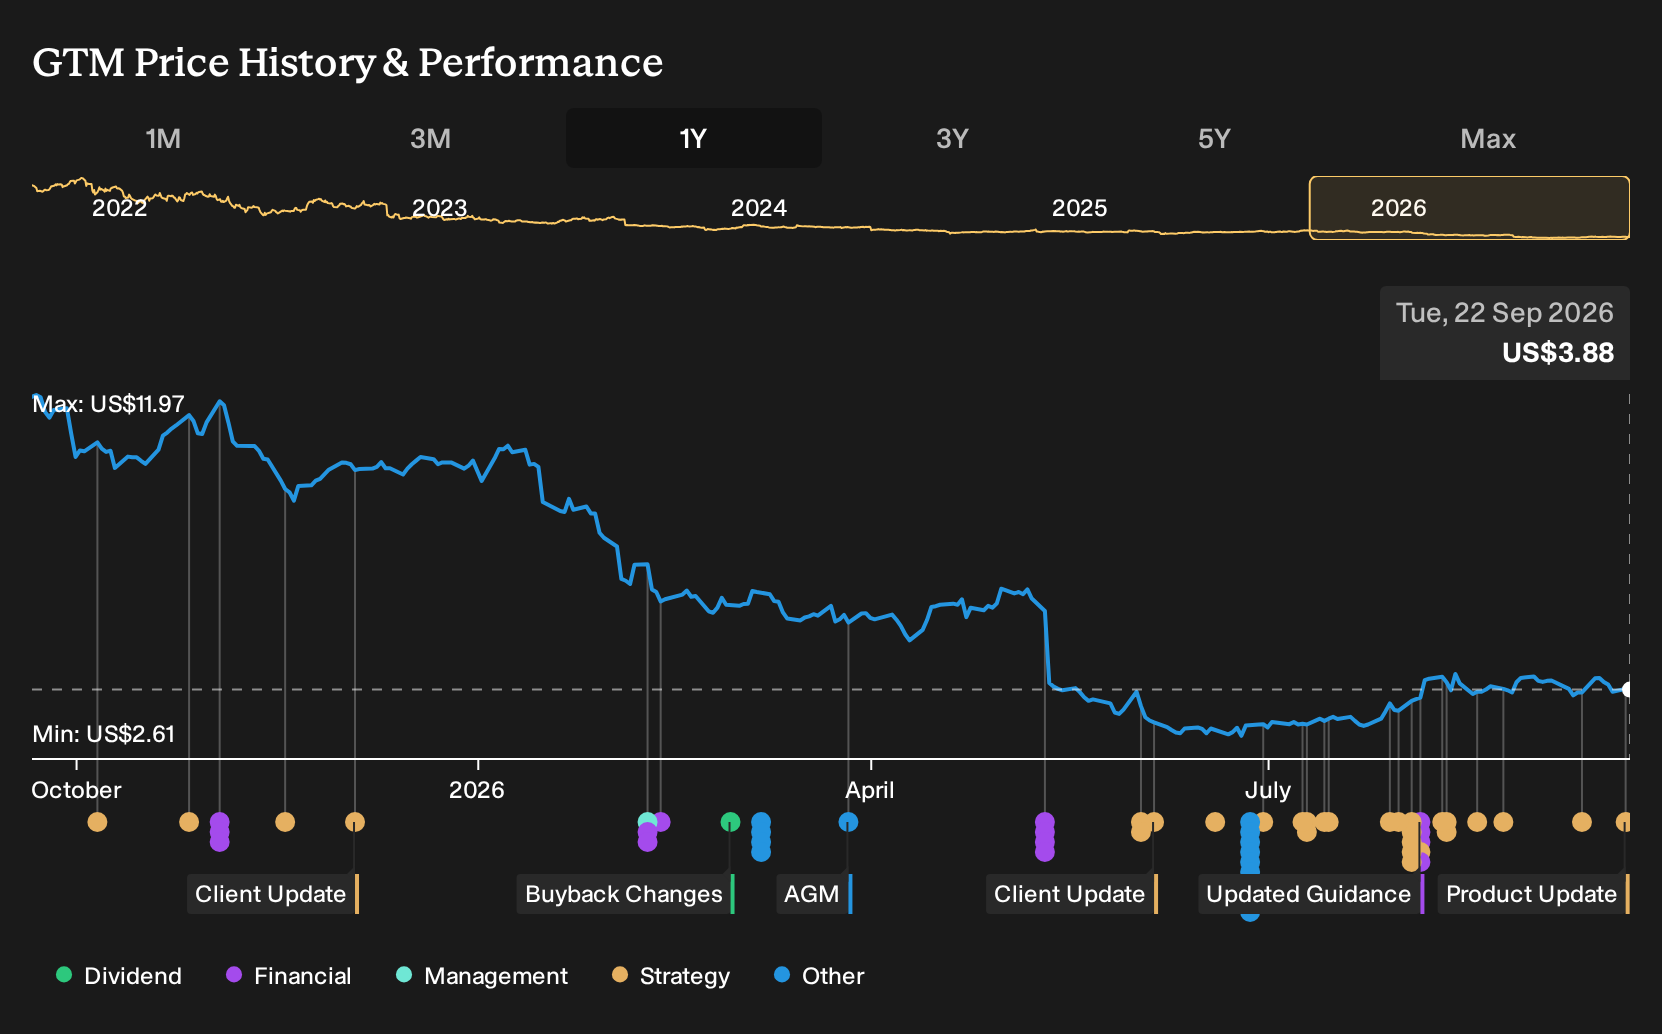
To own ZoomInfo Technologies, you need to believe its data graph and AI driven products can offset weak share price performance and revenue pressure. The main near term swing factor is whether new AI based offerings gain enough traction with large customers to support more stable demand while the downmarket segment remains under strain.
The Talent Autopilot launch fits squarely into that test. It deepens the ZoomInfo Technologies Talent product and leans on verified data, which matters as buyers scrutinize accuracy and explainability. The biggest near term risk still appears operational. Heavy debt, customer concentration upmarket, and ongoing data privacy scrutiny leave little room for execution missteps.
The Talent Autopilot announcement appears most relevant for investors watching AI as a catalyst. It extends ZoomInfo Technologies further into workflow level recruiting, not just lead lists, and directly addresses employer concerns about explainable, independently validated data. That aligns with the idea of ZoomInfo becoming an infrastructure layer for go to market and hiring decisions.
Impact depends on whether recruiters actually adopt it at scale and whether it helps defend pricing in a crowded AI hiring field. If uptake is modest, the product may be commercially minor and the key issues may stay the same. Those include reliance on third party data, regulation risk, and pressure in smaller customer cohorts even as AI offerings expand.
ZoomInfo Technologies' analyst narrative points to revenues of US$1.2b and earnings of US$391.8 million by 2029. This assumes revenue declines of 1.3% per year and an earnings swing of about US$932.8 million from a loss of US$541.0 million today to the 2029 consensus figure.
Uncover why ZoomInfo Technologies' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view treats ZoomInfo Technologies’ data moat itself as the big catalyst. The most optimistic analysts already modeled flat revenue at about US$1.2b and earnings of roughly US$320.1 million by 2029 before Talent Autopilot existed. You can read this as a bet that high quality, compliant data becomes even more valuable, and decide which side of that debate you fit on.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests potential upside of as much as 205% from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking For More ZoomInfo Technologies Style Investment Ideas?
If ZoomInfo Technologies has you thinking about where data, cash flow, and balance sheet strength intersect, it can help to line it up against other listed businesses using the Simply Wall St Screener.
- For investors who want quality and value working together, scan a curated 29 high quality undervalued stocks that combine stronger fundamentals with room for the market to reassess pricing.
- If capital preservation and steadier profiles matter most to you right now, focus on a 30 resilient stocks with low risk scores that score well on financial resilience and lower risk metrics.
- When you want to go beyond the usual tickers and hunt for less crowded ideas, filter through a 16 high quality undiscovered gems that already show solid underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com