
ID Logistics Group (ENXTPA:IDL) Stock May Trade At A Premium On Earnings
ID Logistics Group has seen its share price move around in recent years, which naturally raises a simple question for anyone looking at the stock today. Is the current valuation really supported by the earnings the business is generating?
- Over the past 3 years, ID Logistics Group has delivered a total return of 39.3%, which makes it important to check how much of that story comes from its underlying earnings power.
- The group relies on an asset light contract logistics model. Profitability, cash conversion, and the need for ongoing investment in warehouses and systems can all influence how comfortably earnings support the current share price.
- Your read on ID Logistics Group is one view; the desks covering it have another. See what analysts think ID Logistics Group's shares could be worth.
The issue now is whether the recent share price leaves ID Logistics Group trading at a level that its earnings can reasonably justify.
If you want a wider context for ID Logistics Group's earnings story, a focused stock screen built around solid balance sheet and fundamentals stocks screener (198 results) can be useful.
Does ID Logistics Group Look Pricey on Earnings?
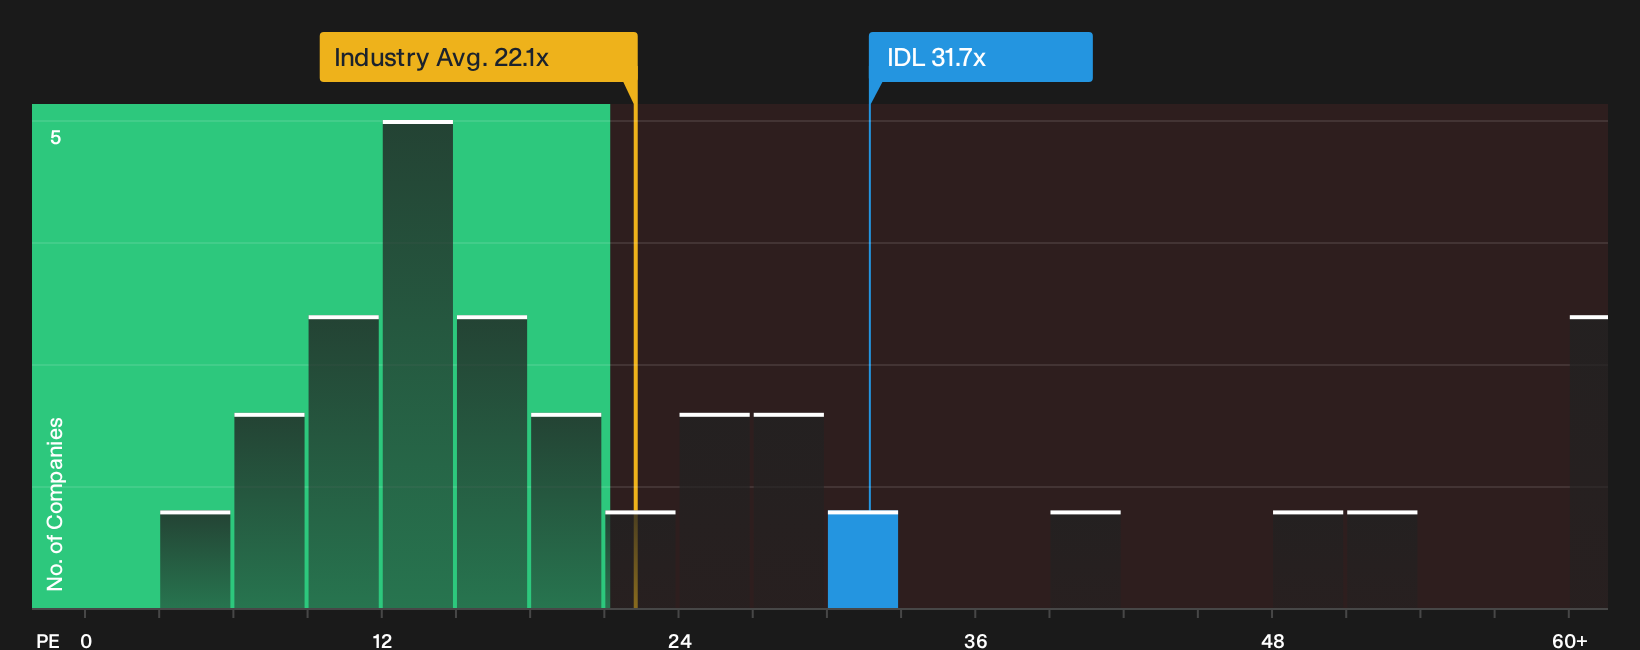
The P/E ratio suits ID Logistics Group because it highlights what investors are paying for each euro of current earnings in a relatively mature logistics business. Right now the stock trades on about 31.7x earnings, which is meaningfully higher than the Logistics sector average of roughly 15.1x and also above a peer group level of about 19.0x.
The fair P/E suggested by this model, which blends the company’s growth profile, profitability, size and risk into a single benchmark, sits below the current multiple. That gap points to ID Logistics Group screening as overvalued on earnings compared with what this framework would expect for a business with similar fundamentals. As a result, you would need to be comfortable paying a premium for its specific qualities to see the current valuation as appealing. Explore the numbers behind ID Logistics Group's P/E valuation.
The ID Logistics Group Narrative: What Would Justify Today's Price?
To make sense of why ID Logistics Group's current P/E looks rich or reasonable, Simply Wall St Narratives spell out the specific paths the future could take. Each one links a fair value estimate to a particular story about ID Logistics Group's potential drivers and pressure points, so you can track over time which version of events appears to be unfolding on the Community page.
A clear, number-driven narrative on ID Logistics Group helps you pin down what you are really assuming about its growth, margins and execution when you accept a P/E above sector and peer levels. Putting those expectations in writing makes it easier to test them against future results and adjust your view as new information comes through.
Share your own Narrative for ID Logistics Group and set out the assumptions behind your valuation.
One big question on ID Logistics Group still sits with who is steering it
The share price puts a clear number on expectations for ID Logistics Group, yet the real leverage point is who runs the operation and how their incentives are set up. See who runs ID Logistics Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com