
Dialysis Product Recalls Could Be A Game Changer For Fresenius Stock (XTRA:FRE)
- Fresenius SE KGaA, through Fresenius Medical Care Renal Therapies Group, has initiated two voluntary Class II recalls for hemodialysis products, including Citrasate Liquid Acid Concentrate and the 5008X HD/HDF Standard Blood Tubing Set, with worldwide distribution and ongoing corrective actions reported by the US Food and Drug Administration.
- The recalls highlight operational and quality control pressures within Fresenius Medical Care's dialysis consumables business, with potential implications for recall costs, customer relationships, and regulatory oversight across key markets where the group has a large chronic kidney care footprint.
- This article examines how Fresenius SE KGaA's investment narrative is affected by these dialysis product recalls and related quality concerns.
Fresenius SE KGaA Investment Narrative Recap
To hold Fresenius SE KGaA, you need to believe the hospital and chronic care platform can keep turning steady demand into disciplined earnings, even while working through product and cost pressures. The dialysis recalls sit against a group that is already dealing with wage and energy inflation, Chinese tender headwinds and a high debt load that limits room for error.
In the near term, the key catalyst is still cleaner execution on restructuring and portfolio focus, with investors watching for proof that margin gains in Kabi and Helios are repeatable. The biggest risk right now is quality or regulatory issues spilling over into pricing, recall expenses or more intense oversight. If that does not happen, the impact of these specific recalls may stay manageable.
The recall of the 5008X HD/HDF Standard Blood Tubing Set is the most relevant item for you here. It goes directly to Fresenius SE KGaA’s ability to run a high volume, high acuity consumables business without disruption. A Class II event with worldwide reach puts a spotlight on manufacturing controls and remediation speed as operational swing factors.
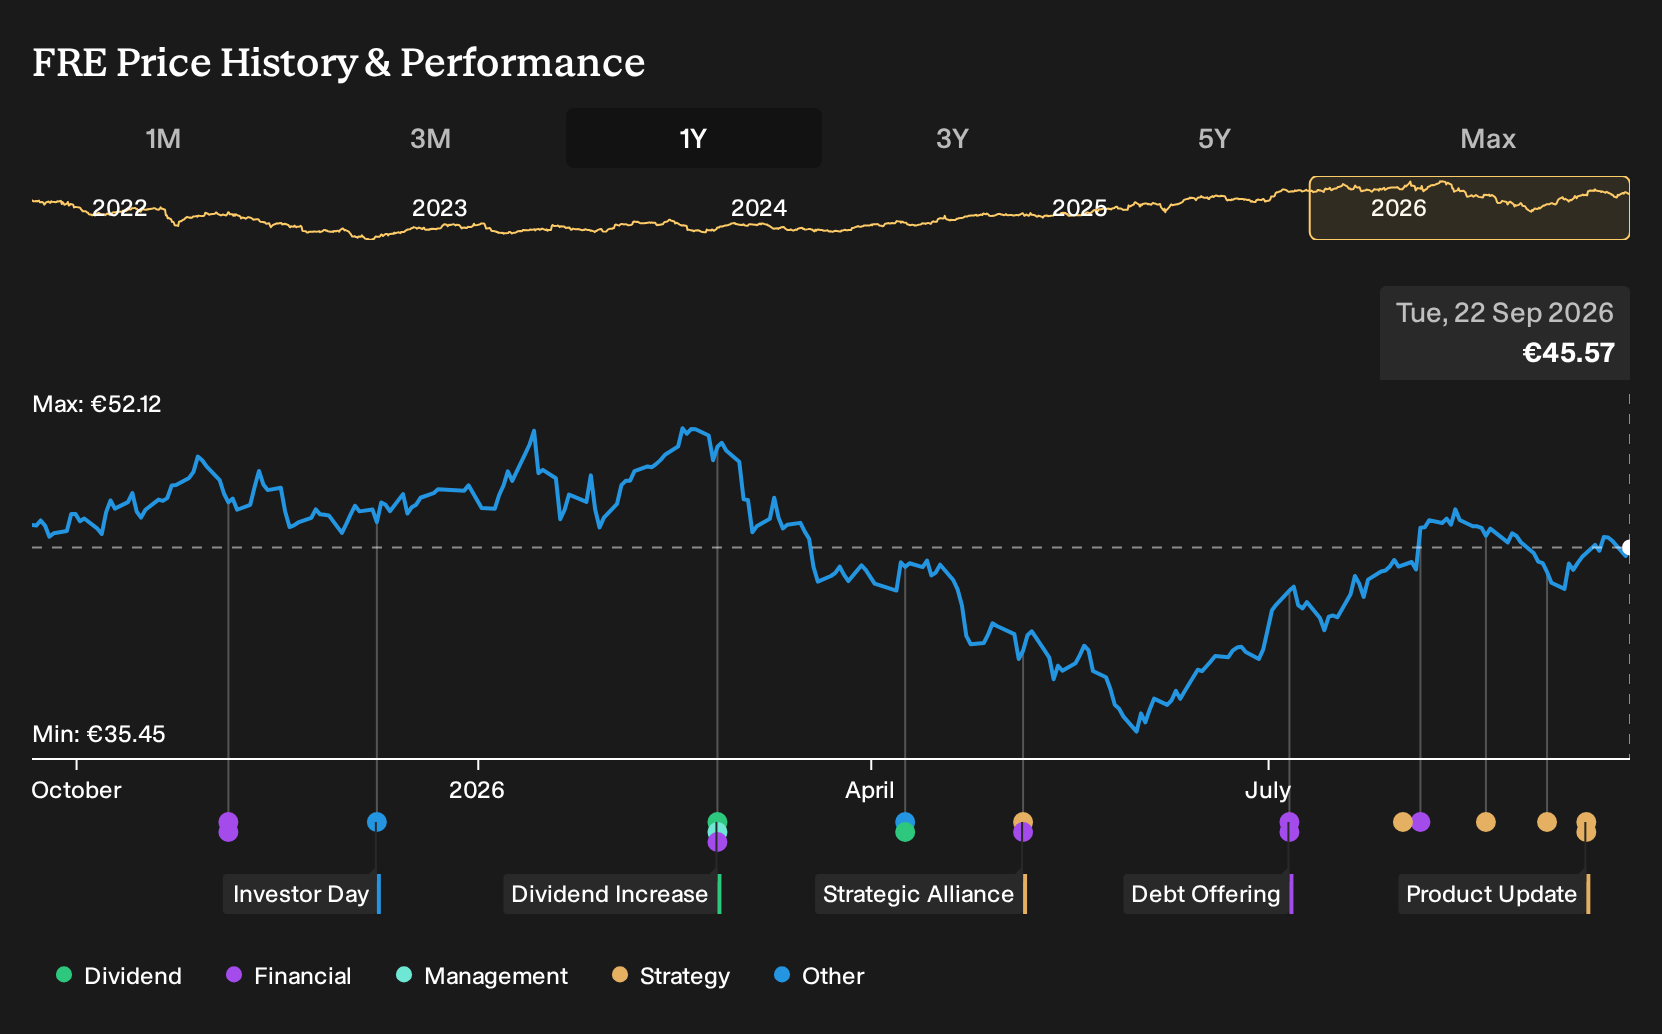
How management addresses this while presenting at the Berenberg and Goldman Sachs German Corporate Conference on 22 September 2026 matters. Investors will be listening for detail on recall costs, product availability and any knock on effects for the broader renal portfolio. That sits alongside existing catalysts around portfolio optimisation, digital health rollout and biosimilar expansion, which still frame the medium term story if execution holds up.
Fresenius SE KGaA’s current analyst narrative points to revenues of €26.4b and earnings of €2.4b by 2029, based on assumed yearly revenue growth of 4.7% and an earnings increase of about €0.9b from €1.5b today.
Uncover why Fresenius SE KGaA's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Simply Wall St Community members have only two fair value estimates for Fresenius SE KGaA, stretching from €54.79 to €143.97 per share, so opinions already span a wide band. Those views were set before the current dialysis recalls and the 22 September 2026 conference, which could reshape how you and other investors judge execution risk and upside.
Explore another Fresenius SE KGaA fair value estimate, including one that suggests up to 216% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Fresenius SE KGaA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fresenius SE KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fresenius SE KGaA's overall financial health at a glance.
Looking for more investment ideas beyond Fresenius SE KGaA?
If these dialysis recalls have sharpened your focus on risk, it can help to widen the lens and compare Fresenius SE KGaA with other businesses that better align with your comfort on balance sheet strength, income needs, or downside protection.
- If capital protection is top of mind, start with companies that currently screen as having sturdier risk profiles by reviewing the 230 resilient stocks with low risk scores.
- If dependable income matters more to you, focus on businesses that offer higher yields and more established payouts through the 159 dividend fortresses.
- If you want to hunt for quality outside the usual crowd, scan financially robust but less followed opportunities using the 617 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com