
ArcelorMittal (ENXTAM:MT) Hit By Ukraine Missile Strike, Is It Still Below Fair Value?
ArcelorMittal (ENXTAM:MT) is back in focus after its Kryvyi Rih complex in Ukraine was hit by another ballistic missile, leaving two contractors dead, employees injured, and primary steel production halted.
Despite the fresh disruption at Kryvyi Rih, ArcelorMittal’s share price has delivered a 17.71% 90 day return and a 60.11% year to date share price return. The 1 year total shareholder return of 111.50% points to strong momentum that markets may now be reassessing against elevated operational risk.
Scan beyond ArcelorMittal and compare how other materials producers handle operational shocks with a curated set of list of solid balance sheet and fundamentals (198 results).
ArcelorMittal’s share price has sprinted ahead of its recent shocks, yet still trades below both analyst targets and some intrinsic estimates. Where does a fair entry point really fall in that gap?
Most Popular Narrative: 4.2% Undervalued
ArcelorMittal’s most followed narrative puts fair value at €66.61, a touch above the latest €63.82 close. This pushes the discussion toward whether recent operational hits are fully reflected in the price.
Strategic decarbonization projects and investments in green steel are positioning the company to benefit from premium demand and expanding margins. Expansion in high-growth regions and asset optimization, including divestments and acquisitions, are driving improved profitability and earnings per share.
See why 26 investors see ArcelorMittal as 4% undervalued.
Result: Fair Value of €66.61 (UNDERVALUED)
Still, that story frays quickly if trade barriers stay unpredictable, or if green transition spending and project delays keep squeezing cash flows and returns.
Find out about the key risks to this ArcelorMittal narrative.
Another View: ArcelorMittal Through The Earnings Lens
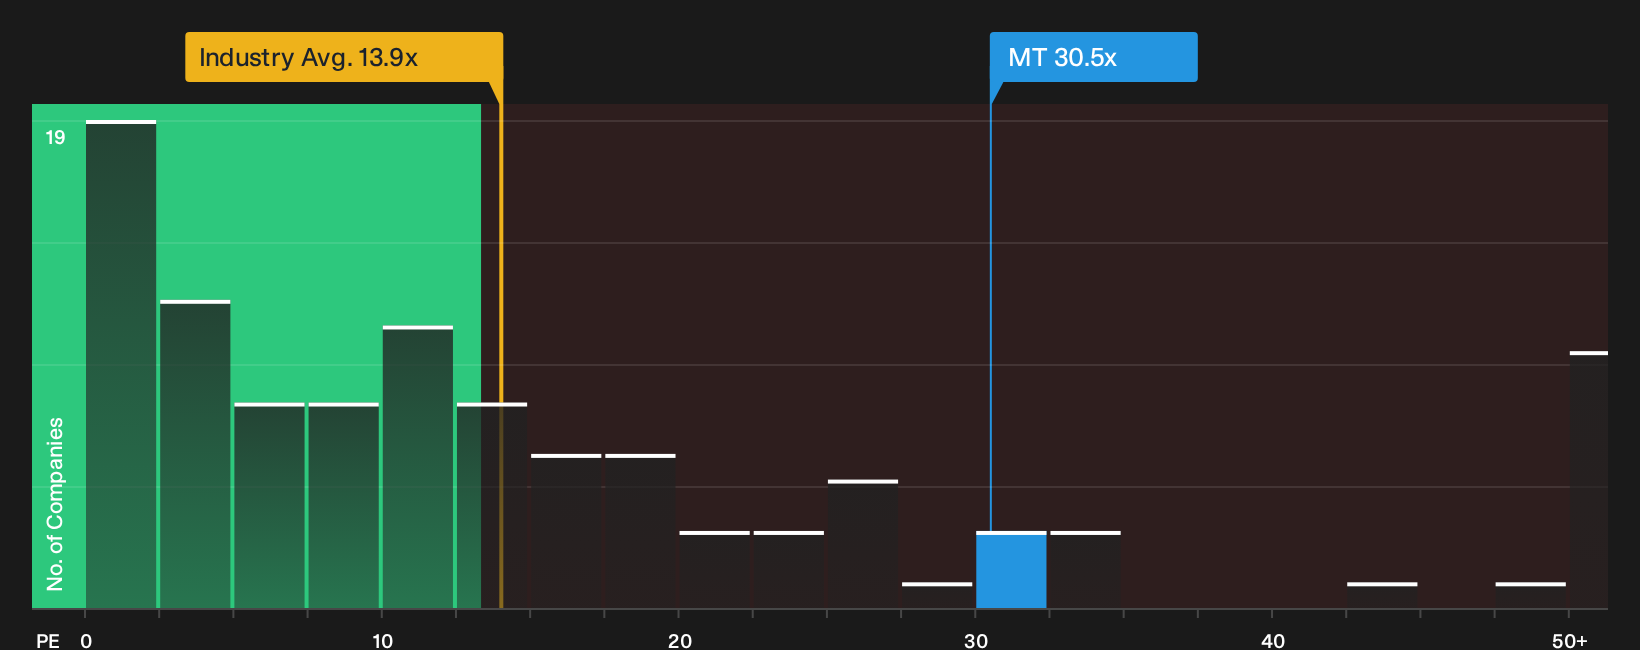
On price targets and fair value estimates, ArcelorMittal screens as 4.2% undervalued. On plain earnings multiples, the story gets trickier. The stock trades on a P/E of 30.4x, which is more than double the European metals and mining group at 13.9x, and above peer average at 33.6x, while the fair ratio sits even higher at 35.5x.
That gap suggests the current tag already bakes in a lot of optimism, yet still leaves room for the market to move toward the fair ratio if earnings keep tracking forecasts. The question for you is simple: does that premium feel like sensible compensation for the risks around tariffs, project delays, and green capex, or like thin ice?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around ArcelorMittal feels mixed to you, that is the point. Act while the data is fresh and test the numbers yourself. Then weigh those findings against the 2 key rewards
Looking for more investment ideas beyond ArcelorMittal?
Do not let your research stop with ArcelorMittal. Use fresh ideas from curated screeners to spot other opportunities that fit your risk tolerance and return goals.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (198 results) that can better absorb shocks and keep funding future plans.
- Hunt for mispriced opportunities through a 171 high quality undervalued stocks that highlights strong fundamentals where the share price has not fully caught up.
- Prioritise stability and potential income using a 159 dividend fortresses focused on companies offering higher yields with robust financial backing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com