
Global Partners (GLP) Cools After Recent Pullback, Is The Stock Still Cheap?
Global Partners (GLP) has drawn fresh attention after recent performance data showed mixed trends, with the stock down over the past week and month, yet still positive over the past 3 months and year to date.
Recent trading has cooled, with the share price down 2.7% over the past day and 3.2% over the week. However, Global Partners still shows double digit 3 month share price momentum and a strong 5 year total shareholder return of 243.2%, suggesting that long term holders have been rewarded even as near term sentiment softens.
Compare Global Partners' mixed recent returns with a curated group of resilient businesses using the 30 resilient stocks with low risk scores to see how other lower risk stocks have held up.
The recent pullback in Global Partners could point to investors cooling on sentiment, even as the underlying fuel distribution, retail and logistics operation keeps grinding on. Is the current price reflecting that business reality, or just mood swings in the market?
Most Popular Narrative: 8% Overvalued
Analysts following Global Partners see a fair value of $45.50 against a last close of $49.25, so the prevailing narrative prices the units as modestly overvalued while still assuming the fuel distributor can keep putting its asset base to work.
Expansion of the company's terminal network through recent acquisitions in key markets is expected to strengthen market presence, enhance distribution efficiency, and drive long-term revenue growth from higher throughput volumes and improved operating leverage.
See why 4 investors see Global Partners as 8% overvalued.
Result: Fair Value of $45.50 (OVERVALUED)
Still, the Global Partners story can change quickly if fuel demand weakens faster than expected or if heavier regulation squeezes profitability in core distribution activities.
Find out about the key risks to this Global Partners narrative.
Another View on Global Partners’ Valuation
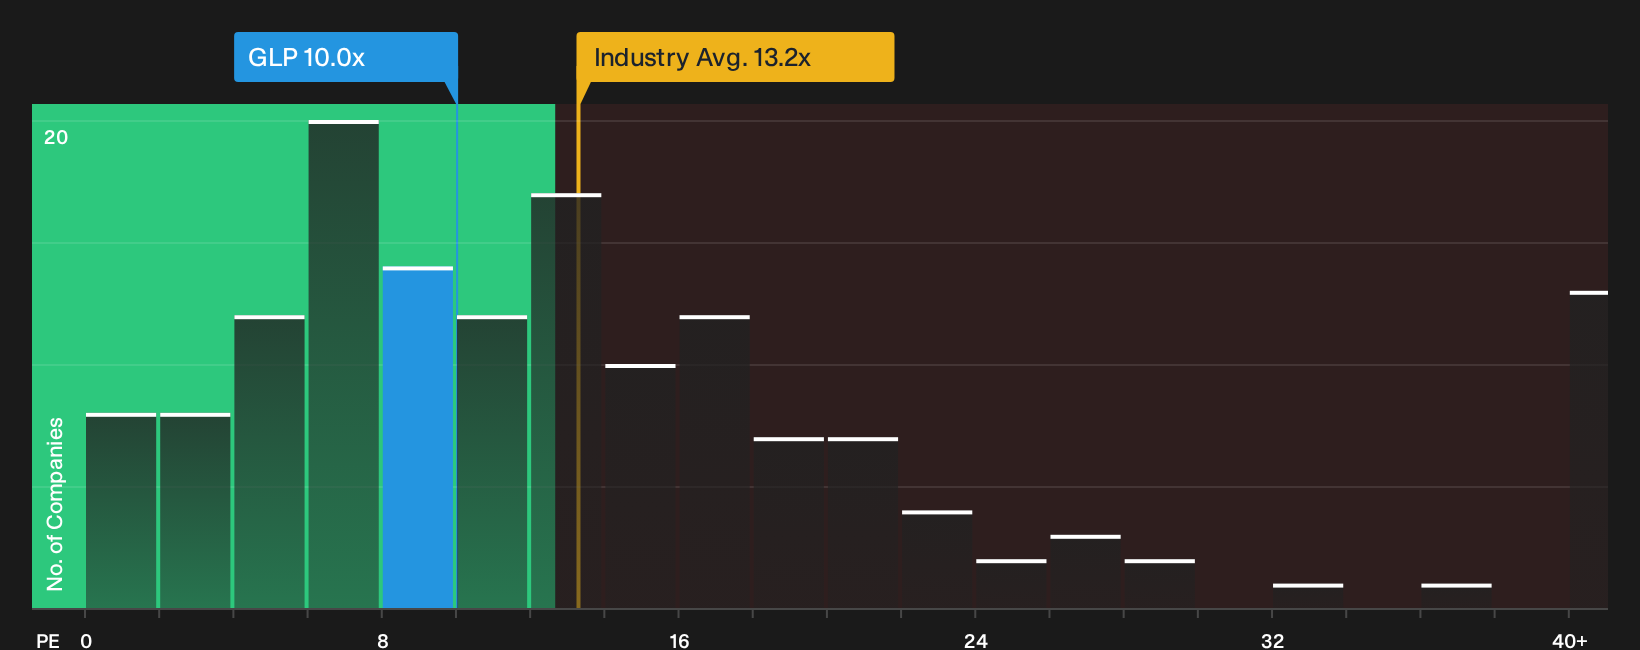
Global Partners looks slightly rich against the $45.50 fair value from the narrative, yet on simple P/E math it points the other way. The units trade at about 10x earnings compared with a fair ratio of 12.1x, the US Oil and Gas group at 13.2x, and peers near 14.9x.
That gap signals the market is assigning a discount rather than a premium. This could reflect concern about debt levels, earnings forecasts or sector risk more than the raw numbers alone. The question for investors is whether that discount is a sensible safety buffer or an overreaction to concerns that may already be priced in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Global Partners so far. If you want to move quickly and form your own view based on the underlying data, review the 4 key rewards and 3 important warning signs to weigh the potential risks and rewards.
Looking for more ideas beyond Global Partners?
If Global Partners has your attention, do not stop here. Fresh opportunities often sit just outside your current watchlist, and delaying that search can mean missing the next move.
- Target potential mispricings by scanning a curated pool of resilient businesses through the 29 high quality undervalued stocks.
- Strengthen your portfolio foundation by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding pressures.
- Hunt for overlooked potential in a 16 high quality undiscovered gems that the broader market has not yet fully focused on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com