
SSY Group (SEHK:2005) Faces A Valuation Test Following Two China Drug Approvals
SSY Group (SEHK:2005) just secured Chinese regulator approval for Ziprasidone Mesilate as a bulk drug and Letermovir Injection, expanding its antipsychotic HPAPI lineup and perioperative injectable portfolio.
SSY Group’s recent regulatory wins arrive as short term momentum picks up, with a 30 day share price return of 11.92% and a 90 day gain of 25.34%. This comes even though the year to date share price return is down 3.15% and the 3 year total shareholder return has declined 31.14%.
Look beyond SSY Group and compare its recent pipeline traction with hand picked 619 high quality undiscovered gems in healthcare and related sectors that may not be on every investor’s radar yet.
SSY Group has rallied hard on fresh drug approvals while longer term returns still look weak. The real issue now is whether the current price still rewards new risk or mainly suits investors already on board.
Price-to-Earnings of 15.8x for SSY Group: Is it justified?
On simple earnings terms, SSY Group is being valued at a P/E of 15.8x, which prices the HK$2.77 share price above several reference points in its own data set and against peers.
The P/E ratio links the current market value of the stock to its earnings per share. For SSY Group it reflects what investors are currently willing to pay for each unit of profit in a pharmaceuticals business with HK$4,378.857m of revenue and HK$507.453m of net income.
That earnings multiple runs higher than both the Hong Kong Pharmaceuticals industry average of 14x and the peer average of 11.3x. It also sits above an estimated fair P/E of 15.2x, which together indicate that the market is paying a richer price for this profit stream than those benchmarks and could compress if sentiment or expectations cool.
Explore the SWS fair ratio for SSY Group.
Result: Price-to-Earnings of 15.8x (OVERVALUED)
Still, SSY Group faces real pressure if drug pricing tightens or if its recent revenue and net income growth rates of 9.42% and 15.71% do not continue.
Find out about the key risks to this SSY Group narrative.
Another View on SSY Group’s Value
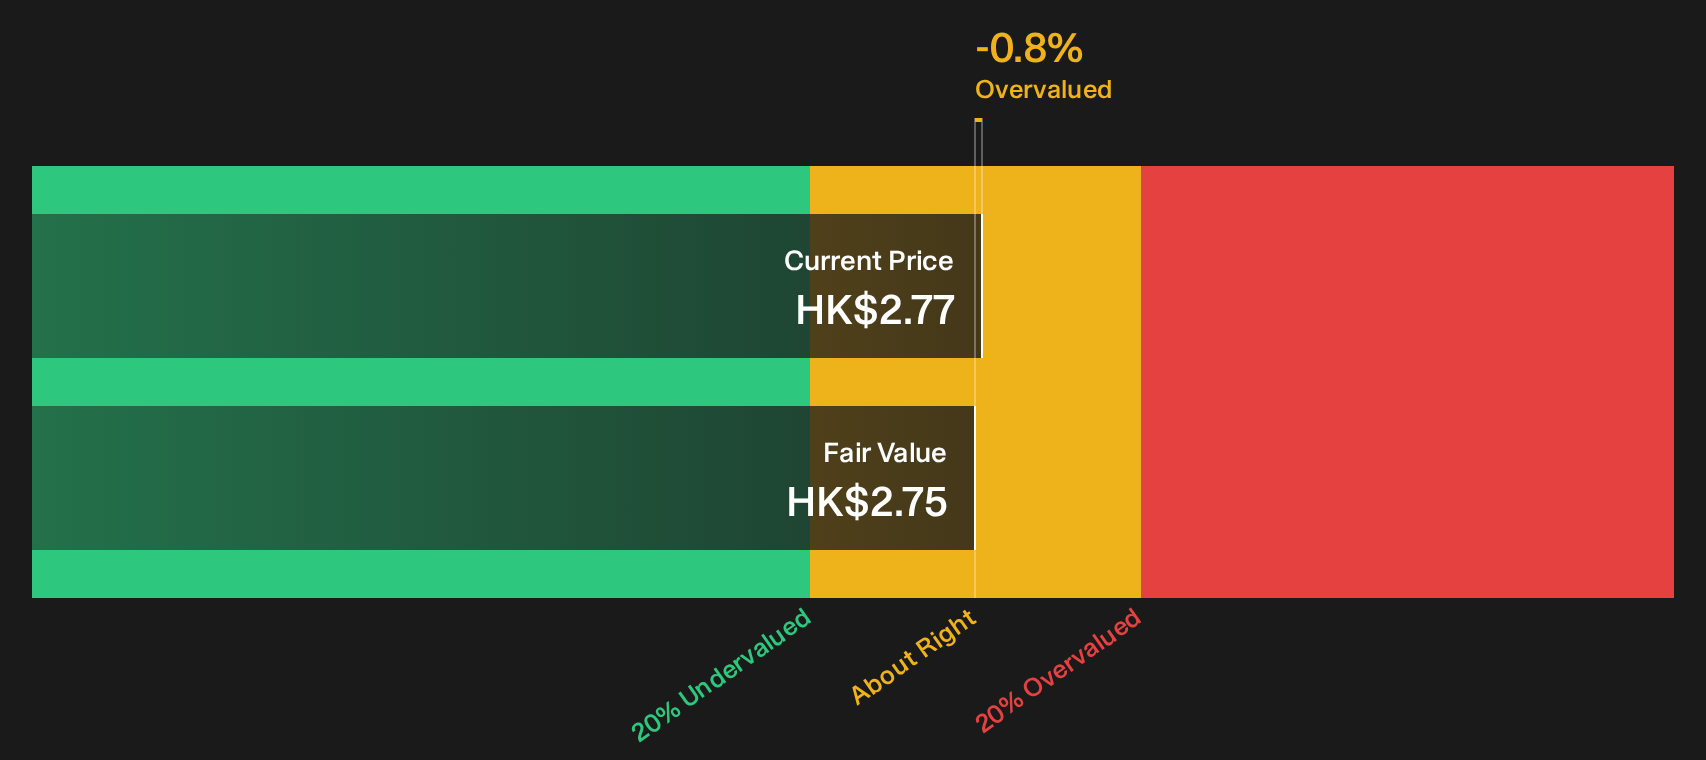
Price looks rich on earnings, yet the SWS DCF model paints a slightly different picture. At HK$2.77, SSY Group trades just above an estimated future cash flow value of HK$2.75, which implies only a narrow premium and limited margin for error if the story changes.
That tiny gap leaves little room if cash flows disappoint, but it also means the stock is not wildly out of line with what the model suggests. The question for you is simple: Are those projected cash flows resilient enough to justify paying this close to modelled value?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SSY Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 171 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this all sounds finely balanced around SSY Group, you may want to act quickly and review the underlying data yourself so your conclusion matches your own risk tolerance. Then review the potential upside signals in the 1 key reward.
Looking for more SSY Group sized opportunities?
Do not stop your work with SSY Group alone. Cast the net wider now and you will not miss potential ideas sitting in plain sight.
- Target potential mispricing by scanning a curated pool of financially solid stocks through the 171 high quality undervalued stocks.
- Strengthen capital preservation by focusing on businesses with cleaner finances and robust fundamentals using the list of solid balance sheet and fundamentals (198 results).
- Reduce stress around volatility by concentrating on companies that carry lower overall risk scores with the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com