
3 European Industrial Stocks Tied To The Defence Shift In Auto Plants
European automakers are starting to turn idle car plants toward defence work, and that shift is quietly rewriting the story for a handful of suppliers. If underused factories find new life in military contracts, some stocks could gain fresh revenue streams while others remain stuck with stranded capacity. This article unpacks that tension and walks through 3 European industrial stocks exposed to this defence pivot and what that might mean for your portfolio.
The three stocks in this article are only a small sample, and the full screen surfaced 34 more European auto and industrial players with equally compelling defence repurposing stories that are not covered here. To identify potential leaders in this capacity pivot, head straight into the European Auto Capacity Repurposing Plays screener to filter, analyze and focus on the highest conviction opportunities.
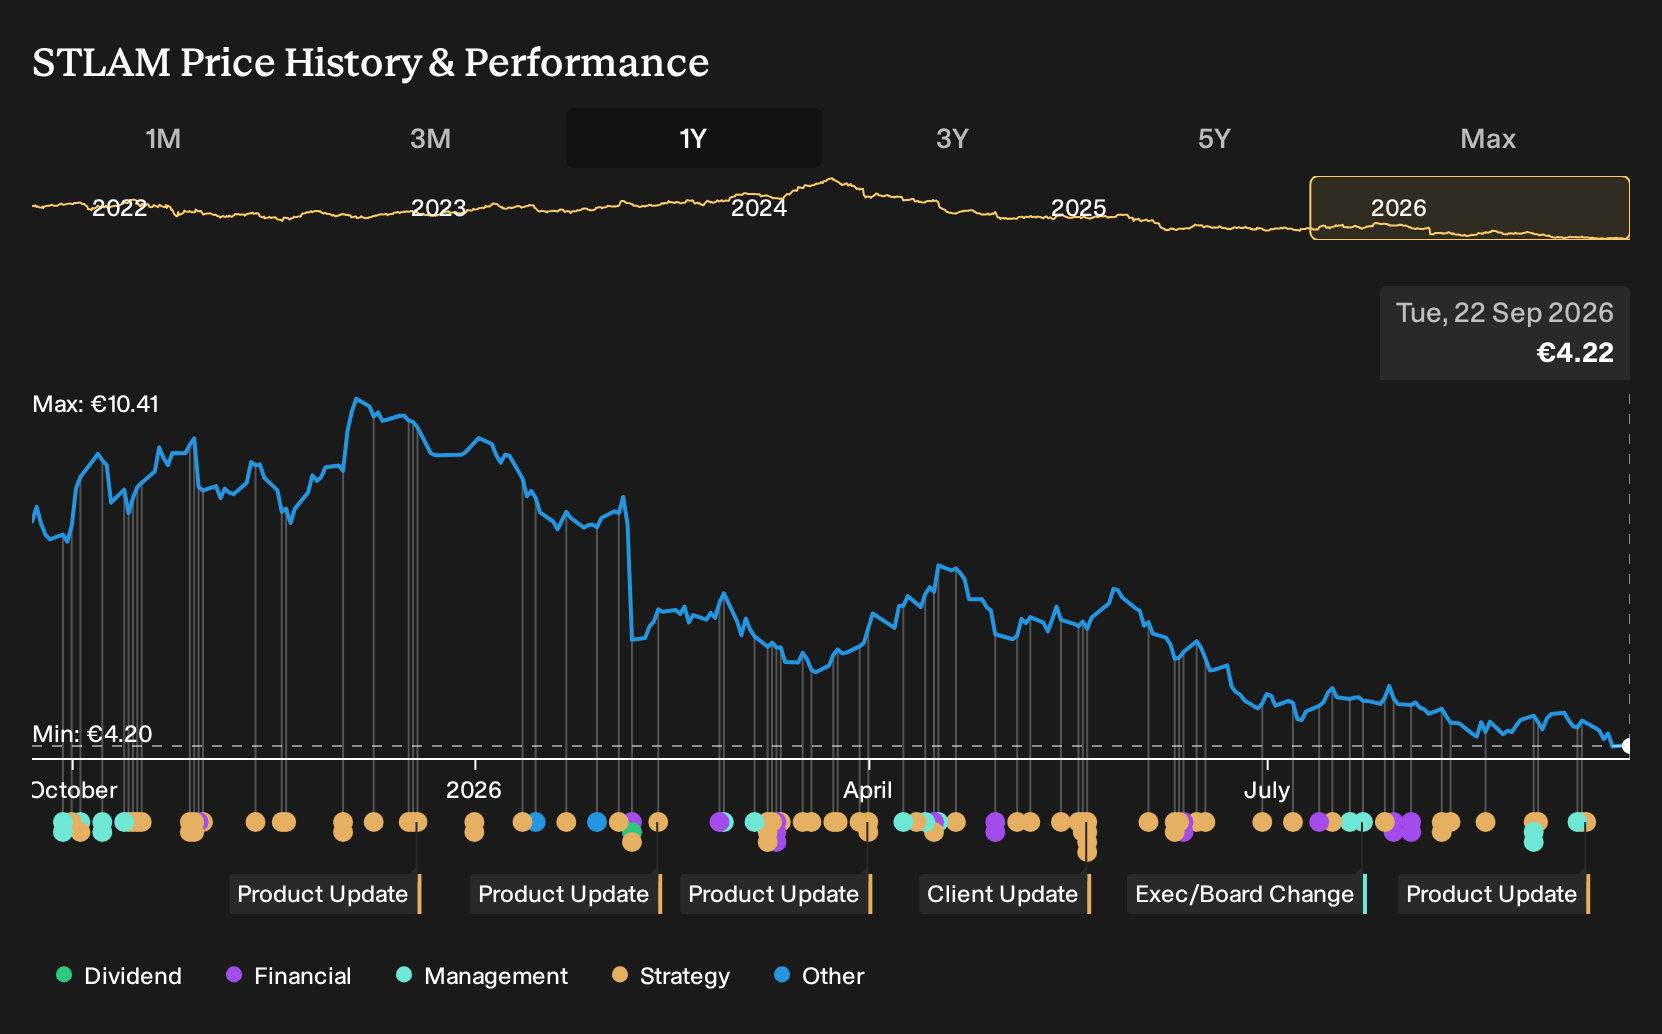
Stellantis (BIT:STLAM)
Overview: Stellantis is a global automaker that designs, builds and sells passenger and commercial vehicles, parts and mobility services across multiple brands.
Operations: Stellantis generates most of its revenue in North America at €66.97b and in Enlarged Europe at €58.02b, with additional contributions from South America and other regions.
Market Cap: €12.23b
For the European Auto Capacity Repurposing Plays theme, Stellantis matters because its vast underused factories can host new defence and industrial work if contracts line up.
"I care about the capital decision itself. Billions of euros were still being treated as excess capital while the North American business was deteriorating badly enough to force a major reset."
What happens to future margins and cash generation now depends heavily on how one underappreciated pressure on this capacity pivot is resolved.
That turning point is exactly what the full narrative for Stellantis unpacks, showing how capital choices, brand mix and factory flexibility could reshape the Stellantis equity story.
EDAG Engineering Group (XTRA:ED4)
Overview: EDAG Engineering Group designs vehicles, electronics and entire production facilities for global auto, commercial, defence and industrial clients.
Operations: EDAG Engineering Group generates most of its revenue in Vehicle Engineering at €408 million, with €194 million from Electrics/Electronics and €94 million from Production Solutions.
Market Cap: €114 million
EDAG Engineering Group sits at the junction of idle auto plants and new defence work, because it designs both vehicles and the production lines that build them. The stock links directly to this screener theme. It remains loss making and dependent on higher risk funding, so much of the potential now depends on how one quiet shift in contract mix plays out.
That quiet contract shift is exactly what the 2 key rewards and 1 important major warning sign lays out, highlighting where EDAG Engineering Group could convert fragile funding into durable defence cash flows.

DEUTZ (XTRA:DEZ)
Overview: DEUTZ develops, manufactures and services diesel, gas, hybrid and hydrogen engines plus related power systems for off highway, industrial and defence equipment worldwide.
Operations: Revenue is concentrated in the Americas at €591 million and China at €141 million, with a €1.42b segment adjustment reported.
Market Cap: €1.84b
DEUTZ matters for this capacity repurposing screen because its engine plants already supply off highway machinery and defence vehicles. Any shift in European auto demand can steer idle expertise toward higher value powertrain programs instead of leaving equipment underused.
"The company's accelerating transformation from an engine pure play to a diversified solutions provider, especially via strategic M&A in electrification, energy systems, and defense, positions it to benefit from the global shift toward decarbonization and rising demand for low-emission/hybrid powertrains, supporting long-term revenue growth and improved operating scale."
What really moves the dial from here is how one quiet change in program mix filters through to pricing power and engine margins.
That shift in program mix is exactly what the full narrative for DEUTZ unpacks, showing where DEUTZ could see accelerating pricing power, capital discipline, and defence exposure pulling apart.

Seeking Fresh Alternatives Beyond Autos
Fresh breakouts rarely stay under the radar for long. Screens move fast, and the cleanest setups get caught early. Scan these ideas while it matters and consider them promptly.
- Spot cash generative balance sheets before momentum starts moving by scanning the curated list of solid balance sheet and fundamentals (198 results) that filters out fragile stories.
- Look for accelerating income streams by reviewing the hand picked 160 dividend fortresses built to surface companies aiming to sustain payouts while prices are still dropping or flat.
- Track early infrastructure beneficiaries of AI capacity build outs by exploring the focused 86 AI infrastructure stocks before the crowd starts following the same tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com