
Ampol (ASX:ALD) Expansion Story Keeps Valuation Questions In Play
Ampol (ASX:ALD) has drawn fresh attention after its recent share price move, with the stock last closing at A$44.84. Investors are weighing this against the business’s current earnings, returns and value profile.
The recent 2.37% one day share price return and 12.52% 30 day share price return suggest interest in Ampol is building, while the 39.60% year to date share price return sits alongside a 61.22% one year total shareholder return that reflects both price and dividend contributions.
Scan how Ampol’s recent run compares with other companies showing strong momentum and solid fundamentals by reviewing the hand picked 5 high quality undervalued stocks.
Ampol’s rapid share price climb and sizeable recent shareholder returns raise a simple issue for anyone eyeing the stock today. Does the current valuation still leave enough upside to justify the risk from here?
Most Popular Narrative: 5% Overvalued
The most followed narrative on Ampol currently points to a fair value of about A$42.78 per share, which sits modestly below the last close at A$44.84. That gap puts the recent share price surge in context and frames the debate around how durable today’s earnings power and cash generation really are.
The acquisition of EG Australia and previous Z Energy acquisition are set to significantly expand Ampol's fuel and convenience network in the Asia-Pacific region. This directly leverages population growth, urbanisation, and rising regional transport/energy demand, which is expected to drive robust volume growth and future revenue.
Accelerating rollout of EV charging infrastructure and initiatives in alternative fuels (for example, renewable diesel, SAF, hydrogen pre-FEED studies) positions Ampol to capture new revenue streams from evolving customer demand and energy transition. This is expected to support longer-term revenue and diversified earnings growth.
See why 49 investors see Ampol as 5% overvalued.
Result: Fair Value of A$42.78 (OVERVALUED)
Still, the narrative around Ampol could shift if the long term decline in core fuel volumes deepens, or if high refinery capex starts to squeeze free cash flow.
Find out about the key risks to this Ampol narrative.
Another View On Ampol’s Valuation
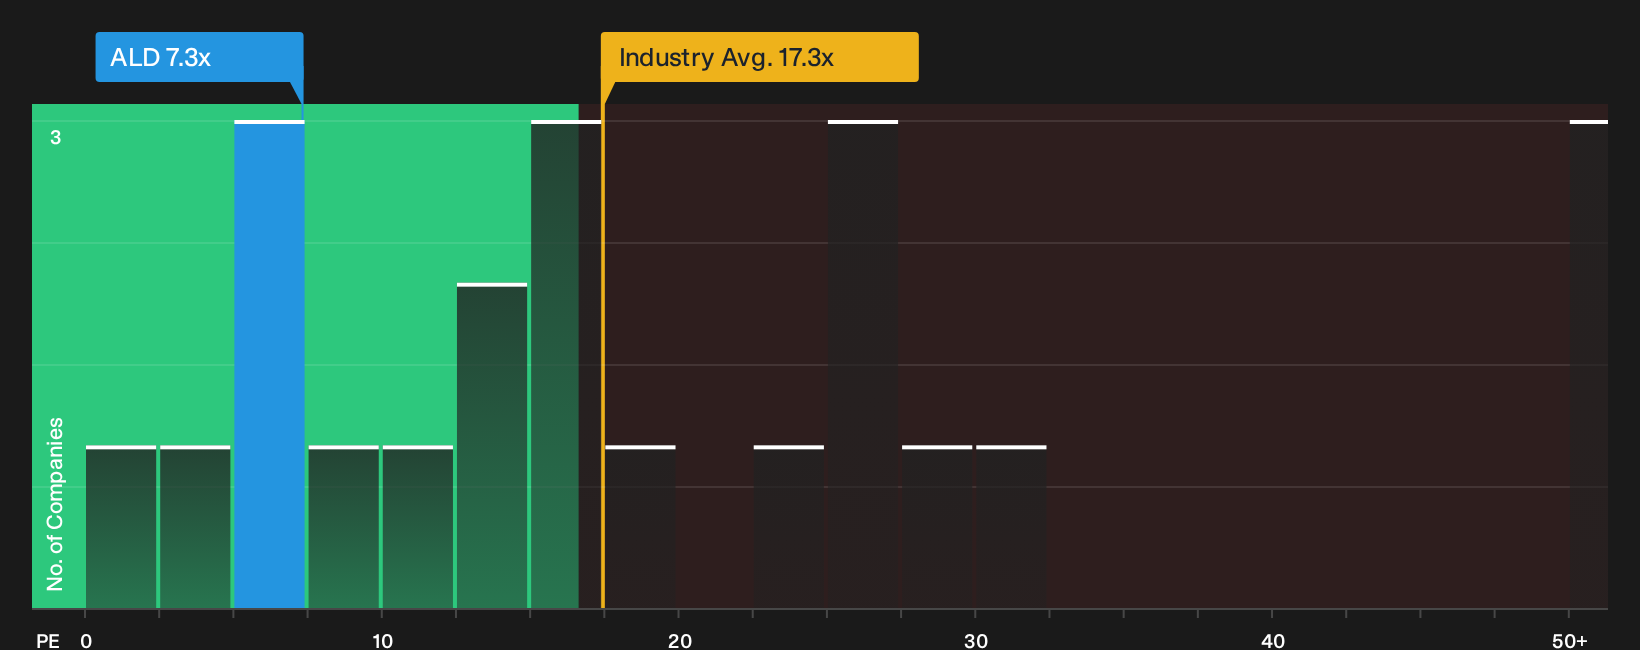
Multiples tell a very different story for Ampol. The stock trades on a P/E of 7.3x, which is far below the Australian Oil and Gas industry at 17.3x and peers at 24.3x, yet still a touch above a fair ratio of 6.9x that the market could move toward. Is this a margin of safety or a value trap in the making?
To see how the current price compares with what the numbers imply, including how that fair ratio is calculated, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Ampol leave you undecided, treat that as your cue to pressure test the numbers yourself and move quickly while sentiment is still forming. To see how those mixed views translate into concrete pros and cons, review the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Ampol?
Do not stop at Ampol if you want a fuller opportunity set. Broaden your watchlist now while valuations, balance sheets and dividends still look compelling across the market.
- Target income resilience by reviewing companies in the 3 dividend fortresses that focus on higher yields backed by meaningful cash generation.
- Hunt for quieter quality by scanning the 16 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- Dial down risk by checking the 7 resilient stocks with low risk scores that screens for resilience scores designed to help protect your downside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com