
K92 Mining (TSX:KNT) Stock May Be Below Fair Value On Earnings
K92 Mining has delivered a powerful run in recent years, and the share price now embeds a clear story about what its earnings can support. The question for anyone looking at the stock today is whether that earnings profile really lines up with where the market now values the business.
- The share price has returned 414.2% over the past 3 years, which puts a lot of weight on whether the current earnings base can justify that kind of re-rating.
- The mining operation depends heavily on how efficiently it can turn ore into profit, so future capital spending and operating costs may play a big role in how sustainable its earnings power proves to be.
- There is a second opinion on K92 Mining worth weighing. See what analysts think K92 Mining's shares could be worth.
The stock's next move may depend on whether K92 Mining's current earnings are strong and reliable enough to back up today's share price.
If you want more ways to pressure test K92 Mining against other opportunities, a focused screen built around 36 elite gold producer stocks can be a helpful next step in your research.
Is K92 Mining Still Cheap on Earnings?
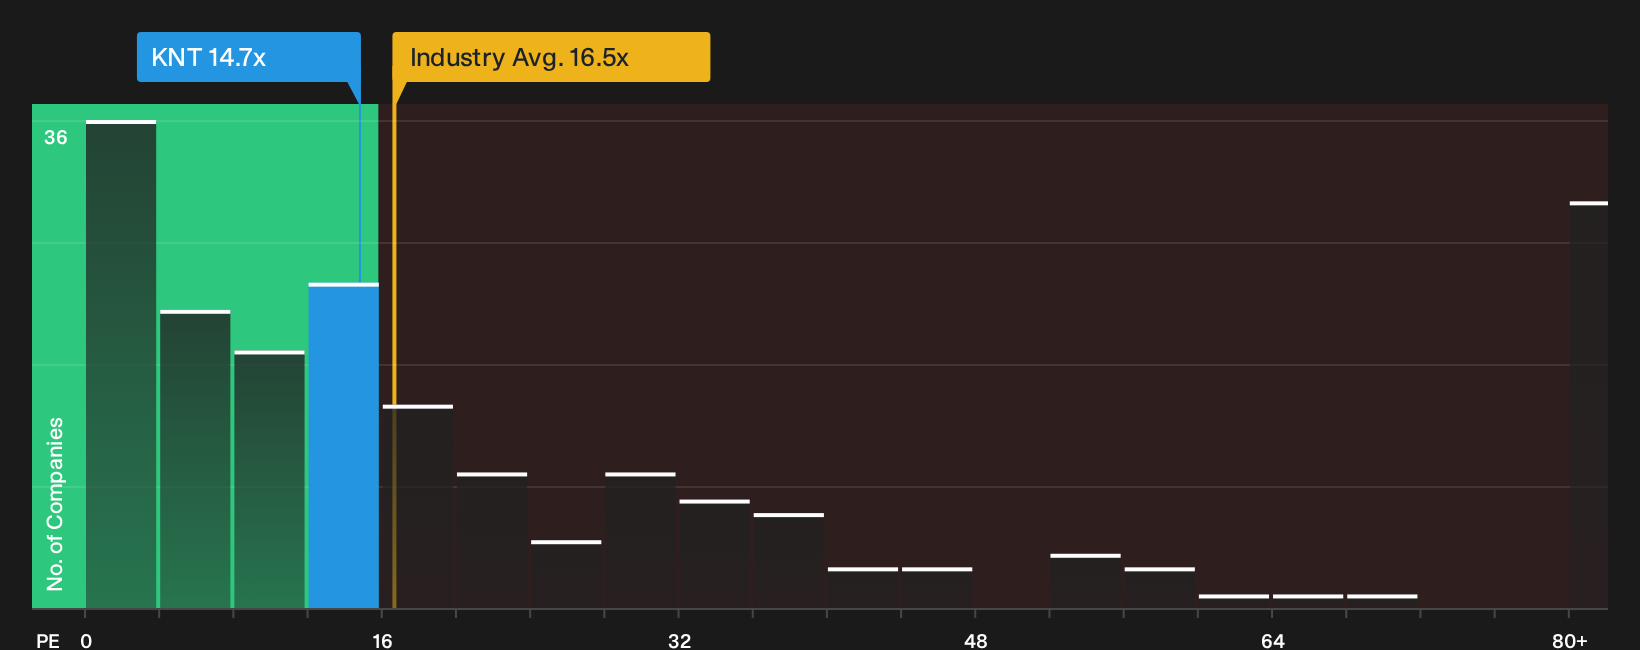
The P/E ratio suits K92 Mining because earnings are a direct output of how effectively its mine turns ore into profit. From this perspective, the stock trades on a P/E of about 14.7x, compared with roughly 16.5x for the wider Metals and Mining group and about 12.9x across peers. That means the market is paying a slightly lower price for each dollar of K92 Mining earnings than the broader sector, but a bit more than for similar companies in the peer set.
The fair multiple that would be expected given K92 Mining's growth profile, profitability, size and risk sits above the current 14.7x level, which, on this framework, suggests the shares may screen as undervalued. For a reader weighing the stock today, the key analytical point is whether those earnings prove durable enough to close that gap between the current P/E and where the model suggests it could trade. Explore the numbers behind K92 Mining's P/E valuation.
The K92 Mining Narrative: What Would Justify Today's Price?
Narratives for K92 Mining pick up where the P/E work leaves off and spell out the earnings path, margin profile and production assumptions that would need to hold for the current valuation to point meaningfully higher or lower than today. Instead of leaving you with a single model output, they unpack the future that figure depends on, so you can watch how K92 Mining's actual progress lines up with that story over time. These sit on Simply Wall St's Community page.
Community views on K92 Mining are split between those who see more upside left in the story and others who are more restrained.
Bull case: 11% undervalued
"Ongoing high-grade exploration success (across Kora/Kora South, Judd Deeps, and Arakompa) and a substantial pipeline of near-mine and regional targets set the stage for continued resource growth…"
Discover why this Narrative puts K92 Mining at 11% undervalued.
Bear case: roughly fairly valued
"Rising jurisdictional risk in Papua New Guinea, including the potential for regulatory changes, increased taxation, or localized unrest, poses ongoing threats to project continuity and could lead to unforeseen increases in operating costs…"
Explore why this Narrative puts K92 Mining at roughly fairly valued.
K92 Mining’s next question is what the professionals think happens from here
Valuation work only goes so far without checking how the broader analyst community expects K92 Mining to evolve over the next few years, and how those projections compare with where the shares trade today. Explore where analysts expect K92 Mining to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com