
3 U.S. Bank Stocks Built For Higher Interest Rates
Higher for longer interest rates are no longer just a talking point; they now shape how money moves through every sector of the market. That shift can create quiet winners and unexpected pressure points, depending on how each business earns, lends or protects capital. This article walks through three stocks exposed to this new rate reality, all drawn from our U.S. Financials screener, and explains why their stories matter for your portfolio.
The three companies that follow are only a starter pack, drawn from a broader search that surfaced 24 more U.S. banks and insurers with equally interesting rate stories that are not covered here. To see the full list and start sizing up your own highest conviction ideas, head straight into the U.S. Financials – Banks and Insurance Benefiting from Higher-for-Longer Interest Rates screener.
Pinnacle Financial Partners (PNFP)
Overview: Pinnacle Financial Partners is a US regional bank that earns most of its money by taking deposits and making loans to households and businesses, a setup closely tied to how much it can collect on interest as rates stay higher for longer.
Operations: Pinnacle Financial Partners generates about US$2.9b from its core banking activities within the United States, with a US$437 million segment adjustment reconciling to total reported revenue of roughly US$3.3b.
Market Cap: US$14.5b
Pinnacle Financial Partners is tightly linked to the higher for longer theme because a traditional lending and deposit model feeds directly into net interest income when policy rates stay elevated. The bank’s earnings growth has recently compared favorably with many peers, supported by strong net interest income trends and a 2.11% dividend that may appeal to income-focused investors seeking cash distributions while rates remain firm. However, ongoing pressure on funding costs and loan pricing could meaningfully affect the margins that investors are monitoring.
Those moving parts make it worth lining up Pinnacle Financial Partners against peers through the 5 key rewards and 2 important warning signs (1 is major!) before funding costs or margins shift again.

Fifth Third Bancorp (FITB)
Overview: Fifth Third Bancorp is a large U.S. regional bank that collects deposits and makes loans across commercial, consumer and wealth clients.
Operations: Fifth Third Bancorp generates about US$5.3b from Consumer and Small Business Banking, US$4.4b from Commercial Banking and US$0.9b from Wealth and Asset Management, with revenue almost entirely from the United States.
Market Cap: US$48.3b
Fifth Third Bancorp sits at the heart of this higher for longer theme because its lending, payments and deposit engines are closely tied to how much it can earn on every extra basis point of U.S. interest rates.
"Growth in payments and deposit rich platforms such as Direct Express and Newline, which together contribute several billions of dollars of low cost deposits and rising fee revenue, gives Fifth Third Bancorp additional levers to support net interest income and noninterest income over time."
The key factor for Fifth Third Bancorp is how one creeping cost pressure shapes the gap between what it pays for funding and what it earns on loans.
That funding gap is the hinge. Read the full narrative for Fifth Third Bancorp to see how deposit mix, fee engines, and capital plans could be masking where Fifth Third is really heading.

WaFd (WAFD)
Overview: WaFd is a U.S. regional bank focused on lending and deposit services, where higher interest rates directly shape its core earnings power.
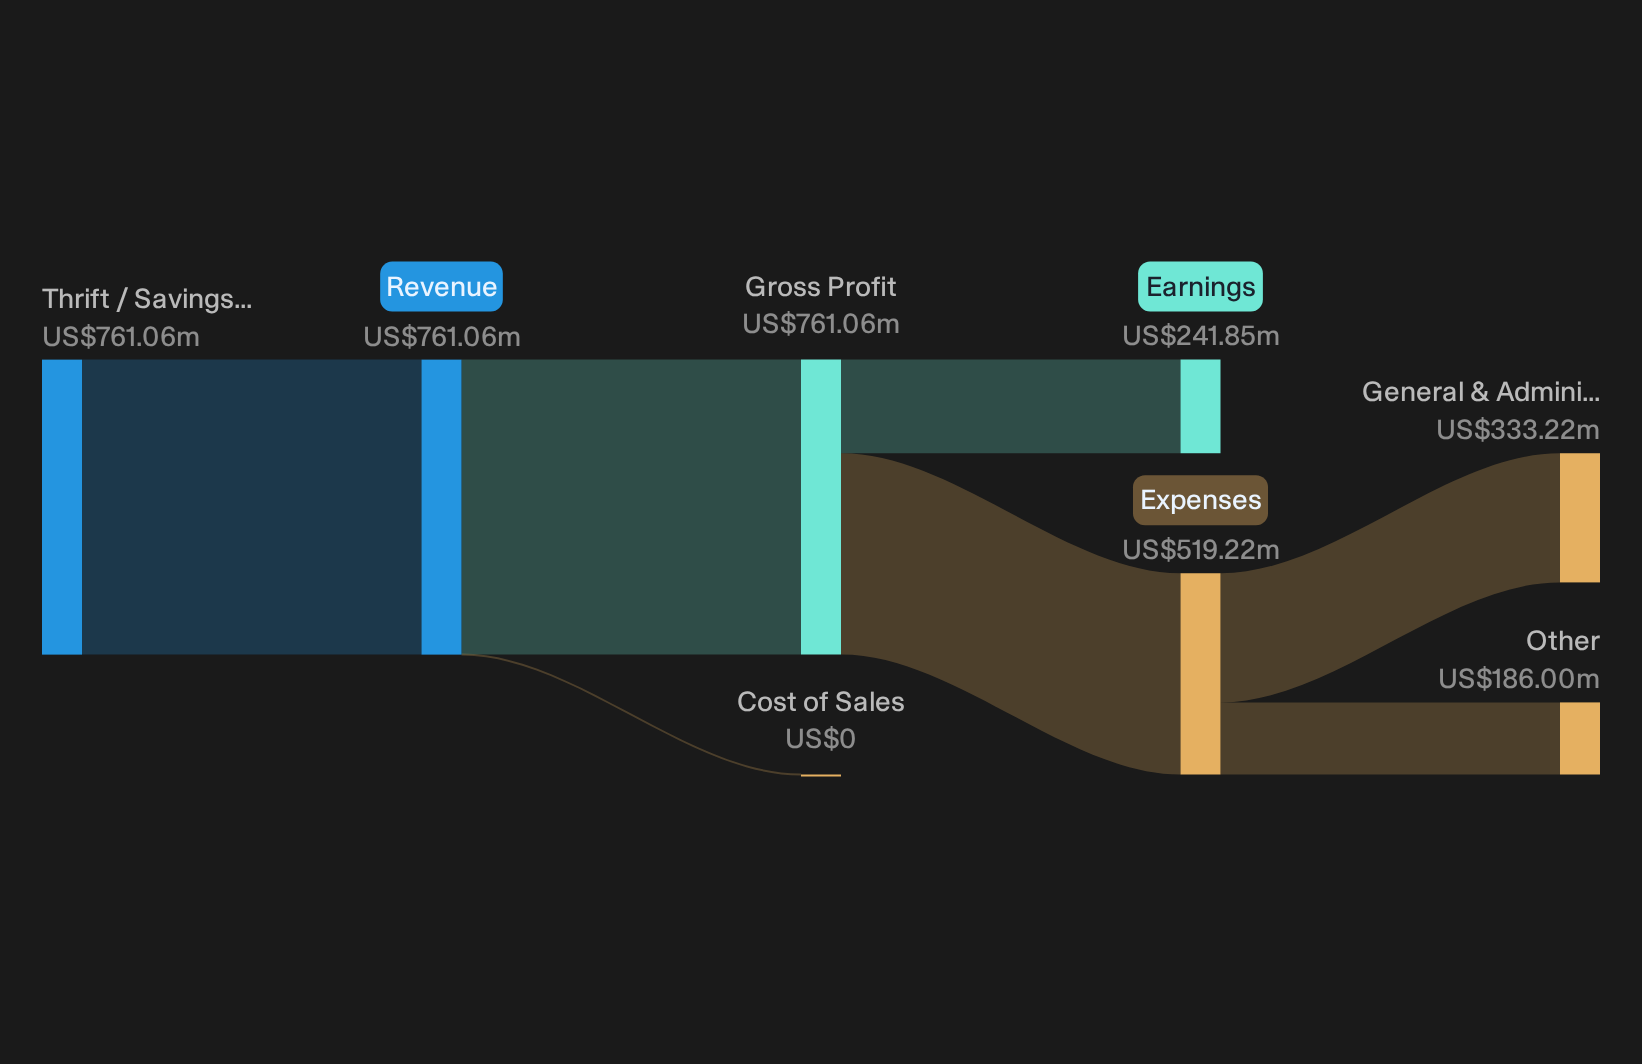
Operations: WaFd generates about US$761 million in revenue from thrift and savings style banking activities, almost entirely within the United States.
Market Cap: US$2.4b
WaFd fits this higher for longer rates theme because its thrift roots and growing commercial focus tie profit directly to what it earns on loans versus what it pays on deposits.
"Ongoing runoff of low yielding single family mortgage loans and redeployment into higher yielding agency mortgage backed securities with no credit risk should structurally lift asset yields and net interest margin over time, improving net income."
What happens to WaFd’s story from here largely comes down to how one unseen pressure shapes the balance between funding costs and earning power.
That unseen pressure is exactly what the full narrative for WaFd unpacks, highlighting how WaFd’s funding mix could accelerate or stall that higher yielding reinvestment story.
Seeking Alternatives Before The Crowd?
Fresh opportunities move fast. Some are breaking out, others quietly building momentum while attention is elsewhere and a few could be caught dropping under the radar for now. Act now.
- Target resilient payers with strong cash generation and use the 7 dividend fortresses to see which high yielders currently combine income strength with balance sheet support.
- Track AI momentum early by scanning the 38 profitable AI stocks that aren't just burning cash where earnings positive operators are already turning machine learning spend into tangible business results.
- Hunt for sturdy compounders using the 30 resilient stocks with low risk scores and focus on businesses screened for steadier fundamentals and lower risk scores before attention really shifts their way.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com