
DHT Holdings (DHT) Secures A Three Year Charter, Is The Stock Fully Valued?
DHT Holdings (DHT) recently secured a three-year time charter for its 2016-built VLCC DHT Panther at $100,000 per day with a global energy company, starting in October 2026.
The charter news comes after a sharp run for DHT Holdings, with a 30-day share price return of 7.92% and a 90-day gain of 10.31%, even though the stock slipped 4.72% over the last session and 3.39% across the week.
At a last close of $21.39, the share price has delivered an 82.20% year-to-date return. Investors who factor in dividends have seen a 92.70% total shareholder return over one year and 187.46% over three years, which highlights the contrast between long-term performance and short-term volatility around new contract announcements.
Scan for other tanker plays with tight contracts and earnings visibility by reviewing the 30 resilient stocks with low risk scores that meet similar quality and risk criteria to DHT Holdings.
So is DHT Holdings’ recent surge and pullback mainly the market reacting to a headline charter, or is it catching up with a business that already prices in a lot of good news?
Most Popular Narrative: 2% Undervalued
DHT Holdings last closed at $21.39, while the most followed narrative pins fair value at $21.85. As a result, the stock is framed as slightly undervalued, with much of that view tied to fleet quality and earnings resilience rather than a single charter headline.
Persistent growth in energy demand from emerging markets, notably in Asia, and evolving global refinery patterns are driving longer trade routes and increased ton-mile demand, supporting sustained high vessel utilization and, therefore, improved revenue visibility for DHT Holdings.
See why 101 investors see DHT Holdings as 2% undervalued.
Result: Fair Value of $21.85 (UNDERVALUED)
Still, DHT Holdings faces clear pressure points, including deeper projected revenue contraction and a policy of paying out all ordinary net income as dividends, which could limit reinvestment.
Find out about the key risks to this DHT Holdings narrative.
Another View on DHT Holdings’ Valuation
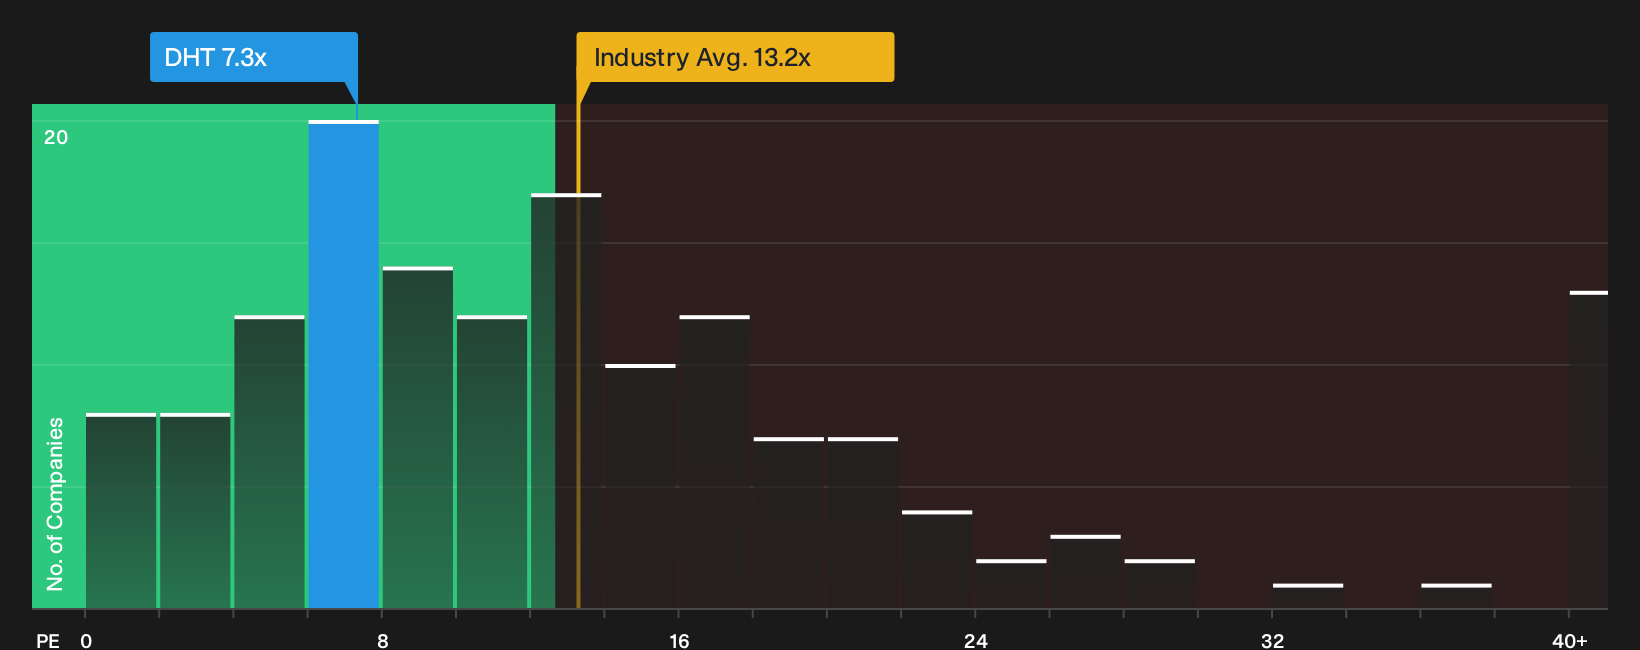
The earlier fair value of $21.85 paints DHT Holdings as modestly undervalued. Using a simple P/E check tells a more cautious story. The stock trades on 7.3x earnings while the estimated fair ratio is 7.2x, so only a tiny cushion exists if sentiment cools.
DHT also sits well below the US Oil and Gas industry average P/E of 13.2x and under the 13.3x peer group level. This hints at a discount that could reflect genuine opportunity or skepticism about forecast revenue declines and dividend coverage. Which side of that trade-off do you think the market is really pricing in right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around DHT Holdings leaves you undecided, consider acting while sentiment is still forming and weigh both sides using the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DHT Holdings?
If DHT Holdings has sharpened your focus on quality and risk, you may want to broaden your watchlist with a few targeted idea lists built from clear, data driven filters.
- Target stability while still pursuing upside by reviewing a 30 resilient stocks with low risk scores that could help you avoid fragile balance sheets and surprise blow ups.
- Hunt for pricing gaps by checking a curated 29 high quality undervalued stocks that screens for strong fundamentals at what may be discounted valuations.
- Build potential income streams with a 7 dividend fortresses that focuses on higher yielding payouts backed by solid financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com