
BlueNord (OB:BNOR) Stock Looks Above Fair Value On Earnings
BlueNord has delivered a very strong run over several years, which puts a spotlight on whether the current share price lines up with what its earnings can reasonably support. With that history in the background, the key issue now is how much of the earnings story is already reflected in today's valuation.
- BlueNord's share price has risen very sharply over the past 5 years, which raises the question of how much of its earnings power is already priced in.
- The business depends heavily on converting operating performance into durable earnings, so any shift in costs, production mix or capital spending plans can change how investors think about the durability of its profit stream.
- Your read on BlueNord is one view; the desks covering it have another. See what analysts think BlueNord's shares could be worth.
The stock's next move may depend on whether BlueNord's current price looks aligned with what its earnings suggest investors are paying for.
If you want to stress test the same earnings question beyond BlueNord, you may also consider looking at companies in the 171 high quality undervalued stocks.
Is BlueNord Getting Expensive on Earnings?
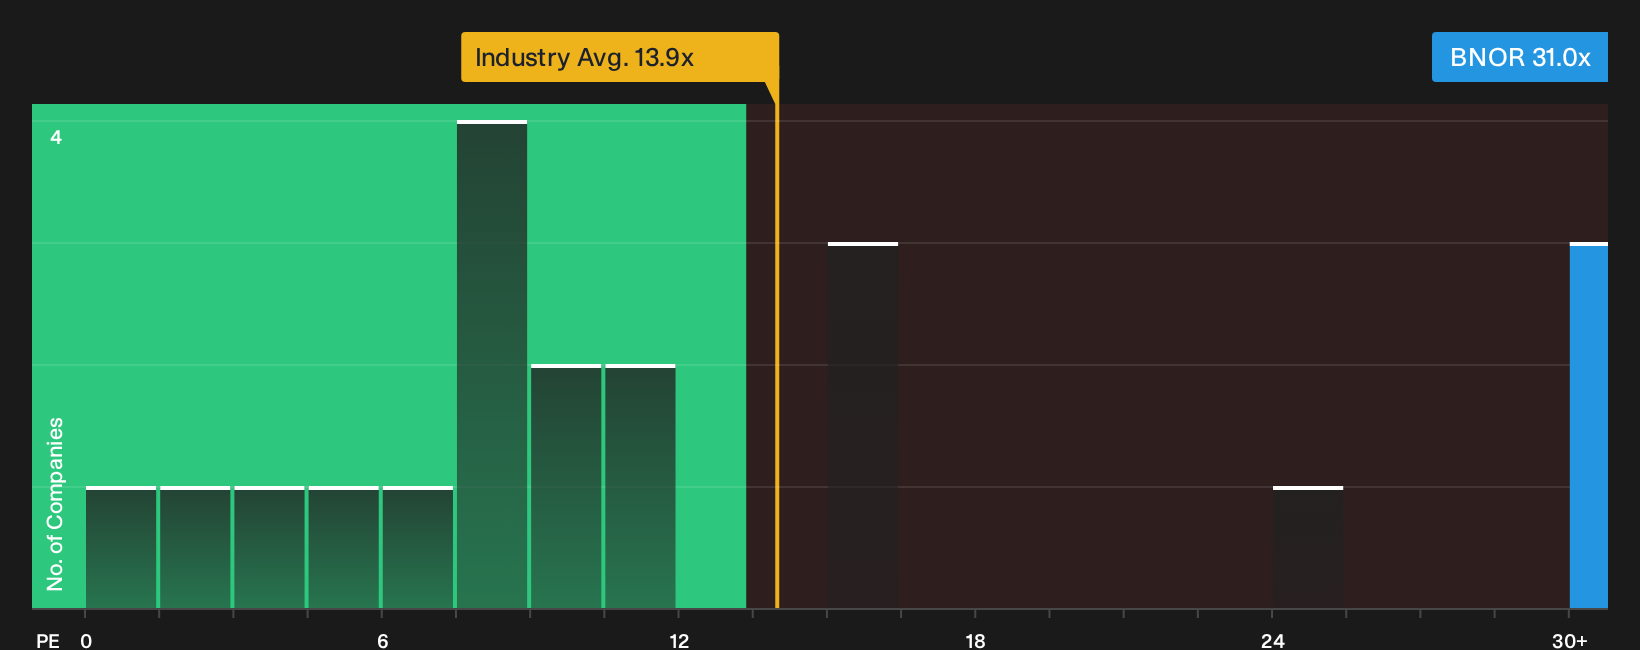
The P/E ratio suits BlueNord because investors are mainly paying for its earnings power rather than rapid top line expansion. On this yardstick, the stock trades on about 31.0x earnings, which is much richer than the Oil and Gas industry average of roughly 13.1x and also well above the peer group on about 14.9x. That gap indicates buyers are already paying a heavy premium for the current earnings stream.
The tailored fair multiple implied by BlueNord's own profile is lower than where the shares trade, so the current P/E points to the stock being overvalued on this framework rather than cheap. For anyone considering the shares, the question is whether the company’s earnings quality, project pipeline and balance sheet strength justify paying a meaningfully higher P/E than its sector and peers, or whether it makes more sense to look at alternatives that offer similar economics on a lower multiple. Explore the numbers behind BlueNord's P/E valuation.
The BlueNord Narrative: What Would Justify Today's Price?
Narratives for BlueNord pick up where the P/E puzzle leaves off by spelling out which future paths for growth, margins and earnings would plausibly support a much higher or lower share price than today. Rather than leaning on a single multiple or one model output, each scenario lays out the key assumptions behind its fair value view so you can track those against BlueNord's reported numbers as new results arrive, all within Simply Wall St's Community page.
Community views on BlueNord’s valuation are divided between a premium price that needs strong execution and a case that sees more upside left.
Bull case: 21% undervalued
"Modern, efficient Tyra facilities and a shift to higher throughput on existing infrastructure are contributing to structurally lower lifting costs per BOE, which can improve net margins and accelerate the conversion of EBITDA into free cash flow..."
Discover why this Narrative puts BlueNord at 21% undervalued.
Bear case: 11% overvalued
"Although Tyra is now inaugurated and contributing higher gas volumes into a region that still imports close to 90% of its gas, the hub remains constrained by water treatment and compressor capacity..."
Explore why this Narrative puts BlueNord at 11% overvalued.
One more side of BlueNord that could change the picture
Valuation only tells part of the story for BlueNord, since separate checks have highlighted potential pressure points in the background that deserve a closer look before you reach any view. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com