
Carl Zeiss Meditec (XTRA:AFX) Stock May Be Undervalued On Earnings
Carl Zeiss Meditec has seen its share price fall sharply in recent years, which puts fresh focus on whether the current valuation still lines up with the earnings that support it. For anyone looking at the stock today, the key issue is how much of that change is already reflected in what the business actually earns.
- Over the past 5 years the share price has declined 81.5%, which puts the spotlight firmly on whether the current market value is still in step with the company's earnings power.
- The business depends heavily on consistent profitability in ophthalmic devices and related services, so any shift in margins or cash conversion can have a direct impact on how sustainable its current earnings base really is.
- The analysts covering Carl Zeiss Meditec have run their own numbers. See what analysts think Carl Zeiss Meditec's shares could be worth.
For investors, the debate is whether Carl Zeiss Meditec's current share price is properly supported by the earnings it generates today and what those profits may reasonably support over time.
If Carl Zeiss Meditec's recent share price decline has you reassessing what you own, a focused stock screen can be a practical next step, starting with 171 high quality undervalued stocks.
Is Carl Zeiss Meditec Still Cheap on Earnings?
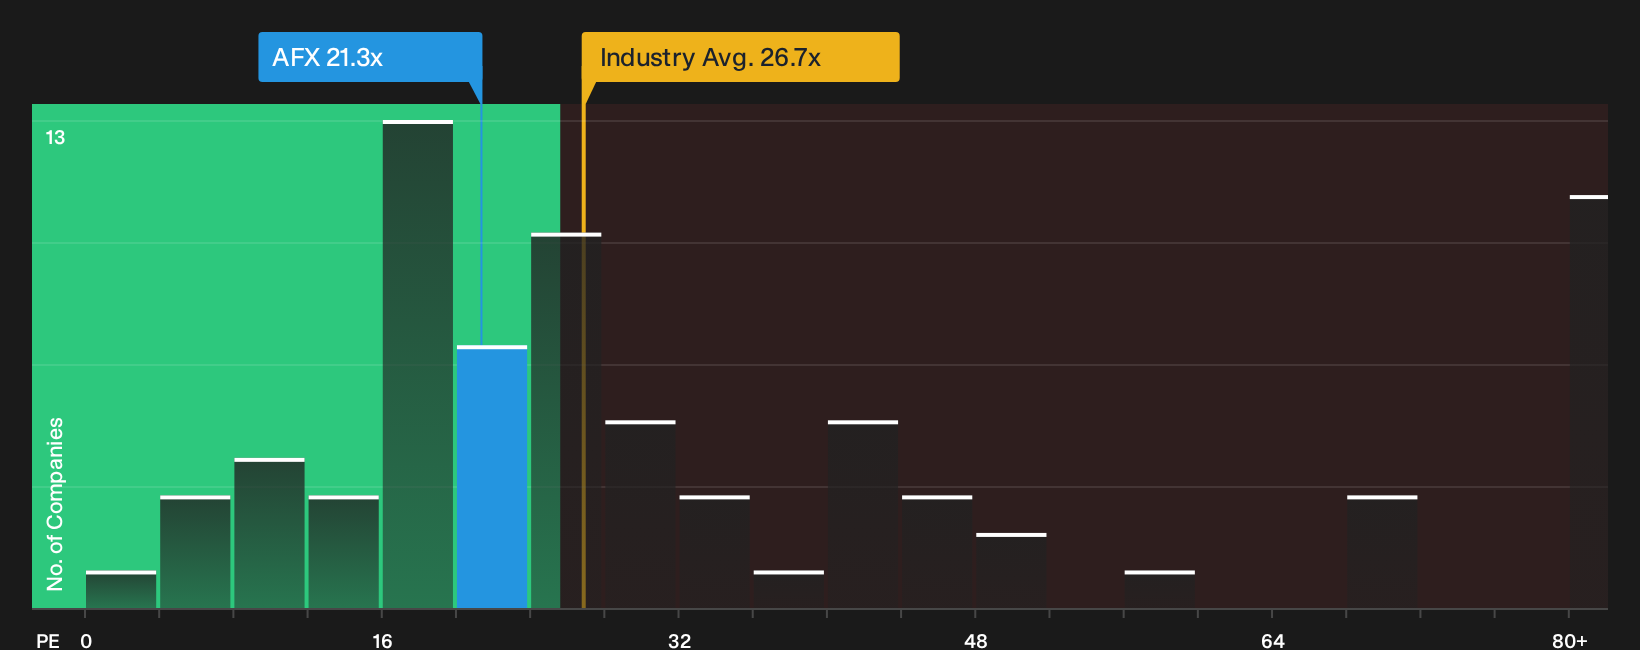
The P/E ratio works well for Carl Zeiss Meditec because earnings remain the key anchor for how investors frame this ophthalmic equipment specialist. The stock currently trades on a P/E of 21.3x, which sits below the wider Medical Equipment industry average of 23.9x and only slightly above the peer group on 18.9x. That puts the shares in a kind of middle ground where you pay something close to what similar businesses command, rather than an obvious premium or a fire sale discount.
The tailored fair-value P/E model, which blends factors like the company’s margins, growth profile, market size and risk, points to a higher multiple than where the equity changes hands today. On this framework the current 21.3x suggests the valuation leans toward undervalued compared with what those fundamentals might support over time. For anyone already holding or building a watchlist around Carl Zeiss Meditec, the next step is working out whether the earnings quality and competitive position justify that gap and where it could close from here. Explore the numbers behind Carl Zeiss Meditec's P/E valuation.
The Carl Zeiss Meditec Narrative: What Would Justify Today's Price?
Carl Zeiss Meditec Narratives pick up where the P/E debate leaves off by spelling out which future paths for growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and they sit on Simply Wall St’s Community page as structured viewpoints. Each one treats fair value as a thesis about the business that can be tracked over time, rather than a single frozen estimate.
Community views on Carl Zeiss Meditec stretch from a reset-and-recovery story to a more cautious read on execution risk.
Bull case: 16% undervalued
"Analyst consensus highlights VISUMAX 800's strong launch in China as a catalyst, but with recurring procedure revenue now over 50% of group sales..."
Discover why this Narrative puts Carl Zeiss Meditec at 16% undervalued.
Bear case: 9% overvalued
"The decline in organic sales growth and the adjusted revenue decline of minus 7.3% suggest challenges in achieving consistent revenue growth..."
Explore why this Narrative puts Carl Zeiss Meditec at 9% overvalued.
One more Carl Zeiss Meditec check that belongs beside the valuation work
Headline multiples only tell part of the story, and the internal checks on Carl Zeiss Meditec have also raised some concerns that careful shareholders may want to weigh before going further. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com