
Mobileye (MBLY) Stock May Be Fully Priced On Robotaxi Fleet Funding News
Mobileye Global has seen a steep share price retreat in recent years, which puts fresh focus on what investors are really paying for in terms of its sales base. With the stock now trading at US$7.68, the key issue is how that market value lines up against the revenue engine behind its autonomous driving technology.
- The share price has fallen 81.0% over the past 3 years, which makes the current valuation question far more about what the business can justify through its sales profile than about momentum.
- Mobileye’s recent funding lead role in Beep’s Series B round signals a push to embed its autonomous systems more deeply in commercial fleets, which can influence how quickly future sales may scale and how much investors are willing to pay for each dollar of revenue.
- Your read on Mobileye Global is one view; the desks covering it have another. See what analysts think Mobileye Global's shares could be worth.
The stock's next move may depend on whether Mobileye Global’s current share price is adequately supported by its sales when set against the Fair Ratio benchmark.
To pressure test whether Mobileye Global’s sales-based valuation still appeals after such a steep share price fall, it can help to line it up against 86 AI infrastructure stocks.
Has Mobileye Global Run Too Far on Sales?
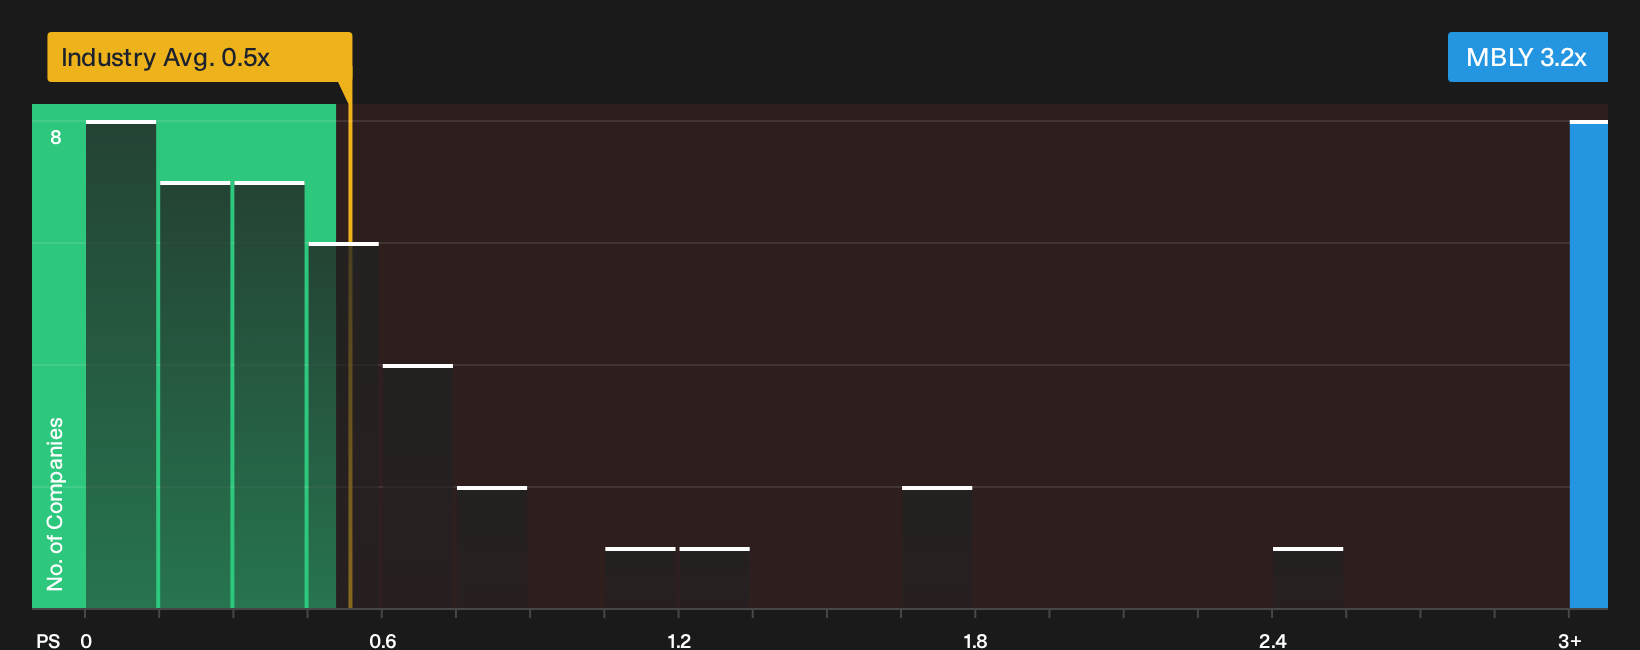
P/S is a useful lens for Mobileye Global because the market is still paying more attention to its revenue base than to current earnings. On this measure, the stock trades on a P/S of 3.2x, which is above both the Auto Components industry average of 0.5x and the peer group on 0.7x. The Fair Ratio model, which looks at Mobileye’s own growth outlook, margins, size and risk, points to a lower P/S than the one implied by today’s price, so the shares screen as overvalued on this metric.
Because Mobileye just led Beep’s Series B round to push its autonomous systems further into commercial fleets, some investors may be treating that expansion effort as justification for paying a richer multiple per dollar of revenue. The current P/S still sits above the level suggested by the tailored Fair Ratio benchmark, which means the market is already assigning a premium to Mobileye’s sales profile relative to sector norms and similar businesses. Explore the numbers behind Mobileye Global's P/S valuation.
The Mobileye Global Narrative: What Would Justify Today's Price?
Narratives for Mobileye Global pick up where the valuation puzzle leaves off by spelling out which assumptions on future growth, profitability and earnings power would need to hold for the stock to be worth meaningfully more or less than today’s price. Each one treats Mobileye Global's fair value as a thesis about how the business might develop over time, so you can see how that view holds up as new information arrives on Simply Wall St's Community page.
Community views on Mobileye Global are split between those who see underappreciated upside and those who think expectations still run ahead of execution risk.
Bull case: 36% undervalued
"The planned launch of a vertically integrated robotaxi service in at least one U.S. city in 2027, along with ongoing deployment work with partners such as Volkswagen's MOIA and Beep, sets up a new revenue line from both vehicle level economics and potential recurring mobility services income…"
Discover why this Narrative puts Mobileye Global at 36% undervalued.
Bear case: 11% overvalued
"Mobileye's future revenue growth is threatened by global regulatory tightening around AI and data privacy, which could significantly prolong validation and approval cycles for advanced driver-assistance and autonomous technologies, delaying time to market and potentially resulting in lost OEM contracts…"
Explore why this Narrative puts Mobileye Global at 11% overvalued.
One more angle on Mobileye Global that could change the story
Price and sales only tell part of the picture for Mobileye Global, because professional estimates for where this business might be a few years from now offer a separate yardstick to compare with today's market value. Explore where analysts expect Mobileye Global to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com