
Beiersdorf (XTRA:BEI) Could Be 7% Undervalued As NIVEA Expands Product And Media Push
Beiersdorf (XTRA:BEI) is back in the spotlight after NIVEA rolled out its Smooth & Glow Body Milk nationwide and expanded Black & White Deodorant into a Channel 4 branded entertainment push targeting Gen Z viewers.
For context, Beiersdorf’s share price has climbed over the past week, but is still down 17.63% on a year to date basis. The 1 year total shareholder return has fallen 13.44%, suggesting that recent product launches and marketing pushes are drawing attention yet have not fully shifted longer run sentiment.
Scan beyond Beiersdorf and see how other consumer-focused players are trying to capture similar momentum with our hand picked 619 high quality undiscovered gems.
Beiersdorf’s recent bounce tells two stories at once: a long running drawdown and fresh optimism around NIVEA’s product and media push. How does that mix line up against what the current valuation implies?
Most Popular Narrative: 7% Undervalued
Beiersdorf last closed at €76.46, while the most followed narrative pegs fair value closer to €82.11. This implies the recent share price slump sits at odds with the longer term cash flow story embedded in those models.
Breakthrough innovation in science-based skincare, particularly the global rollout of the Epicelline anti-aging ingredient under both Eucerin and NIVEA, positions Beiersdorf to capture increased demand from an aging, health-conscious population, driving higher-margin revenue growth from both premium and mass-market channels.
See why 17 investors see Beiersdorf as 7% undervalued.
Result: Fair Value of €82.11 (UNDERVALUED)
Still, if retailer tension in Europe drags on or premium brands like La Prairie stay weak, that 7% undervaluation narrative around Beiersdorf could unravel fast.
Find out about the key risks to this Beiersdorf narrative.
Another View: What Beiersdorf’s P/E Is Telling You
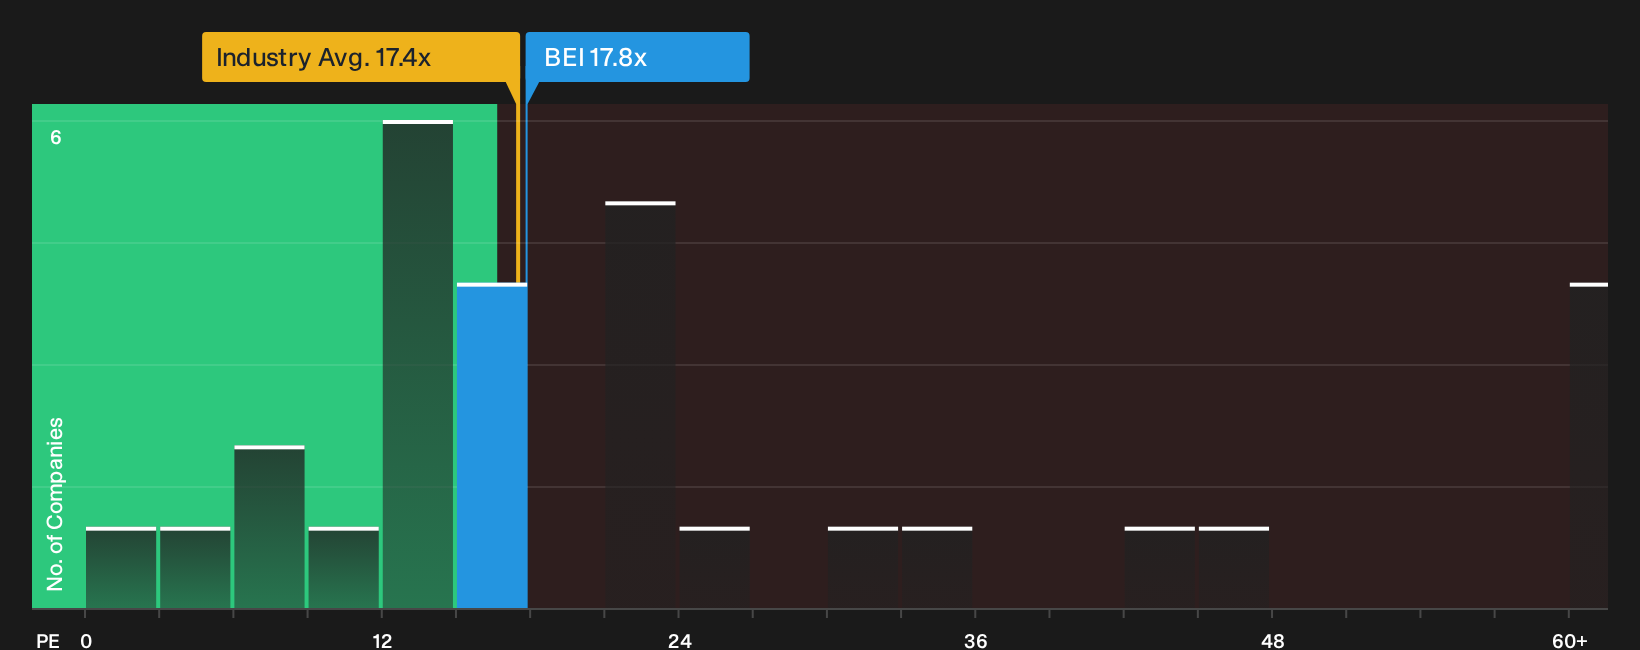
The cash flow narrative presents Beiersdorf as undervalued, yet the snapshot from earnings multiples looks less generous. The stock trades on a P/E of 17.8x, compared with 16.9x for the wider European Personal Products group and a fair ratio of 16.2x.
That gap means investors today are paying a premium to both the sector and the fair ratio for each euro of current earnings, even as the share price is described as 30.7% below future cash flow value. Is that premium a comfort or a complication in your own thesis on Beiersdorf?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Beiersdorf’s value story, or just healthy debate in action? Use the numbers as your starting point and move quickly to test your own thesis with the 3 key rewards.
Looking for more Beiersdorf-sized ideas?
Do not stop your research with Beiersdorf. Fresh ideas often come from comparing different business models, risk profiles, and balance sheets side by side.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (198 results), which keeps financial strength front and centre.
- Hunt for potential mispricings by working through the 171 high quality undervalued stocks, which focuses on quality paired with attractive valuations.
- Prioritise stability and downside protection by reviewing the 229 resilient stocks with low risk scores to spot companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com