
Global Payments (GPN) Stock Looks Fully Valued Given Its Earnings Outlook
Global Payments has seen its share price pressure build over several years, which puts extra focus on whether the current valuation still lines up with the earnings power of the business. With the stock sitting around US$84.78 at the last close, the real question is how solid the profit engine behind that quote looks today.
- The share price has fallen 45.0% over the past 5 years, so any assessment now leans heavily on whether the earnings profile justifies staying invested through that kind of drawdown.
- The company relies on processing volumes and fee income, so trends in profitability, cost control and cash conversion can play an outsized role in how the earnings base supports the current share price.
- Your read on Global Payments is one view; the desks covering it have another. See what analysts think Global Payments's shares could be worth.
The issue now is whether Global Payments' current price is adequately supported by the earnings the business is generating and is expected to produce.
If you are weighing Global Payments against other opportunities where earnings also sit under the microscope, a focused stock screen built around 29 high quality undervalued stocks.
Does Global Payments Look Pricey on Earnings?
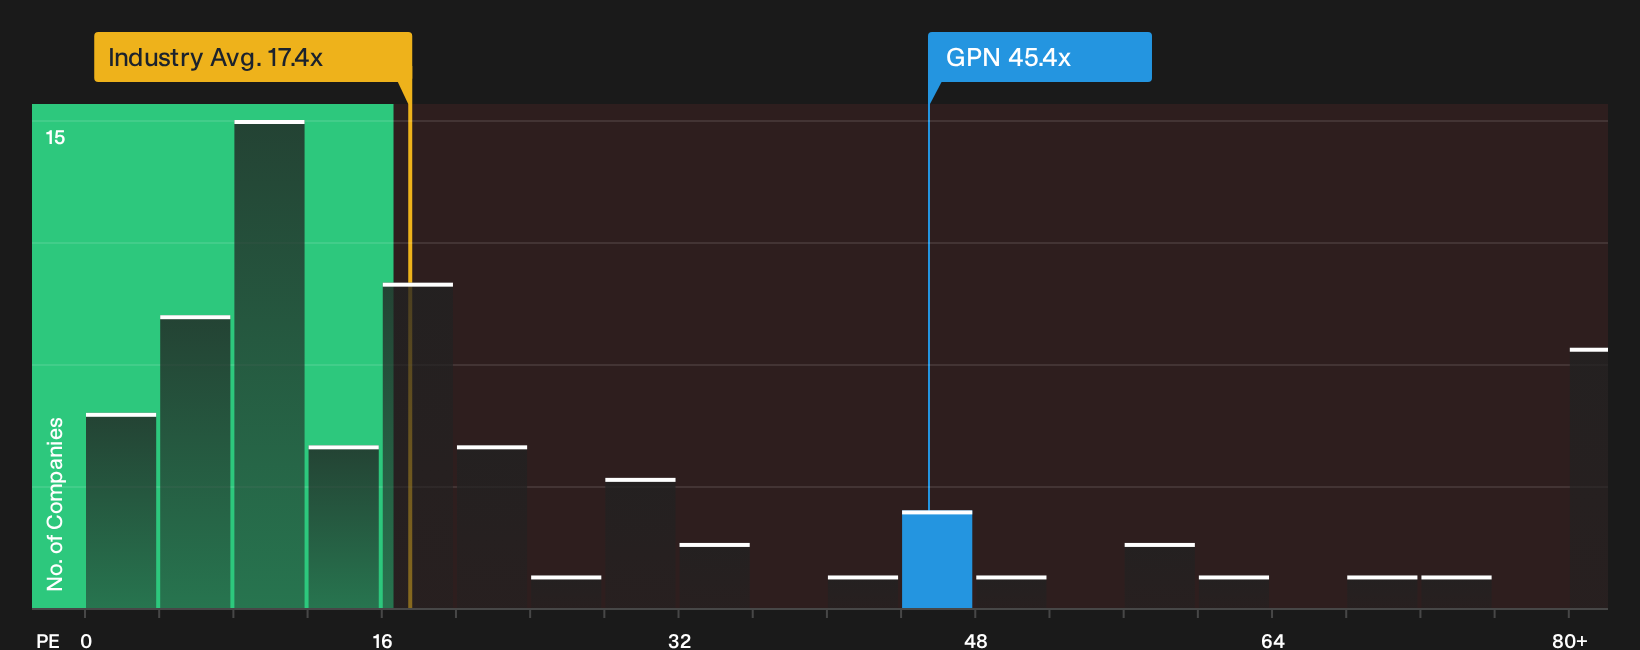
The P/E ratio fits Global Payments because earnings are a key yardstick for a payments processor that leans on transaction volume and fee income. On that measure, the stock trades on about 45.4x earnings, which is far above the Diversified Financial industry average of roughly 17.1x.
Compared with a peer group around 12.9x and a modelled P/E that would typically be expected for Global Payments given its profitability profile and risk mix, the current multiple screens higher. That premium suggests investors are putting a rich value on each dollar of earnings today, so you need to be comfortable that the earnings base and its resilience justify paying well above sector and peer norms. Explore the numbers behind Global Payments's P/E valuation.
The Global Payments Narrative: What Would Justify Today's Price?
Global Payments' valuation puzzle really comes down to what the future needs to look like for the current P/E to make sense. Narratives on Simply Wall St's Community page spell out the earnings, growth and margin paths that would need to play out for the stock to be worth materially more or less than today's price. Each one lays out its own fair value assumptions so you can measure them against the numbers as they are reported over time.
Community views on Global Payments split into two clear camps, with one side seeing meaningful upside and the other flagging downside risk.
Bull case: 21% undervalued
"The market is applying a conglomerate discount and a debt penalty, while the sheer volume of Free Cash Flow provides a massive safety net..."
Discover why this Narrative puts Global Payments at 21% undervalued.
Bear case: 21% overvalued
"Global Payments faces a persistent threat from the accelerating shift toward direct-to-consumer and embedded payment capabilities within mobile platforms, which could bypass traditional payment processors..."
Explore why this Narrative puts Global Payments at 21% overvalued.
For Global Payments, one unresolved question still matters
Global Payments' earnings multiple tells only part of the story, because separate checks have flagged potential issues that could change how you view the whole risk profile. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com