
Exploring 3 Undervalued European Small Caps With Insider Buying
The European market has experienced volatility recently, with the pan-European STOXX Europe 600 Index declining amid heightened energy prices and inflation concerns. As investors navigate these challenging conditions, small-cap stocks with insider buying can present intriguing opportunities for those seeking potential value plays in a fluctuating economic landscape.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 39.19% | ★★★★★★ |
| Telecom Plus | 7.9x | 0.3x | 39.36% | ★★★★★☆ |
| Nyab | 17.7x | 0.8x | 31.79% | ★★★★☆☆ |
| Franchise Brands | 27.9x | 2.1x | 46.48% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 16.54% | ★★★★☆☆ |
| Saniona | 7.6x | 3.3x | 29.11% | ★★★★☆☆ |
| Linc | 12.5x | 13.0x | 31.73% | ★★★★☆☆ |
| Eurocell | 23.7x | 0.3x | 46.29% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.47% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -222.91% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
Fevertree Drinks (AIM:FEVR)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Fevertree Drinks is a premium mixer company specializing in the production and distribution of high-quality tonic waters, ginger ales, and other carbonated mixers, with a market capitalization of approximately £1.62 billion.
Operations: Fevertree Drinks generates its revenue primarily from sales, with recent figures showing £361.7 million in quarterly revenue as of September 2024. The company has experienced fluctuations in its gross profit margin, which was last recorded at 37.56% in December 2024. Cost of goods sold (COGS) and operating expenses are significant components affecting profitability, with COGS reaching £230.1 million and operating expenses at £106.8 million during the same period.
PE: 39.0x
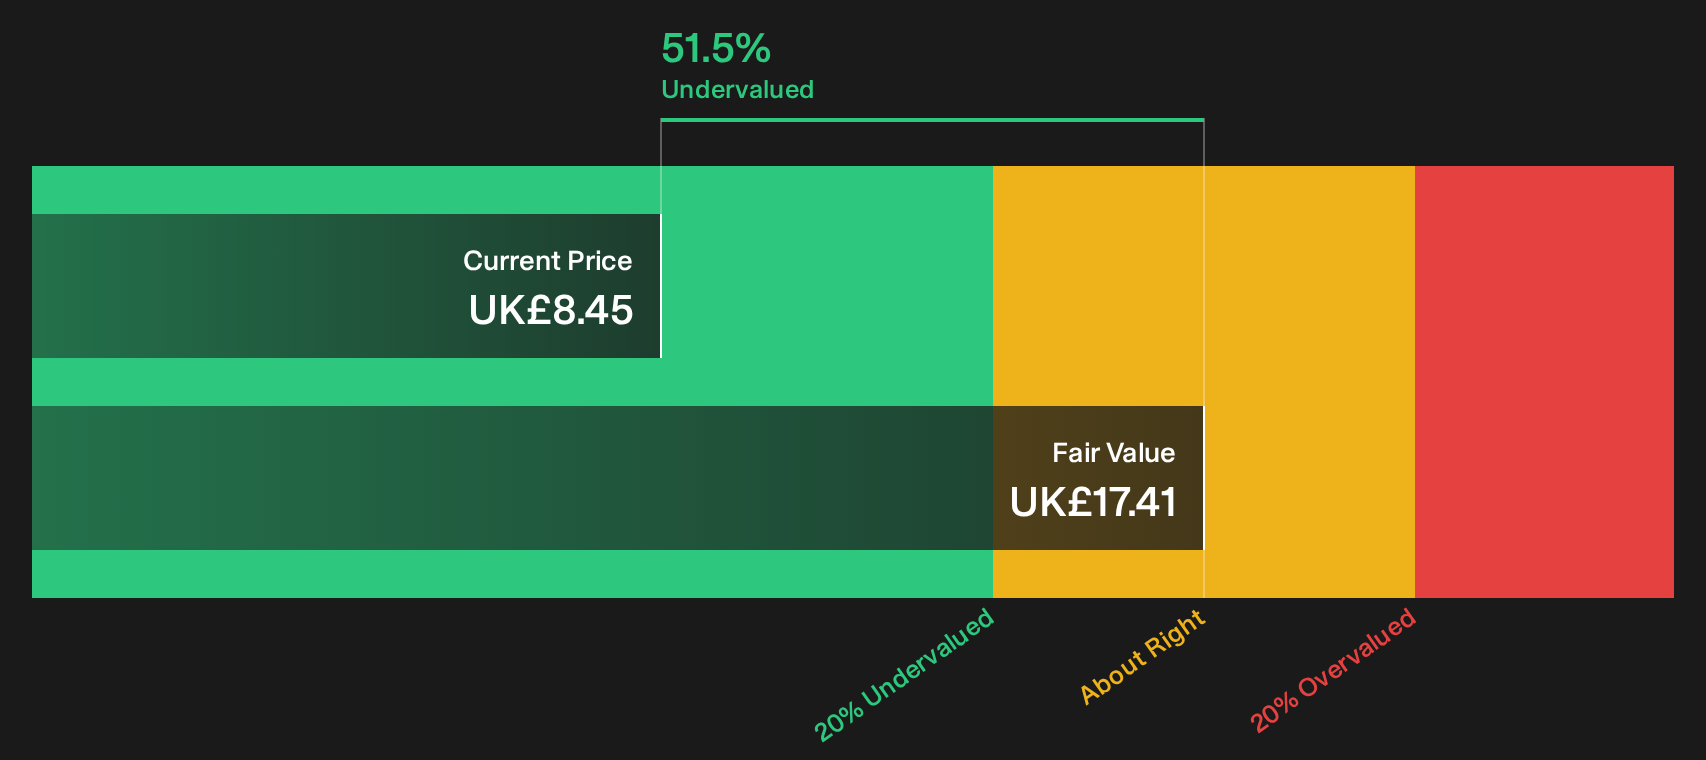
Fevertree Drinks is catching attention as a potential undervalued player in the European market. Recent insider confidence was demonstrated by Domenico De Lorenzo, who purchased 44,674 shares for £348,256 between January and June 2026. The company repurchased 2.87 million shares for £23.6 million during this period, signaling management's belief in its value. Sales rose to £165.1 million from last year's £144.3 million with net income increasing to £11 million from £8.4 million, reflecting healthy growth prospects despite reliance on external borrowing for funding and recent board changes impacting governance dynamics.
- Navigate through the intricacies of Fevertree Drinks with our comprehensive valuation report here.
Gain insights into Fevertree Drinks' past trends and performance with our Past report.
Tamburi Investment Partners (BIT:TIP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Tamburi Investment Partners is an Italian investment company engaged in investment banking and merchant banking activities, with a market cap of approximately €1.83 billion.
Operations: TIP's revenue primarily comes from its investment banking and merchant banking activities, totaling €5.03 million. The company has experienced fluctuations in its gross profit margin, with recent figures showing a negative trend at -1.42% as of September 2024 and improving to 0.42% by June 2026. Operating expenses have varied significantly over time, reaching €30.86 million in March 2026 before decreasing to €26.84 million by June of the same year, impacting overall profitability dynamics within the business model.
PE: 3509.5x
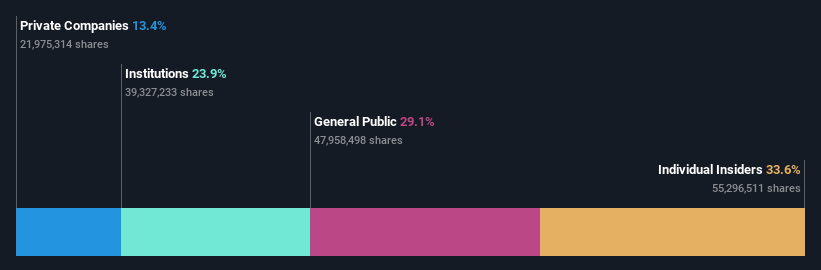
Tamburi Investment Partners, a European investment company, has seen insider confidence with recent share purchases indicating strong belief in its potential. Despite reporting a net loss of €15.4 million for the first half of 2026, the company's sales and revenue increased significantly compared to last year. With earnings projected to grow by 15.68% annually, Tamburi's low profit margins at 8.1% suggest room for improvement as it aims to capitalize on growth opportunities within its sector.
- Click here and access our complete valuation analysis report to understand the dynamics of Tamburi Investment Partners.
Understand Tamburi Investment Partners' track record by examining our Past report.
Funding Circle Holdings (LSE:FCH)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Funding Circle Holdings is a financial technology company that operates a peer-to-peer lending platform, facilitating loans primarily for small and medium-sized enterprises, with a market capitalization of approximately £0.45 billion.
Operations: Funding Circle Holdings generates revenue primarily from Term Loans (£199.7 million) and Flexipay (£50.5 million). The company has experienced fluctuations in its gross profit margin, reaching 69.82% in the latest reported period. Operating expenses are significant, with a notable portion allocated to sales and marketing activities. Over recent periods, net income margins have varied significantly but showed an improvement to 25.10% as of the last available data point.
PE: 8.8x
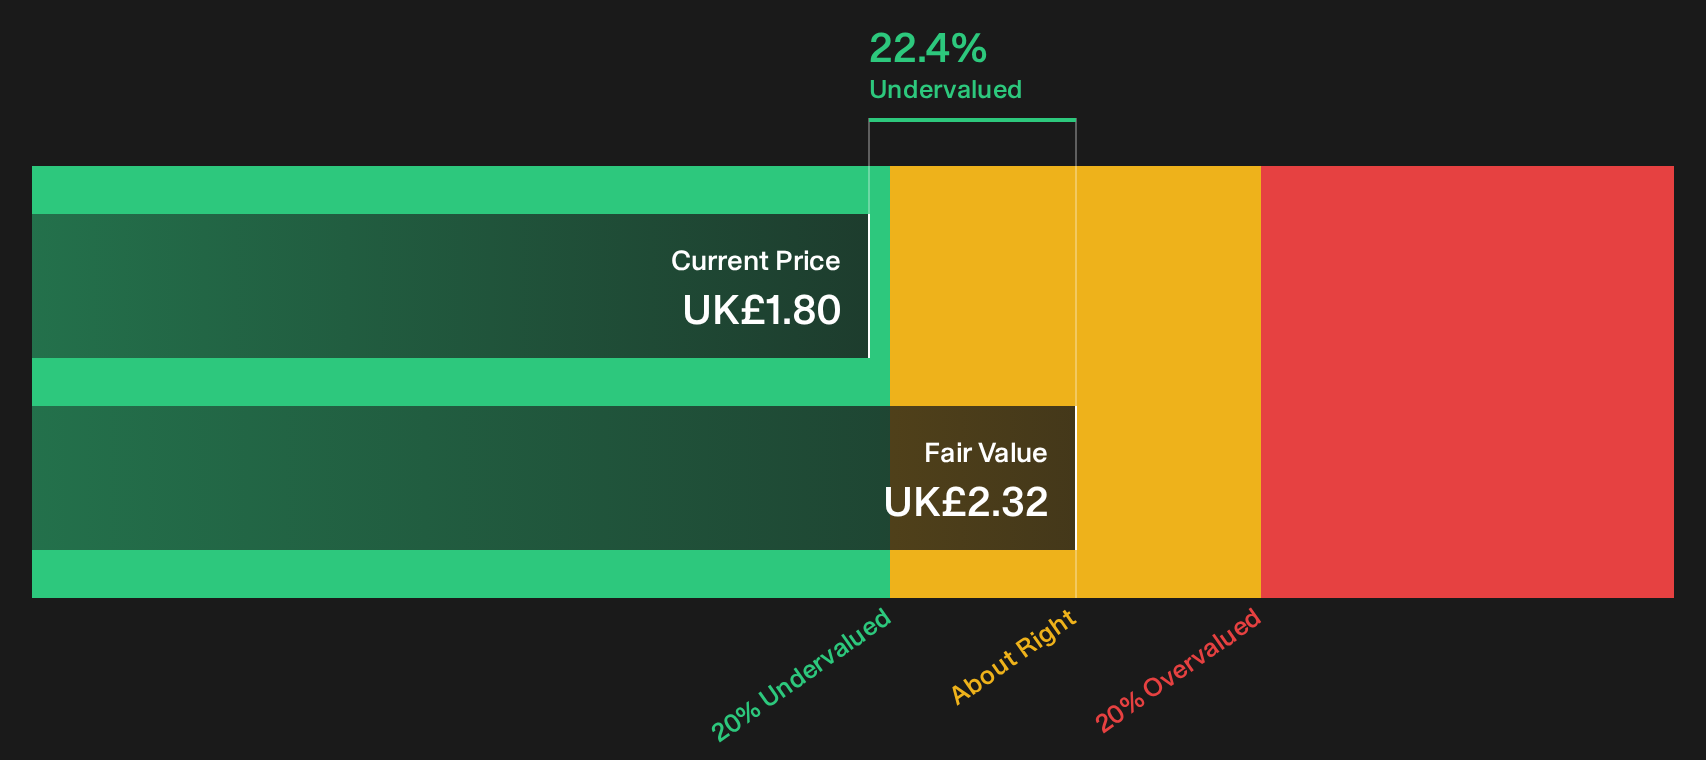
Funding Circle Holdings, a dynamic player in the European market, recently showcased promising financials with first-half 2026 revenue jumping to £138.2 million from £92.3 million last year and net income rising to £22.6 million from £5.8 million. The company completed a share buyback of 13,950,978 shares for £22.3 million by June 2026, reflecting strategic confidence in its growth trajectory. Additionally, an enhanced earnings forecast for fiscal year 2026 projects revenues exceeding £255 million, underscoring potential value within this sector's landscape amidst executive transitions and innovative product launches like their new mobile app designed for SME financial management efficiency.
- Unlock comprehensive insights into our analysis of Funding Circle Holdings stock in this valuation report.
Explore historical data to track Funding Circle Holdings' performance over time in our Past section.
Next Steps
- Click here to access our complete index of 43 Undervalued European Small Caps With Insider Buying.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com