
InterDigital (IDCC) Stock Looks Hard To Call After Dividend Raise
InterDigital has delivered very large 5 year gains for shareholders, yet the real question today is whether that kind of share price outcome still lines up with what its earnings can support. With the stock around US$333.76 at the last close, the focus now shifts to what investors are really paying for the underlying profit stream.
- The share price has returned about 440.5% over 5 years, which puts a lot of weight on the idea that InterDigital’s earnings story can keep carrying that kind of valuation.
- The board’s decision to raise the regular quarterly dividend to US$0.75 per share from late 2026 signals confidence in future cash generation, which can influence how much investors are prepared to pay for each dollar of profit.
- Your read on InterDigital is one view; the desks covering it have another. See what analysts think InterDigital's shares could be worth.
The issue now is whether InterDigital’s current price is justified by its earnings when you line it up against the Fair Ratio benchmark.
If you are weighing whether InterDigital’s earnings justify this kind of dividend and share price, it can help to compare it with other 7 dividend fortresses
Does InterDigital Look Fairly Valued on Earnings?
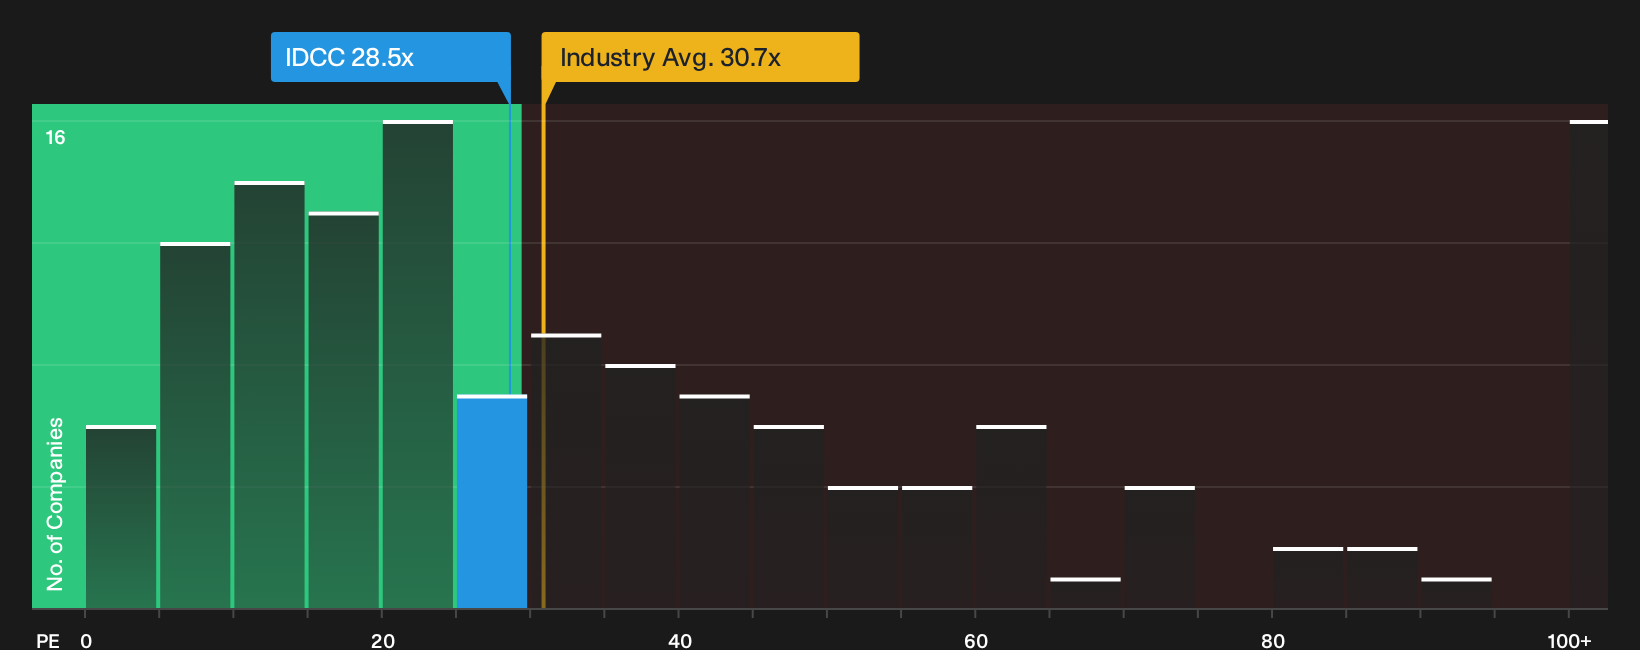
The P/E ratio works well for InterDigital because earnings are a key lens on a licensing focused software business. On this measure, the stock trades on about 28.5x earnings. That is slightly below the wider software industry average of roughly 30.5x and also under the peer group marker of about 44.8x, so investors are not paying the very top tier price that some comparable stocks command.
The Fair Ratio benchmark, which blends factors like InterDigital’s margins, growth profile, size and risk, points to a multiple close to where the shares trade today. That suggests the valuation is broadly about right on earnings, rather than clearly cheap or clearly stretched. Because the board has already flagged a higher regular dividend from late 2026, the market is effectively treating that payout plan as consistent with the current earnings multiple rather than a reason to re rate the stock sharply upward. Explore the numbers behind InterDigital's P/E valuation.
The InterDigital Narrative: What Would Justify Today's Price?
Narratives for InterDigital pick up where the P/E comparison leaves off by explaining what path for earnings, margins and cash flows would need to occur for the stock to be worth meaningfully more or less than today’s price. Each scenario presents its own set of assumptions behind a fair value view, so you can judge those inputs yourself against InterDigital's actual results on Simply Wall St's Community page as new numbers appear.
One of the top community narratives on InterDigital: 28% undervalued
"Bullish analysts view the Amazon licensing agreement as strong validation of InterDigital's video and streaming patents, which they see as supportive of higher confidence in long term monetization…"
Discover why this Narrative puts InterDigital at 28% undervalued.
One more InterDigital angle worth checking before you move on
InterDigital’s story on profits and valuation is only part of the picture, because the people steering the business and the way they are rewarded can shape how those numbers evolve over time. See who runs InterDigital and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com