
Ingevity (NGVT) Stock Looks Fully Priced On Current Earnings
Ingevity has delivered a strong share price run in recent years, which naturally puts the spotlight on whether the current US$71.27 level still lines up with what its earnings can support. For anyone considering the stock today, the real issue is how that past return squares with the profit engine underneath the business.
- Over the past 3 years, Ingevity has returned 51.6%, which makes it important to ask whether that kind of share price outcome is now fully reflected in what the company currently earns.
- The group’s value story hinges on how reliably it can turn its specialty chemicals and materials operations into consistent profits, since that earnings base is what ultimately anchors any assessment of the share price.
- Your read on Ingevity is one view; the desks covering it have another. See what analysts think Ingevity's shares could be worth.
For investors, the debate is whether Ingevity’s recent share price around US$71.27 is adequately supported by the earnings power the business is delivering today.
If you are evaluating Ingevity at US$71.27 from an earnings perspective, it can be useful to compare it with other stocks that meet similar quality criteria using the 29 high quality undervalued stocks
Does Ingevity Look Pricey on Earnings?
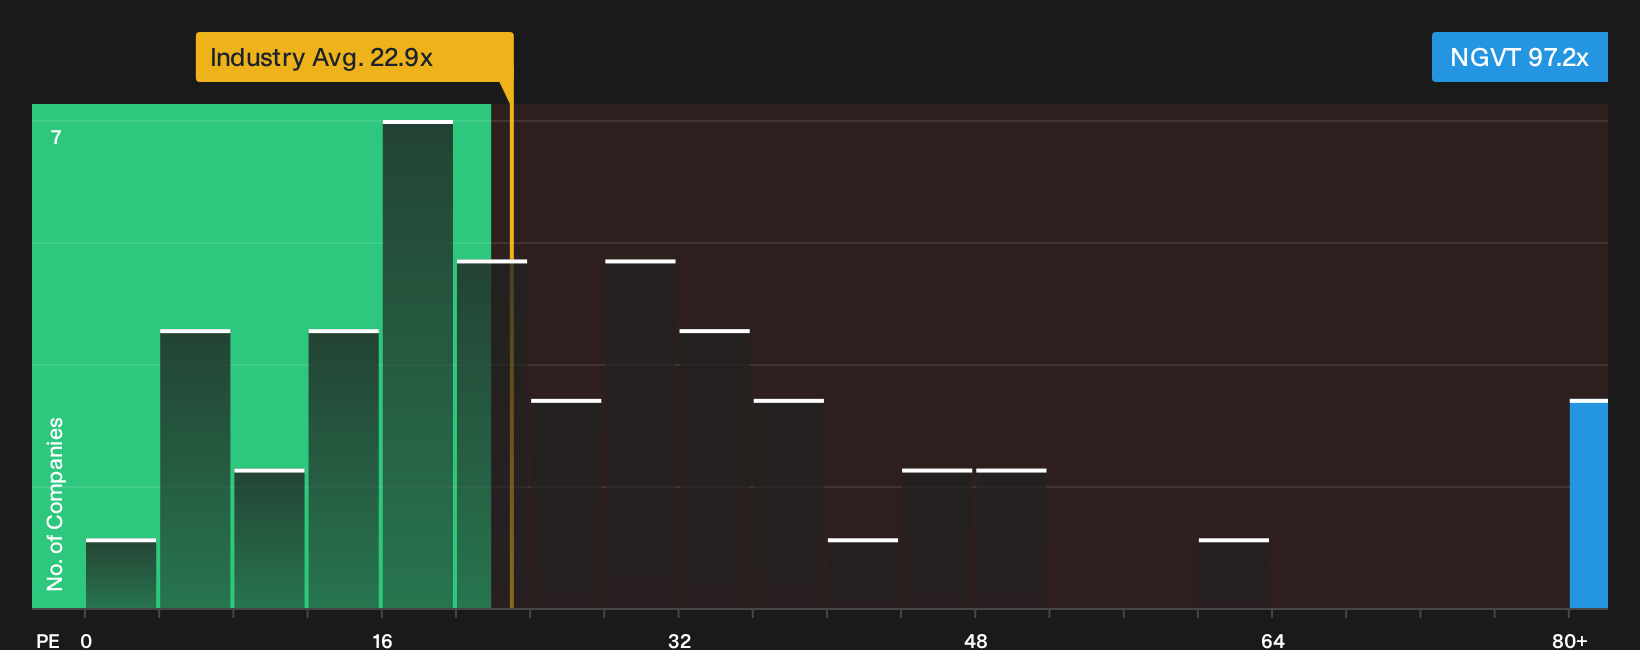
The P/E ratio works well for Ingevity because earnings are a key lens for a chemicals producer with an established business model. At about 97.2x earnings, the stock trades far above the Chemicals industry average P/E of roughly 22.9x and also well ahead of the peer group around 26.2x. That kind of gap means investors are paying a high price today for each dollar of current profit.
A more tailored benchmark that adjusts for Ingevity’s own growth profile, margins, size and risk points to a lower P/E as a reasonable anchor. This places the current multiple on the expensive side of that range. For anyone looking at the ticker around US$71.27, the key question is whether the company’s earnings quality and future prospects make that premium sensible or whether the valuation has stretched too far on this metric alone. Explore the numbers behind Ingevity's P/E valuation.
The Ingevity Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ingevity extend the valuation puzzle by spelling out which assumptions on growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today's price, and they sit on the Community page. Each scenario links a fair value view to a particular mix of potential catalysts and risks so you can track over time which version of Ingevity's story is actually unfolding.
One of the top community narratives on Ingevity: 20% undervalued
"Substantial investments in innovation and engineered additives, especially in applications such as EV battery materials and process purification, position Ingevity to capture new demand..."
Discover why this Narrative puts Ingevity at 20% undervalued.
The Ingevity share price is only one piece of the decision
Before treating Ingevity as a straightforward valuation story, it is worth knowing that Simply Wall St’s broader checks have picked up potential concerns that deserve a closer look from you. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com