
Will Index Reshuffle Change Illumina (ILMN) Narrative
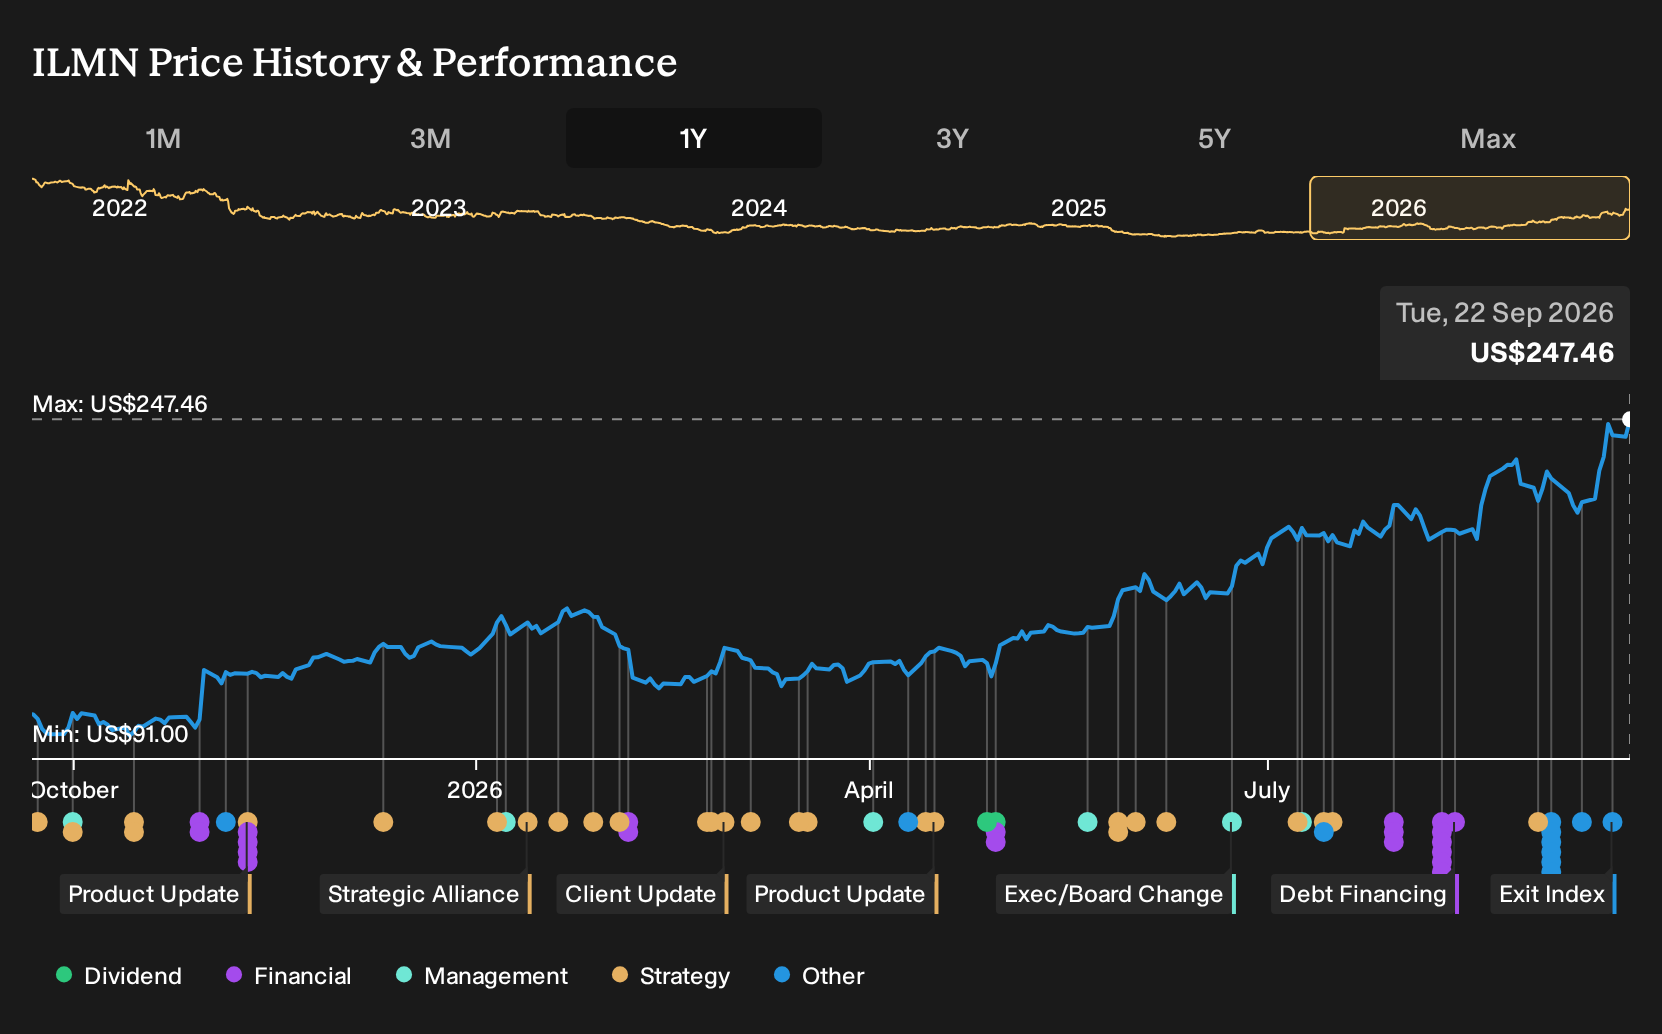
- Illumina, Inc. was recently added to the S&P 500 Equal Weighted Index and removed from the Russell Small Cap Comp Value Index, prompting index-related trading as investors realigned portfolios.
- The shift from a small cap value benchmark to a broad equal weighted large cap index changes how Illumina fits into asset allocation frameworks and could affect how funds size their exposure to its clinical genomics and sequencing business.
- Investors will now be able to observe how Illumina's investment narrative develops in the context of its inclusion in the S&P 500 Equal Weighted Index.
Scan how Illumina's index reshuffle compares with other potential re-raters by checking a hand picked mix of 29 high quality undervalued stocks that may appeal to the same type of investor focus.
Illumina Investment Narrative Recap
To hold Illumina, you need to believe its sequencing platforms and consumables can keep gaining clinical share while research demand and China exposure stay manageable. The most important near term swing factor remains execution around clinical genomics volumes and consumables mix, where recurring usage can offset softer academic and Chinese demand.
The recent index reshuffle looks more mechanical than fundamental. It does not change Illumina's reliance on clinical applications or its exposure to research funding and export controls. The bigger risk for you to watch is pressure on pricing and margins as competition intensifies and next generation sequencing technology continues to commoditize.
The move into the S&P 500 Equal Weighted Index is the announcement that links most directly to this episode. Inclusion can pull Illumina further into the core holdings list for diversified large cap mandates. This may increase attention on consistency of execution in its clinical and oncology segments rather than shorter term trading swings.
Index removal on the small cap value side matters more for who holds the stock than how the business runs day to day. The practical watchpoint is whether this broader large cap peer set leads investors to put greater weight on current P/E levels, the recent step down in profit margins from 28.8% to 18.3%, and the pace of earnings growth that analysts currently expect at 12.3% a year.
Illumina's current earnings of US$824.0 million are set against analyst forecasts that point to US$5.5b in revenue and US$1.1b in earnings by 2029. This implies 7.0% yearly top line growth and an earnings increase of about US$276.0 million if the consensus view plays out.
Uncover why Illumina's fair value indicates a 19% potential downside to its current price, resulting in a valuation premium that leaves little room for error.
Exploring Other Perspectives
One alternate angle to watch is legal and cost pressure rather than index mechanics. The most cautious Illumina analysts were working off roughly US$5.3b of revenue and US$1.1b of earnings by 2029 before this index reshuffle. Their view is that margin strain and legal risks justify a much lower P/E. Your take on today’s news could push you closer to or further from that camp.
Explore 3 other Illumina fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Illumina research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Illumina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Illumina's overall financial health at a glance.
Looking For More Investment Ideas Beyond Illumina?
If the Illumina story has sharpened your thinking about risk, valuation, and balance sheet strength, it can be useful to compare it with a wider field of companies using the Simply Wall St Screener.
- For investors who care most about quality at a reasonable entry point, consider reviewing a 29 high quality undervalued stocks that combines strong fundamentals with pricing that may still be catching up.
- If capital preservation and financial resilience sit at the top of your checklist, scan a list of solid balance sheet and fundamentals (23 results) to see which businesses carry less debt and more shock absorbers.
- When you want to broaden your watchlist with less widely followed ideas, run through a 16 high quality undiscovered gems that surfaces quieter companies with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com