
What Rockwell Automation Shares' Project Glasswing Move Means For Shareholders
- On 15 September 2026, Rockwell Automation, Inc. joined Anthropic’s Project Glasswing, gaining controlled access to Claude Mythos 5 to support vulnerability discovery, validation, prioritization, and remediation across industrial software and connected manufacturing systems.
- This collaboration aligns Rockwell Automation’s cybersecurity work with a global group of critical infrastructure providers, reinforcing how security capabilities are becoming part of the operating backbone for its connected industrial automation offerings.
- We will now look at how Rockwell Automation’s investment narrative is influenced by its Project Glasswing work on industrial cyber resilience.
Scan Rockwell Automation’s peers tackling similar cyber risks and see which ones your process flags first with our curated list of 95 robotics and automation stocks.
Rockwell Automation Investment Narrative Recap
To own Rockwell Automation, you need to believe that demand for industrial automation, software and connected systems keeps converting into orders across its Intelligent Devices, Software & Control and Lifecycle Services segments. The Glasswing news sits mainly in the Software & Control and cybersecurity layer and looks additive, but not a clear swing factor for near term orders on its own.
The more immediate upside catalyst remains execution on the existing project pipeline in North America, software deployments such as Plex and disciplined pricing. The biggest near term risk still sits with delayed customer capex and softer recurring Lifecycle Services. Glasswing should help product resilience over time, rather than change those demand and cost pressures quickly.
The Glasswing announcement fits alongside Rockwell Automation’s broader push into AI enabled automation such as Plex QMS with FactoryTalk VisionAI and TechConnectIQ remote support. Both Glasswing and these offerings point to a tighter link between cyber resilience, remote monitoring and software centric automation, which matters most for the higher margin Software & Control mix.
For catalysts, the interesting angle is how these AI offerings and security work could support recurring services and software attached to new hardware projects. The risk side is that weaker recurring Lifecycle Services growth in Q3 2026 and inflation in components still weigh on margins, so investors will likely watch whether these digital and cybersecurity efforts translate into steadier ARR and pricing power over time.
Rockwell Automation's narrative projects US$10.5b revenue and US$1.9b earnings by 2029. This assumes 5.3% yearly revenue growth and an earnings increase of about US$700m from US$1.2b today.
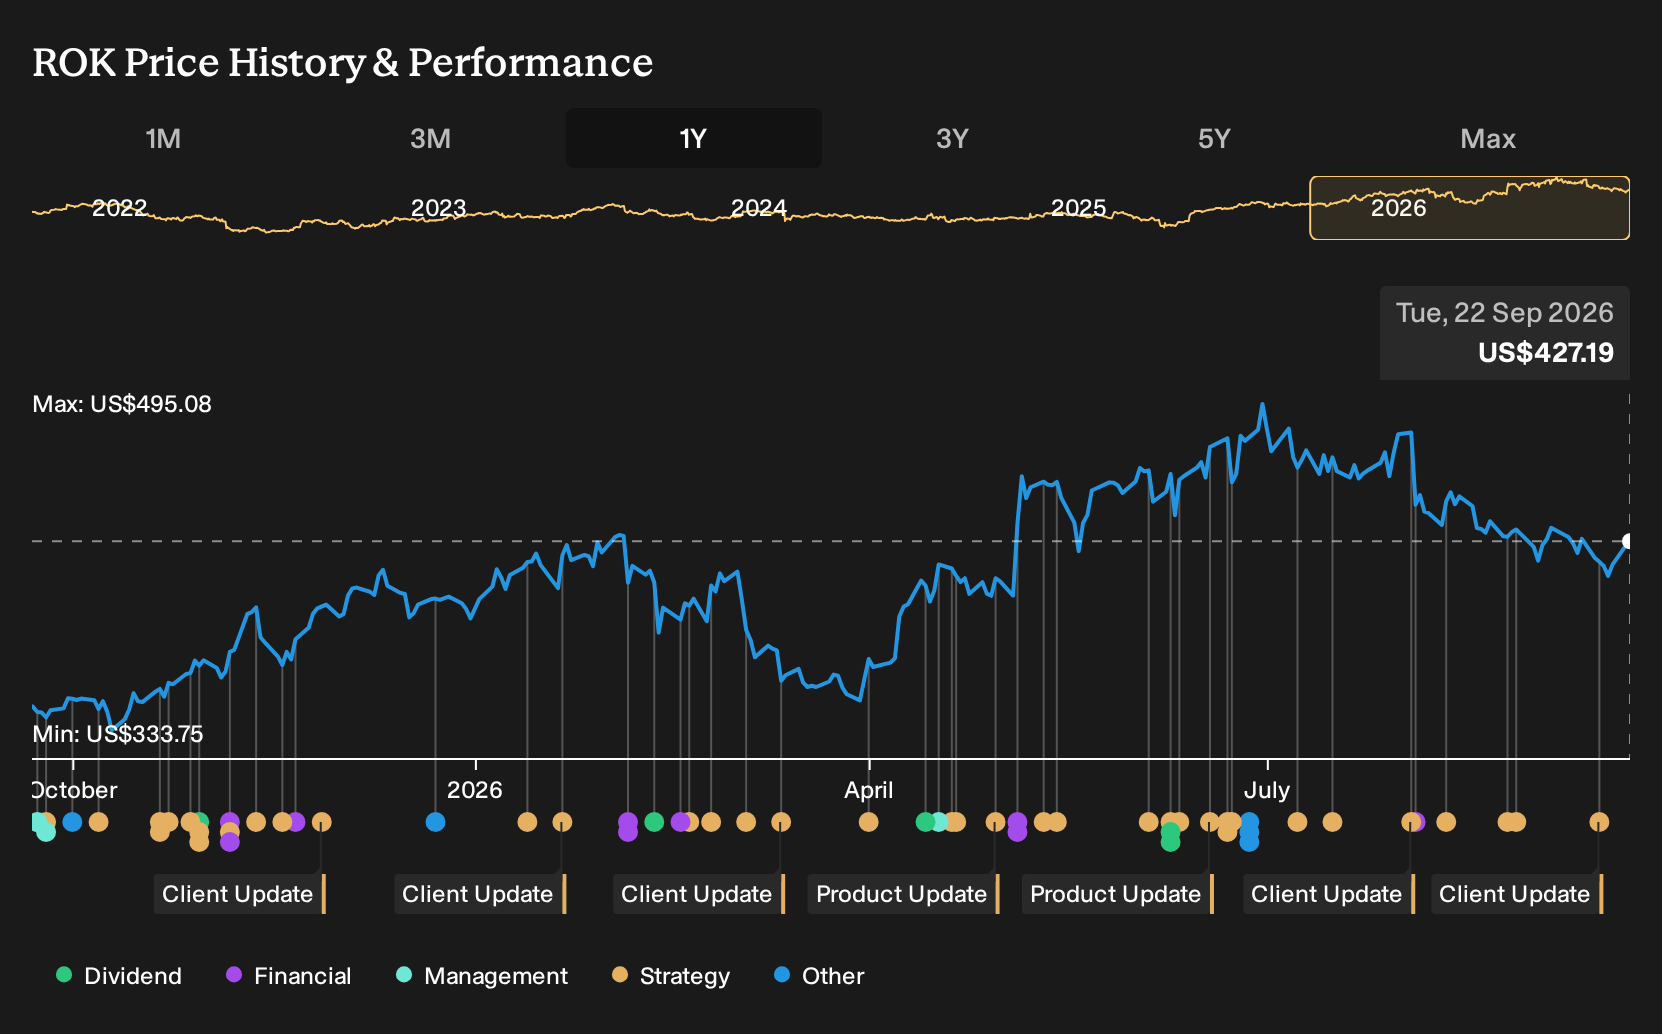
Uncover why Rockwell Automation's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Rockwell Automation’s Project Glasswing work as a potential accelerator for recurring digital revenue. Before this news, that bullish camp was already sketching out about US$10.9b of revenue and US$2.1b of earnings by 2029. You might see those numbers and wonder whether this cybersecurity push nudges forecasts even higher or simply reshapes where that future income comes from. Either way, opinions already span a wide range, so it is worth exploring several viewpoints before deciding how this new development fits your own thesis.
Explore 2 other Rockwell Automation fair value estimates, including one that suggests up to 12% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rockwell Automation research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rockwell Automation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rockwell Automation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rockwell Automation?
If Rockwell Automation has sharpened your focus on quality, it can help to line it up against other listed businesses that share some of the traits you care about most. The Simply Wall St Screener lets you move from a single ticker to a short list of candidates that fit your filters, so you can compare fundamentals side by side instead of relying on headlines.
- If capital preservation sits high on your list, start by scanning 30 resilient stocks with low risk scores that our filters flag for relatively resilient profiles and fewer red flags on key risk metrics.
- For investors hunting for what might be mispriced quality, broaden the field with a curated pool of 29 high quality undervalued stocks that pair stronger fundamentals with valuations that screen below fair value estimates.
- Anyone looking to back sturdier balance sheets can quickly narrow the universe using a list of solid balance sheet and fundamentals (23 results) that screens for companies with cleaner debt profiles and more robust financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com