
Comer Industries (BIT:COM) Could Be 19% Below Fair Value After $65 Million Plant Overhaul
Comer Industries (BIT:COM) just finished a multi year, $65 million overhaul of its Loves Park plant, creating a flagship U.S. hub that consolidates operations and increases manufacturing capacity.
The €47.5 share price has edged higher in recent weeks, with a 4.17% 1 month share price return hinting at gradually improving momentum. The 34.82% 1 year total shareholder return and 74.33% 3 year total shareholder return suggest longer term investors in Comer Industries have already seen substantial gains.
Scan for other industrial manufacturers pursuing similar capacity builds and U.S. expansion stories by reviewing our curated list of 40 power grid technology and infrastructure stocks.
Comer Industries now has a larger U.S. footprint and a share price that has already rewarded holders. The real tension is whether that €47.5 tag still offers sensible value or now asks too much.
Price-to-Earnings of 19.1x: Is it justified?
On current numbers, Comer Industries changes hands at a P/E of 19.1x, which screens as inexpensive compared with both peers and the wider machinery group described in the data.
The P/E ratio compares the share price with earnings per share and gives you a shorthand way of seeing how much investors are paying for each euro of profit. For a manufacturer like Comer Industries, where earnings can be tied to industrial cycles and capital spending, this measure often anchors how the market weighs the durability of its profit stream.
Here, the multiple sits below the peer average P/E of 29.7x and also below the European machinery industry average of 20.7x, indicating a valuation gap. The firm is also described as trading at good value relative to an estimated fair P/E of 20.1x. This is a level the market could plausibly move toward if its earnings profile and forecasts remain intact.
Explore the SWS fair ratio for Comer Industries.
Result: Price-to-Earnings of 19.1x (UNDERVALUED)
Still, the €1.36b market value and reliance on both agricultural and industrial demand leave Comer Industries exposed if equipment orders or large customer projects slow.
Find out about the key risks to this Comer Industries narrative.
Another View on Comer Industries’ Value
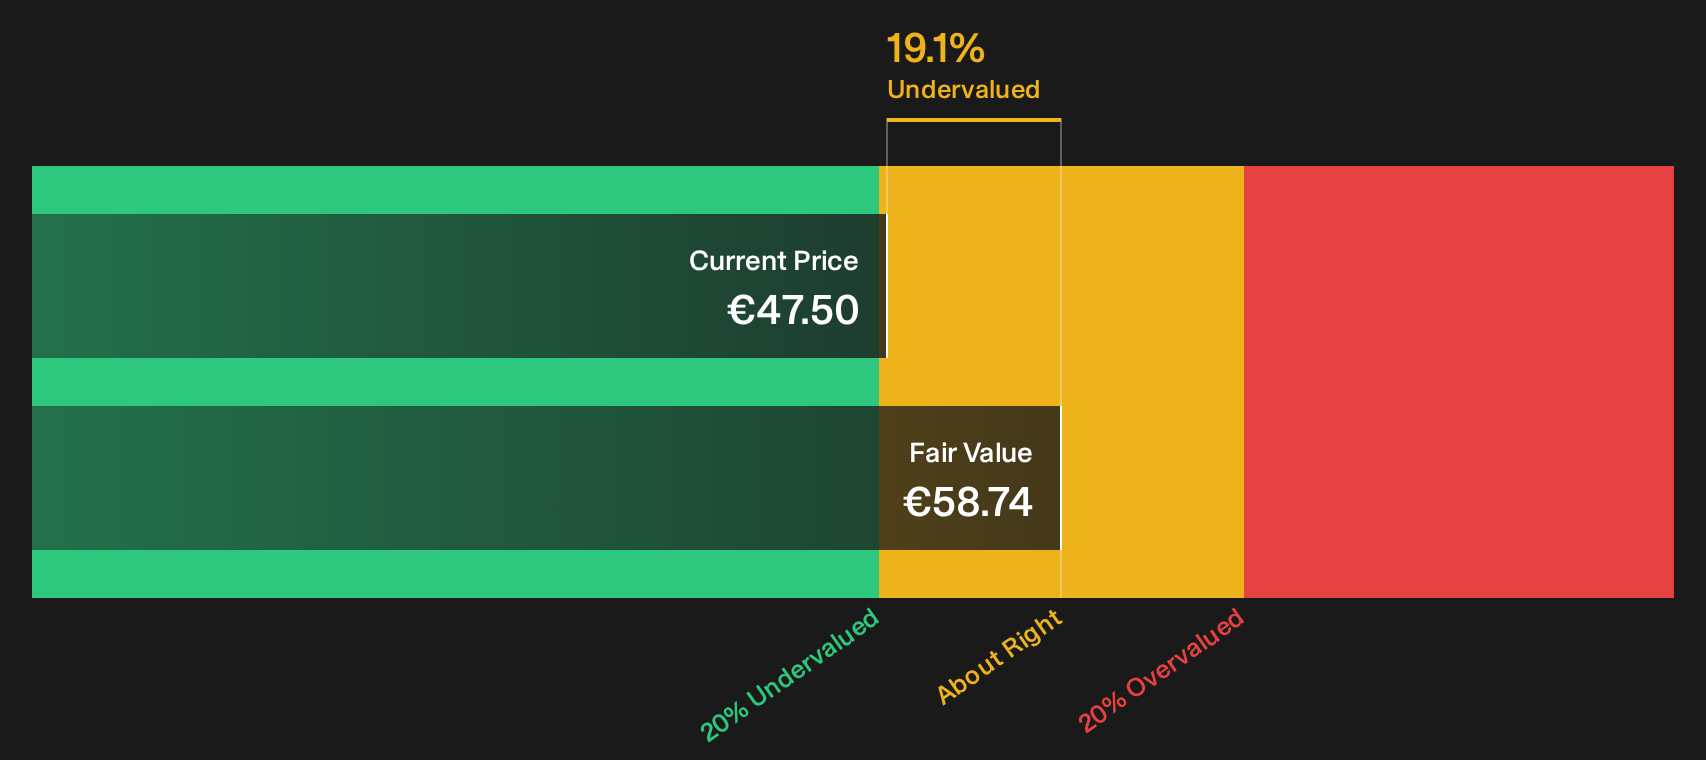
The P/E points to Comer Industries looking inexpensive, yet the SWS DCF model paints an even stronger picture. At €47.5, the share price sits 19.1% below an estimated future cash flow value of €58.74, which also aligns with the separate DCF based fair value flag.
Both methods point in the same direction, which reduces the chance this is just a quirk of one model. It raises a different question for you as an investor. If the cash flow view also leans toward undervalued, what risk or timing issue might still be keeping some buyers on the sidelines?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Comer Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 171 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or opportunity, the only way to square Comer Industries’ risks with its potential upside is to look at the detail yourself and decide quickly where you stand. Start by weighing its 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Comer Industries?
Once you have a view on Comer Industries, widen your lens and use targeted stock lists to pressure test your thesis and uncover fresh opportunities.
- Zero in on potential mispricings by scanning a curated pool of 171 high quality undervalued stocks that pair quality fundamentals with attractive entry points.
- Build a portfolio with staying power by evaluating a list of solid balance sheet and fundamentals (198 results) that can better handle economic shocks and financing pressure.
- Get ahead of the crowd by reviewing 619 high quality undiscovered gems that combine strong financial profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com