
Is MercadoLibre (MELI) Still Worth A Look After Its Ad Engine Gains Share?
MercadoLibre (MELI) recently highlighted its fast growing ad engine, with updates indicating it now accounts for more than 10% of Latin America’s digital advertising market.
Recent trading tells a mixed story for MercadoLibre. The share price is around US$1,826, with the 90 day share price return up 10.1% even though the year to date share price return is down 7.5%, while the 1 year total shareholder return has declined 26.8% against a 44.0% gain over three years. That pattern suggests momentum has cooled over the past year even as long term holders still sit on gains, and fresh headlines about the ad engine, strong free cash flow generation and the new US$1.0b 2036 senior notes are giving investors more information to reassess both growth potential and risk.
Extend your thinking beyond MercadoLibre and scan a hand picked 29 high quality undervalued stocks that combine strong fundamentals with potential mispricing in the current market.
That recent swing in MercadoLibre now sits between two stories. Is the price starting to better reflect the cash generation and ad traction, or is sentiment just resetting after a hot few years?
Most Popular Narrative: 43% Undervalued
MercadoLibre is trading at around $1,826, while the widely followed narrative fair value sits at $3,200, so the gap between price and story is wide and very explicit.
"Because after spending months studying this company, I think I have finally learned what MercadoLibre’s real trick is. It is not e-commerce. It is not fintech. It is not credit. It is making each customer more valuable to every other part of the machine. The shopper gives Mercado Pago another user. Mercado Pago gives Credit another borrower. Credit gives Commerce another purchase. Commerce gives Advertising another impression. Advertising attracts another merchant. The merchant gives the shopper another reason to return."
See why 137 investors see MercadoLibre as 43% undervalued.
Result: Fair Value of $3,200 (UNDERVALUED)
Still, the MercadoLibre story can break if credit quality weakens as the loan book expands or if fintech margins land well below those modeled assumptions.
Find out about the key risks to this MercadoLibre narrative.
Another View on MercadoLibre’s Valuation
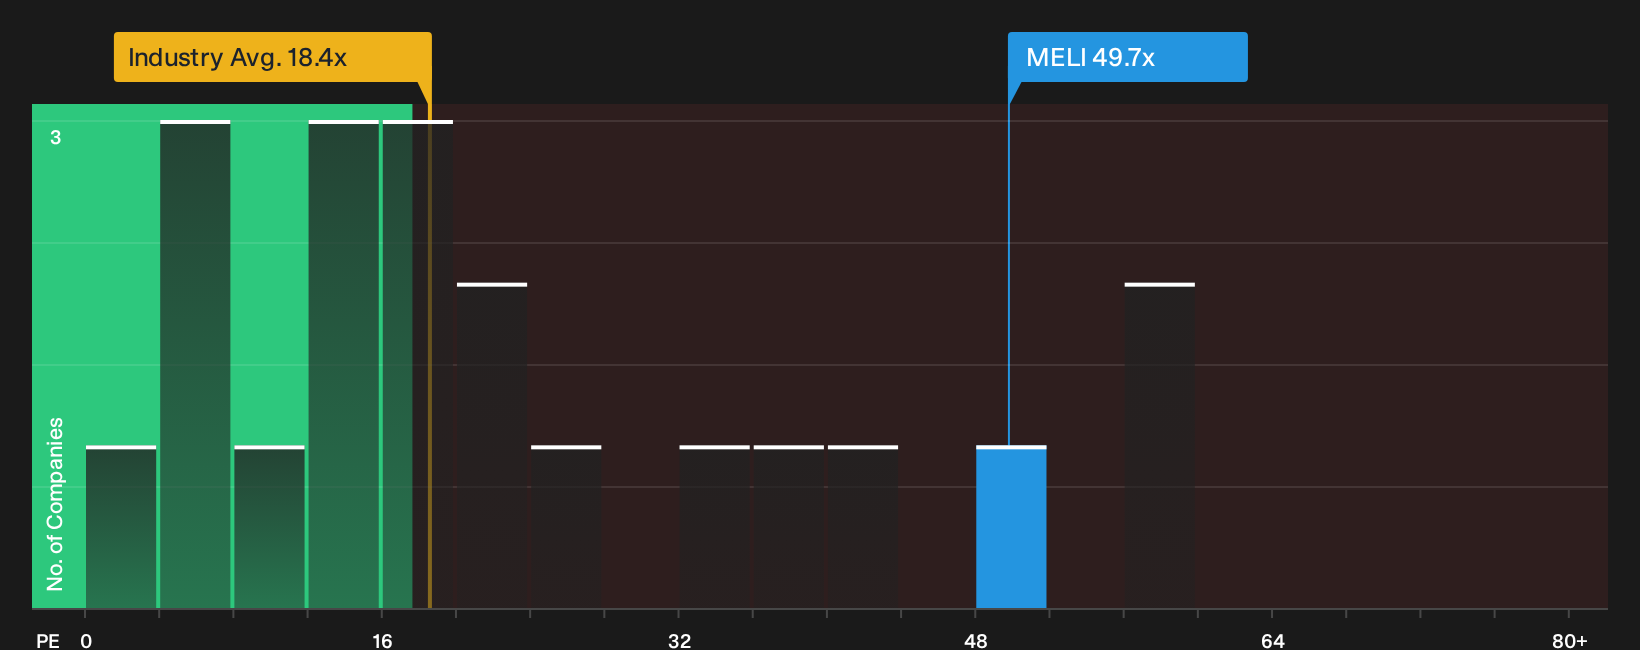
The story looks different once you step away from the narrative fair value and look at plain earnings multiples. MercadoLibre trades on a P/E of 49.7x, compared with 21.5x for peers and a fair ratio of 36.2x that our work suggests the market could drift toward over time.
That gap implies investors today are paying a much richer price than both the sector and the modeled fair ratio, which raises a simple question for anyone watching MELI closely. Is the premium a reasonable price for growth, or is it extra valuation risk that only makes sense if everything goes right from here?
To see how the earnings-based view stacks up against other valuation angles, including growth and balance sheet context, See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual read on how MercadoLibre’s P/E compares with its industry and where that premium currently sits, see
Next Steps
Sentiment on MercadoLibre is mixed, with both clear concerns and positive aspects in the data. Consider acting promptly and review the full picture for yourself by checking the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond MercadoLibre?
If MercadoLibre has sharpened your focus on quality, do not stop here. Use the screener to quickly surface fresh opportunities that fit your risk and return preferences.
- Target resilient payouts by zeroing in on 7 dividend fortresses that can help anchor your portfolio with income-focused opportunities.
- Hunt for potential mispricings through a 16 high quality undiscovered gems that filters for quality businesses the market may be overlooking.
- Dial down portfolio stress by concentrating on 30 resilient stocks with low risk scores that aim to pair steadier fundamentals with fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com